TL;DR
Cloud-based payroll software can automate calculations, approvals, payslips, filings, direct deposits, and recurring deductions. It does not automatically provide global employment infrastructure or transfer legal responsibility to the vendor. We recommend evaluating platforms by worker type, country coverage, compliance ownership, exception handling, integrations, security, implementation support, and total cost—not dashboard features alone.
Table of contents
- TL;DR
- Table of contents
- What is cloud-based payroll software, and what does it handle?
- The four payroll operating models: which one fits?
- Cloud payroll vs. EOR, PEO, and contractor payment platforms
- International payroll compliance: what software cannot decide
- Essential cloud payroll features for stronger control
- What cloud payroll really costs
- Integrations and controls for variable, high-volume workforces
- How to evaluate security, implementation, and vendor accountability
- FAQ
- Evaluate your payroll operation with real workforce data
Moving payroll to the cloud does not automatically make it compliant. Most products can automate calculations. Far fewer handle the legal employer relationship, local registration, tax filing, worker classification, and payment obligations behind those calculations.
The distinction becomes clear when payroll is almost due and late timesheets, invalid bank records, or changed earnings create exceptions. A capable platform should show what changed, who approved it, how net pay was affected, and whether unaffected payments can proceed.
If it cannot, the software may be storing payroll information rather than helping the business control payroll.
What is cloud-based payroll software, and what does it handle?
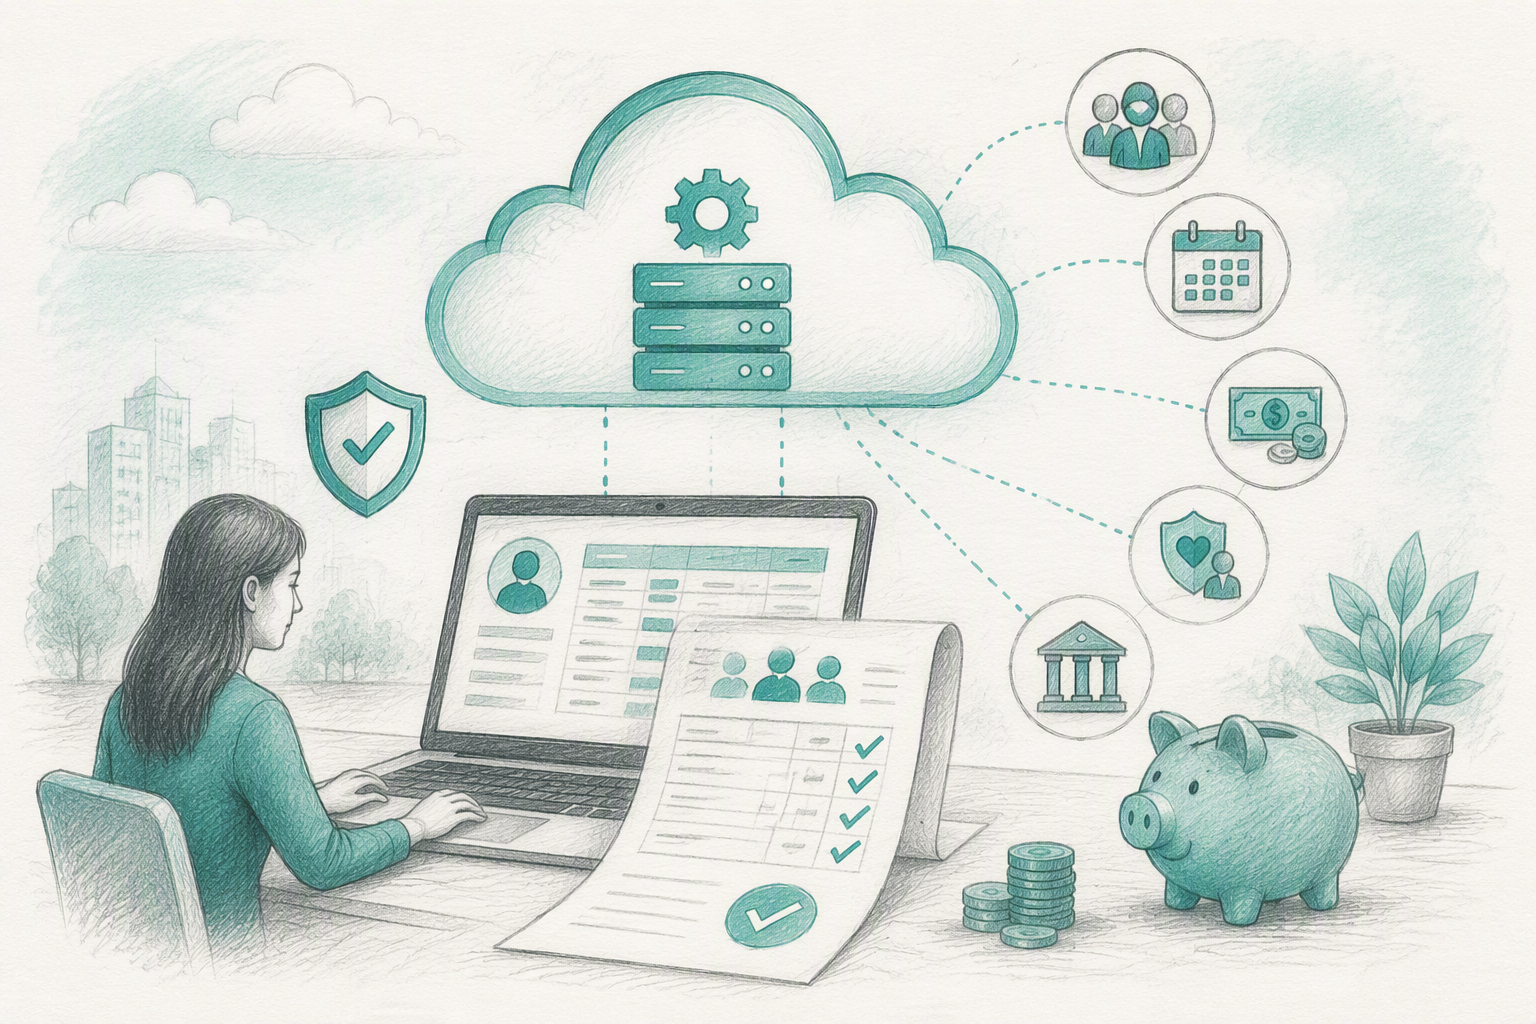
Cloud-based payroll software is an internet-accessed system for collecting payroll inputs, calculating earnings and deductions, routing approvals, generating payslips, preparing filings, initiating payments, and retaining payroll records. Authorized users can generally access it through a browser or connected application rather than relying on software installed on a particular computer.
A typical payroll run begins with worker records and approved time or earnings data. The platform applies configured rates, tax settings, benefits, deductions, reimbursements, overtime rules, and other pay components to calculate gross-to-net pay.
A complete workflow may involve:
- Collecting worker, compensation, time, leave, expense, and banking data.
- Validating required fields and flagging unusual or incomplete records.
- Calculating gross pay, taxable earnings, deductions, taxes, and net pay.
- Routing exceptions and payroll totals for review.
- Recording approval and confirming funding.
- Preparing or submitting required payroll and tax filings.
- Paying workers, authorities, benefit providers, or local partners.
- Delivering payslips and payment confirmations.
- Posting payroll results to accounting systems.
- Reconciling inputs, calculations, funding, filings, and payments.
Not every product performs every step. Some online payroll systems calculate pay but leave filings and payments to the customer. Others connect with local providers. An international platform may combine payroll software with employer of record services, contractor payments, local support, or payment infrastructure.
That is why there is no universal answer to “What software should we use for payroll?” The right choice depends on:
- Whether workers are employees, contractors, agency workers, or a mix.
- Where those workers perform their services.
- Where the business has legal entities and employer registrations.
- The currencies, pay schedules, earning types, and integrations involved.
- Whether the company has internal payroll, tax, HR, finance, and legal expertise.
- Who files returns, funds payroll, responds to notices, and corrects errors.
- How often the payroll team handles off-cycle changes and other exceptions.
A domestic business with salaried employees in one jurisdiction may need only local payroll software. A startup hiring across several countries without local entities may require a mix of local payroll, employer of record arrangements, and contractor workflows.
Cloud-based does not automatically mean global
“Cloud” describes how software is delivered. It does not describe the legal infrastructure supporting payroll.
Depending on the service, the customer may still need to:
- Establish a local legal entity.
- Register as an employer.
- Obtain payroll or tax identification numbers.
- Open or fund a suitable bank account.
- Select and manage an in-country payroll provider.
- Submit local filings or appoint a tax agent.
- Review permanent establishment exposure.
- Determine whether each worker is classified correctly.
“Global coverage” may mean that a platform can send money to a country. It does not necessarily mean the provider can legally employ someone there or complete every required filing. Contractor payment coverage also does not prove that the underlying engagement is compliant.
We recommend requesting a country-by-country service schedule. It should identify supported worker types, entity requirements, calculation responsibilities, filing ownership, payment processes, and tasks that remain with the customer.
For example, a startup may employ staff in countries where it has registered entities, use an EOR elsewhere, and engage genuine independent contractors in other markets. One interface can support these groups, but the legal relationships underneath remain different.
How a cloud payroll run should work
A reliable payroll run starts with controlled data collection. Worker records, approved hours, compensation changes, leave, expenses, benefits, and deductions should arrive through defined integrations or standardized imports—not scattered emails and uncontrolled spreadsheets.
Validation should happen before calculation. The platform should flag issues such as missing tax identifiers, duplicate records, invalid bank details, unexpected hours, negative net pay, or unusual changes from the previous period.
The calculation preview should clearly present:
- Gross and taxable earnings.
- Employee taxes and deductions.
- Employer taxes and contributions.
- Benefits and statutory costs.
- Net pay by worker.
- Funding totals by entity, country, and currency.
- Changes from the previous payroll.
- Exceptions requiring review.
After approval, the system should preserve the calculation version, approver, timestamp, source data, and later changes. Filings, funding, payments, payslips, and accounting entries should remain traceable to the approved run.
A polished dashboard cannot repair fragmented source data. If hours live in one spreadsheet, rate changes sit in email, and bank details are stored in another portal, the dashboard may only display unreliable information faster.
The four payroll operating models: which one fits?
We use four practical operating models when assessing payroll: in-house processing, an outsourced payroll bureau, local payroll software, and a global payroll platform. These are not strict legal categories, and businesses often combine them.
| Operating model | Internal workload | Control | Cross-country scalability | Typical responsibility |
|---|---|---|---|---|
| In-house processing | High | High | Limited by internal resources | Primarily internal |
| Outsourced payroll bureau | Moderate | Moderate | Depends on the bureau network | Shared by contract |
| Local payroll software | Moderate | High | Usually country-specific | Primarily customer |
| Global payroll platform | Low to moderate | Moderate to high | Depends on actual coverage | Varies by provider |
In-house processing gives the business direct control over payroll data, calculations, approvals, and filings. It also requires trained staff, maintained tax configurations, documented processes, and adequate cover during absences or turnover.
An outsourced payroll bureau performs some or most payroll work as a managed service. The customer may still collect inputs, approve calculations, fund payroll, maintain registrations, and retain legal responsibility.
Local payroll software can work well when the company already has the necessary entities and local expertise. Using separate products in each market, however, can fragment data and create inconsistent controls.
A global payroll platform provides a common operating layer across countries. Depending on the provider, it may coordinate local vendors, use its own payroll infrastructure, offer employer of record services, or process contractor payments.
Operational complexity matters more than headcount alone. A small team spread across several jurisdictions can create more payroll work than a much larger workforce in one location.
Vendor comparisons should therefore focus on fit and responsibility. Our practical international payroll platform for founders is designed around actual countries, worker relationships, and payroll processes rather than treating every workforce as a uniform list of payees.
Cloud payroll compared with desktop software, spreadsheets, and bureaus
Cloud payroll can improve remote access, version control, audit logging, and centralized updates compared with desktop software. Business continuity still depends on vendor availability, access controls, backups, and recovery procedures.
Desktop software may provide local control but complicate upgrades, backups, remote access, and collaboration. Once files are copied between users, proving which version produced the final payroll becomes difficult.
Spreadsheets remain useful for controlled imports, variance analysis, allocations, and reconciliations. They become risky when used as the main system of record without protected formulas, approval logs, version controls, or reliable links to worker data.
Payroll bureaus can add valuable expertise and processing capacity. Problems arise when the customer must manage different formats, deadlines, funding requirements, contacts, and correction procedures in every country.
Cloud software should reduce that coordination burden. If it simply places separate local processes behind one login, much of the difficult work remains with the customer.
How to interpret branded payroll searches
A well-known brand does not remove the need for detailed assessment. Sage Cloud Payroll, for example, is a branded cloud payroll offering, but buyers must still investigate its relevant country support, entity requirements, filing responsibilities, integrations, worker types, support commitments, and exception workflows.
Similarly, asking who a large provider’s biggest competitor is offers little guidance. Vendor size does not determine whether a platform supports a particular entity structure, jurisdiction, payroll calendar, integration, or compliance requirement.
We recommend comparing:
- Directly supported countries and worker types.
- Owned infrastructure and third-party involvement.
- Contractual responsibility for calculations and filings.
- Entity and employer-registration requirements.
- Correction and exception workflows.
- Implementation work and service commitments.
- Complete costs, including foreign exchange and transaction fees.
A focused comparison is useful when it examines operating details. Our platform comparison framework looks beyond headline feature lists to the practical differences founders should investigate.
Cloud payroll vs. EOR, PEO, and contractor payment platforms
Payroll software, employer of record services, professional employer organizations, and contractor payment platforms solve different problems.
Payroll software calculates and administers payroll for workers employed by the customer or another identified legal employer. The software generally does not change who employs the worker or carries employment liability.
An employer of record, or EOR, becomes the worker’s legal employer in the relevant jurisdiction while the client directs day-to-day work. The EOR commonly manages the employment contract, payroll, withholding, statutory contributions, and certain local employment obligations.
A professional employer organization, or PEO, commonly works through a co-employment arrangement. Structures vary by jurisdiction, and the customer may need an eligible local entity.
A contractor payment platform helps onboard and pay independent contractors. It may collect agreements, invoices, tax documents, and banking information, but it cannot turn an employee-like relationship into an independent business relationship.
| Model | Legal employer | Payroll and filings | Main risk holder |
|---|---|---|---|
| Payroll software | Customer or another existing employer | Customer, provider, or payroll partner | Primarily the legal employer |
| EOR | EOR entity | Usually the EOR or its partner | Allocated by law and contract |
| PEO | Usually the customer within a co-employment structure | Shared or administered by PEO | Shared or contractually allocated |
| Contractor platform | No employer if classification is valid | Invoicing and payment support | Customer retains classification risk |
A distributed business may use several models. It might run payroll where it has entities, use an EOR in selected countries, and pay valid independent contractors elsewhere.
Employee payroll and contractor payments are different workflows
Employee payroll can involve withholding, employer contributions, statutory benefits, leave entitlements, minimum wage, overtime, payslip rules, filing calendars, and termination obligations.
Contractors generally invoice for services and manage more of their tax affairs, subject to local law. Their workflow may focus on tax documentation, statements of work, milestone approval, currency conversion, and accounts-payable controls.
Choosing a contractor workflow because it appears quicker or cheaper creates risk when the working relationship resembles employment. Relevant factors may include control, exclusivity, economic dependence, working hours, equipment, substitution rights, and integration into the business.
Automation can scale this problem. Rapidly onboarding and paying misclassified contractors does not reduce compliance exposure; it spreads the underlying error.
We recommend reviewing classification during onboarding and again when responsibilities change. Our guide to paying international contractors explains the operational steps without treating payment capability as proof of correct classification.
When an EOR may remove the immediate need for a local entity
An EOR may allow a business to hire an eligible employee in a country where it lacks its own entity. The worker enters a local employment contract with the EOR, while the client manages day-to-day work under a separate service agreement.
This can reduce the administration associated with forming an entity, registering as an employer, creating local payroll operations, and managing statutory benefits. Not every role, activity, or country will be suitable.
Before selecting an EOR, verify:
- The identity of the legal employer.
- Employment contract requirements.
- Intellectual property and confidentiality protections.
- Statutory and supplemental benefits.
- Leave, expense, and bonus treatment.
- Probation, termination, notice, and severance procedures.
- Permanent establishment implications.
- Data-processing and cross-border transfer terms.
Our guide to how an employer of record works provides a fuller explanation of the structure and the responsibilities involved.
International payroll compliance: what software cannot decide
International payroll compliance starts before the calculation engine runs. A business may need a local entity, employer registration, payroll account, tax identification number, social insurance registration, insurance coverage, or other local setup.
Ongoing obligations can include:
- Income tax withholding.
- Employee and employer social contributions.
- Statutory benefits and leave payments.
- Minimum wage and overtime compliance.
- Compliant payslips.
- Periodic and year-end filings.
- Payments to tax and social authorities.
- Record retention and inspection support.
Permanent establishment risk is separate from payroll registration. Hiring or directing workers in another country may create corporate tax concerns depending on their activities, authority, location, and local law. Payroll software cannot make that legal determination. Qualified legal or tax advisers should review it.
Providers may calculate payroll and prepare filings, but buyers still need to identify who is legally and contractually accountable. A statement that a platform “supports compliance” is less useful than a responsibility matrix showing who performs each task.
That matrix should cover:
- Required entities and registrations.
- Data supplied by the customer.
- Calculations performed by the provider or local partner.
- Returns prepared, reviewed, and submitted.
- Payroll and tax funding responsibilities.
- Filing and payment deadlines.
- Completion evidence.
- Ownership of notices, amendments, and penalties.
Classification must come before automation
Worker classification depends on the substance of the relationship, not the label used in a contract or platform.
Relevant factors may include:
- Who controls how the work is performed.
- Whether the individual sets their schedule.
- Whether the worker serves other clients.
- The degree of economic dependence.
- Who provides tools and equipment.
- Whether the worker can subcontract.
- How the worker is paid.
- Their integration into core operations.
- The expected duration and exclusivity of the relationship.
- Who carries commercial risk.
Tests differ by country, so one questionnaire cannot guarantee the same outcome everywhere.
Relationships also change. A contractor may start with a limited project but later work fixed hours, report to a manager, use company equipment, and depend on one client.
We recommend reviews whenever hours, duties, supervision, exclusivity, compensation, location, or contract length changes. The system should preserve the evidence, decision, reviewer, and follow-up date.
Ask who is liable when payroll goes wrong
Payroll contracts should explain what happens when a provider submits a late filing, miscalculates wages, sends funds to the wrong destination, or misses a correction deadline.
Request terms covering:
- Provider-caused penalties and interest.
- Error acknowledgement and resolution times.
- Amended filing procedures.
- Failed or rejected payments.
- Incorrect exchange rates or deductions.
- Tax authority notices.
- Service credits and remediation costs.
- Liability limits and exclusions.
- Customer actions that can shift responsibility.
A green dashboard status does not prove that a filing was accepted or a payment settled. Ask for authority receipts, filing confirmations, bank confirmations, and worker-level payment status.
Essential cloud payroll features for stronger control
The most useful cloud payroll features create control over calculations, approvals, filings, payments, and records.
We look for:
- Automated gross-to-net calculations.
- Configurable earning and deduction rules.
- Appropriate tax and contribution logic.
- Calculation previews and variance reports.
- Multi-level approvals.
- Digital payslips.
- Filing preparation and status tracking.
- Worker and authority payment tracking.
- Role-based access.
- Complete audit trails.
- Accounting exports or integrations.
- Controlled corrections and off-cycle workflows.
Standard demonstrations are usually clean. Real payroll is not. Bonuses arrive late, managers correct timesheets, employees leave unexpectedly, identifiers fail validation, and bank transfers are rejected.
A platform should preview calculations before approval and validate both individual records and the overall run. Useful checks include unexplained pay changes, missing fields, duplicate records, unusual overtime, invalid bank formats, and totals outside agreed tolerances.
When a worker questions net pay, payroll staff should be able to trace the result through approved hours, taxable earnings, deductions, exchange rates, payslips, and payment confirmation. That evidence is more useful than a generic “processed” label.
Exception handling is the real product test
We recommend testing vendors with imperfect scenarios:
- A late timesheet after draft calculations.
- Duplicate imported time records.
- A missing tax identifier.
- Negative net pay caused by deductions.
- Changed or invalid bank details.
- A retroactive compensation change.
- An urgent final payment.
- A late-approved bonus.
- A failed transfer.
- A reversal after funds are initiated.
The platform should isolate affected records without unnecessarily delaying valid payments. It should also show whether a change requires recalculation, reapproval, additional funding, an amended filing, or an off-cycle payment.
For variable workforces, the exception queue may be more valuable than the standard payroll screen. Teams need to process correct records while disputed hours, rates, or assignments remain under review.
Role-based approvals and defensible audit trails
Payroll access should follow separation-of-duties principles. One person should not automatically be able to enter data, change bank details, approve payroll, release funds, and remove evidence of those actions.
Permissions may cover data import, calculation, exception review, manager approval, final approval, funding authorization, payment release, system administration, and read-only audit access.
The audit trail should retain original and updated values, users, timestamps, approval decisions, calculation versions, supporting documents, filing status, and payment status. Changes after approval should trigger a visible workflow rather than silently altering the record.
What cloud payroll really costs
Cloud payroll cost rarely stops at the advertised subscription or per-worker rate. Pricing may also include:
- Country minimums and setup fees.
- Implementation and migration.
- Integrations.
- Foreign exchange spreads or markups.
- Wire and payment charges.
- Tax filing and year-end fees.
- Off-cycle payroll.
- Amended returns and corrections.
- Premium support.
- Compliance or classification add-ons.
Provider fees should be separated from employment costs. Employer taxes, social contributions, statutory benefits, insurance, leave, and payroll funding are not usually software charges, but they remain part of hiring costs.
A low headline price can become less attractive after exchange margins, payment fees, setup costs, and filing charges are included. Before comparing vendors, estimate employment expenses with an international employer cost calculator. Then compare provider charges separately.
A practical total-cost formula
Use the same workforce, currencies, calendars, and transaction assumptions for every proposal:
Total payroll operating cost = software and service fees + setup and integration costs + FX costs + payment charges + compliance add-ons + internal payroll labor
Estimate foreign exchange costs using expected payroll value, not only worker count. Also model normal payroll, corrections, country launches, year-end work, and workforce growth.
Internal labor belongs in the calculation. Include time spent collecting inputs, resolving exceptions, coordinating providers, approving runs, funding payroll, answering worker questions, and reconciling accounts.
Predictability matters alongside the modeled total. A transparent fee may be easier to manage than a low base price surrounded by variable exchange and transaction charges.
Pricing questions to put in the contract
Ask vendors to document:
- The exchange-rate source and applied margin.
- Whether that margin can change.
- The currency used for each fee.
- Transfer and payment-method charges.
- Failed payment and reversal fees.
- Country minimums and dormant-country charges.
- Setup, migration, and integration fees.
- Off-cycle and correction charges.
- Year-end document fees.
- Support costs.
- Contract minimums and price increases.
Provider-caused corrections should not generate additional charges for the customer.
Integrations and controls for variable, high-volume workforces
Payroll integrations can reduce duplicate entry and processing time, but they must preserve validation, approval, and reconciliation.
Common connections include time tracking, scheduling, accounting, HR, applicant tracking, banking, expenses, benefits, property management, and identity or tax-document verification.
A staffing business might import approved hours, separate regular and overtime earnings, route exceptions to operations, and preserve the approval history. A property manager may allocate labor by property and send approved costs to accounting.
The integration should reduce manual work without bypassing control. Automatically transferring incorrect hours only moves the error faster.
Controls for staffing and data-labeling companies
Staffing and data-labeling businesses often manage variable hours, changing projects, multiple rates, rapid onboarding, and large contractor populations.
Before calculation, validate:
- Worker identity and status.
- Work and payment countries.
- Entity, client, property, or project.
- Rate and effective date.
- Currency.
- Approved hours or completed units.
- Overtime and premium rules.
- Tax documentation.
- Bank or payment details.
- Duplicate or overlapping records.
Records with missing tax information, unresolved classification concerns, or rejected payment details should enter an exception queue. Valid records should continue through a controlled batch rather than waiting for unrelated issues.
Batch approval is useful only when worker-level visibility remains available. Managers should be able to exclude disputed records and document the reason.
Reconciliation matters more than sync badges
An integration badge shows that systems can exchange data. It does not prove that every record transferred correctly, only once, or into the right pay period.
Payroll teams should reconcile:
- Imported hours against source totals.
- Worker counts and identifiers.
- Rates and earning codes.
- Payroll registers against approved inputs.
- Funding requests against approved payroll.
- Bank confirmations against released payments.
- Tax payments against filed liabilities.
- Accounting entries against payroll registers.
- Worker-level net pay against payment results.
Require error logs, retry controls, duplicate detection, and visible processing status. Operating procedures should identify who investigates failures and how they escalate urgent issues.
How to evaluate security, implementation, and vendor accountability
Payroll systems hold identity data, compensation details, tax information, addresses, bank accounts, and employment records. Security therefore requires more than a broad statement that data is encrypted.
We recommend evaluating encryption in transit and at rest, multifactor authentication, role-based access, audit logging, data residency, subprocessors, breach notification, backups, recovery testing, and independent assurance evidence.
Implementation deserves equal attention. A capable platform can still fail at launch if historical balances, tax settings, integrations, approvals, or worker records are wrong.
A practical implementation process should:
- Confirm countries, entities, worker types, and calendars.
- Clean worker and historical payroll data.
- Map earnings, deductions, benefits, taxes, and accounting codes.
- Configure local rules and opening balances.
- Set up integrations and file formats.
- Design access roles and approval workflows.
- Validate payment details.
- Run parallel payroll testing.
- Investigate worker-level variances.
- Communicate changes to workers and managers.
- Document escalation and launch approval.
- Reconcile the live run through settlement.
Give shortlisted providers representative records, sample calculations, unusual earnings, and exception scenarios. Ask them to demonstrate the full resolution process rather than promising that support will handle it.
Security evidence to request
Ask for current evidence covering:
- Independent audit or certification reports.
- Penetration testing and remediation.
- Encryption and key management.
- Multifactor authentication.
- Privileged-access reviews.
- Security monitoring.
- Data retention and deletion.
- Backup and recovery procedures.
- Business continuity testing.
- Incident notification commitments.
- Subprocessor lists and change notices.
Confirm where data is stored and transferred, as well as which employees, contractors, or local partners can access it. Privileged administrative actions should be logged and reviewed.
Security questionnaires help, but current evidence and contractual commitments are stronger than simple yes-or-no answers.
Implementation checklist before live payroll
Before launch, confirm that the team has:
- Removed duplicate and obsolete records.
- Validated names, addresses, identifiers, and bank details.
- Confirmed worker classifications.
- Mapped earning and deduction codes.
- Loaded historical wages, taxes, benefits, and leave balances.
- Configured calendars, cutoffs, and funding deadlines.
- Tested overtime, bonuses, reimbursements, and statutory payments.
- Configured approval roles.
- Tested accounting entries and integrations.
- Compared worker-level payroll results.
- Approved or resolved identified variances.
- Documented rollback and escalation procedures.
- Explained payslip access and support routes to workers.
Worker-level comparison is essential. Offset errors can leave the total payroll unchanged while individual workers still receive the wrong amount.
Questions every cloud payroll vendor should answer
Every vendor should clearly explain:
- Which countries and worker types it directly supports.
- Where it uses local partners or other third parties.
- Whether customers need local entities or registrations.
- Who maintains those registrations.
- Who calculates payroll and reviews exceptions.
- Who submits filings and moves funds.
- Who handles notices and amended returns.
- Who pays penalties caused by provider error.
- What approval and funding deadlines apply.
- How late data or funding is handled.
- How corrections, reversals, and off-cycle payments work.
- How failed transfers are investigated.
- What evidence is supplied for filings and payments.
- How worker disputes are escalated.
- What implementation work remains with the customer.
- Which fees sit outside the standard run.
We recommend testing the answers against actual countries, worker types, calendars, integrations, and recent exceptions. Generic demonstrations tend to hide the operating details that determine whether a platform reduces work or adds another coordination layer.
Evaluate your payroll operation with real workforce data
Map your countries, worker types, entities, payroll calendars, currencies, integrations, exceptions, and manual workload. Then evaluate Shorpay against that operating reality—not a generic feature checklist.
FAQ
What software should we use for payroll?
Use software that matches the business’s worker types, countries, entities, pay complexity, and internal expertise. Domestic software may suit a registered local entity, while distributed teams may need global payroll, EOR, and contractor capabilities. Confirm ownership of registrations, filings, payments, corrections, and penalties before choosing.
What is Sage Cloud Payroll?
Sage Cloud Payroll is a branded payroll product delivered through cloud technology. Buyers should still assess whether the relevant offering supports their countries, entities, employee types, filings, accounting integrations, approval workflows, and service requirements.
What are the four types of payroll?
In our framework, the four practical operating models are in-house processing, an outsourced payroll bureau, local payroll software, and a global payroll platform. Businesses can combine them across countries. The best fit depends on compliance ownership, entities, internal capacity, integrations, implementation effort, and cost.
Who is ADP’s biggest competitor?
There is no single alternative that suits every business. We recommend comparing supported jurisdictions, required entities, contractual responsibilities, exception handling, implementation support, integrations, foreign exchange charges, and accountability rather than relying on vendor size.
Does cloud-based payroll software guarantee international compliance?
No. Cloud delivery describes how the system is accessed. International compliance may still require local entities, registrations, classification reviews, withholding, social contributions, filings, and permanent establishment advice. Confirm in writing which obligations belong to the platform, local partners, and customer.
How much does international cloud payroll cost?
Total cost may include subscriptions, per-worker charges, implementation, integrations, country minimums, foreign exchange margins, transfers, filings, corrections, year-end work, support, and internal labor. Keep provider fees separate from employer taxes and statutory benefits when comparing proposals.