TL;DR
Direct deposit is an electronic payment sent to a recipient’s account. It is convenient, but it is not necessarily instant or available at a guaranteed hour. On-time payroll depends on approval, funding, provider cutoffs, settlement, holidays, and the receiving institution’s posting process. We recommend planning backward from payday, collecting bank details securely, and managing international payments and worker classification as separate issues.
Table of Contents
- What is direct deposit, and how does it work?
- Who is eligible for direct deposit?
- What information and authorization does an employer need?
- Direct deposit timing: Cutoffs, settlement, weekends, and holidays
- What time does direct deposit arrive, and how can its status be checked?
- Prenotes, account validation, and first-payroll controls
- Failed direct deposits, returns, and reversals
- International direct deposit is more than a bank transfer
- Common direct deposit questions
- FAQ
- Build a payroll process that supports on-time payment
What is direct deposit, and how does it work?
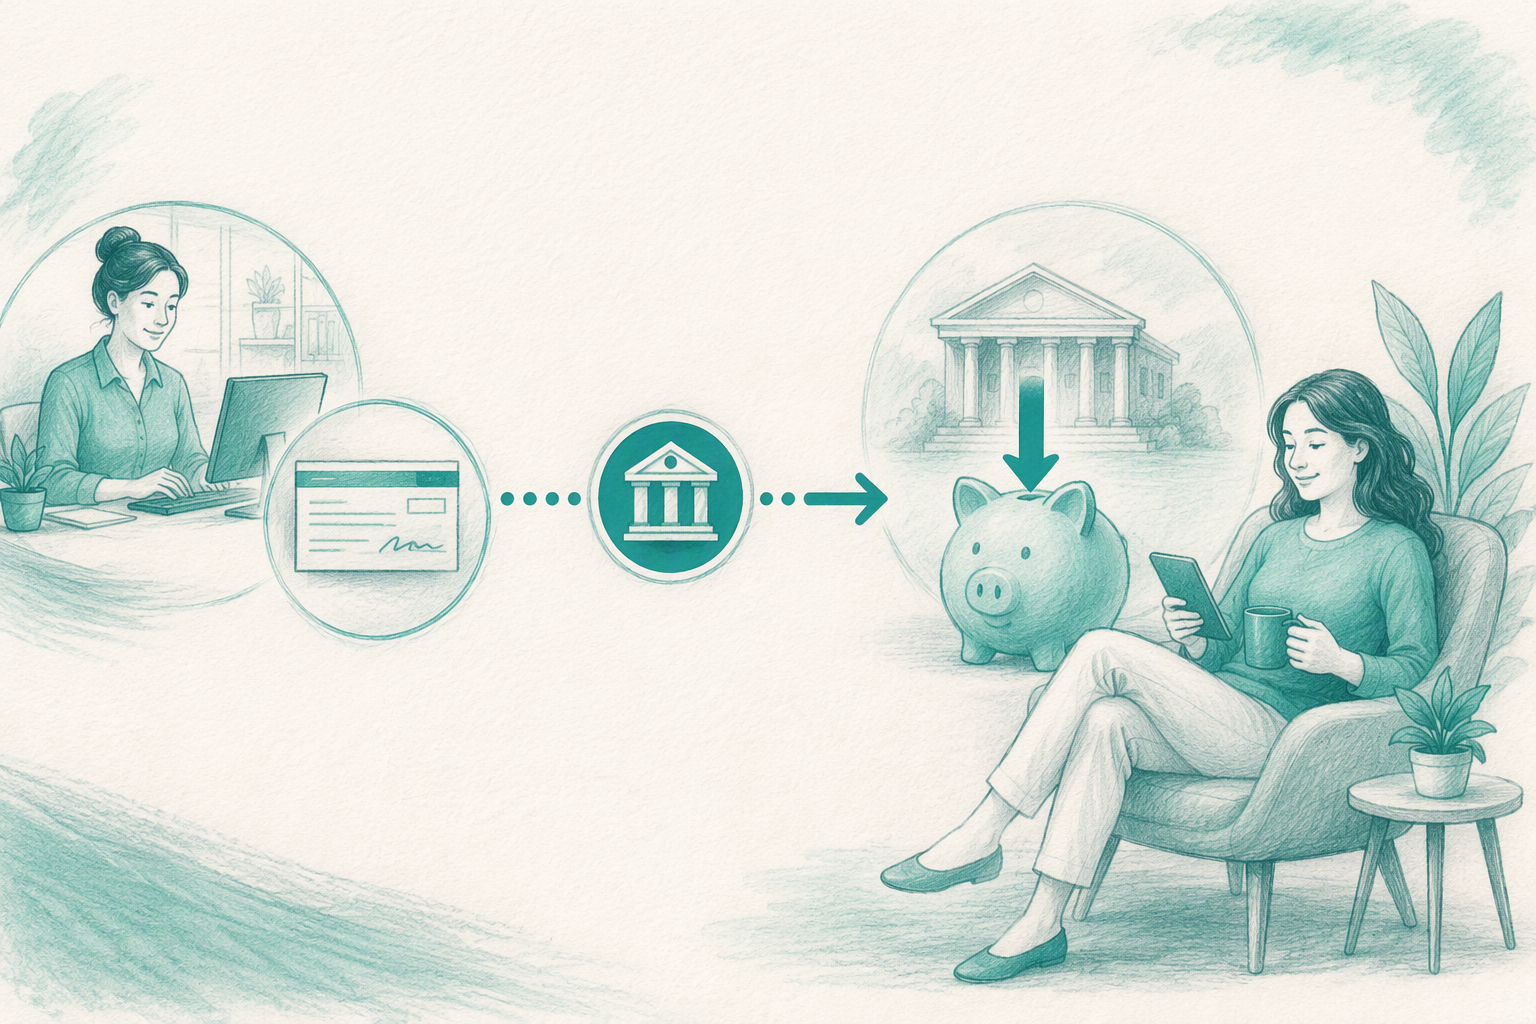
Direct deposit means a payer sends money electronically to a payee’s account. Businesses commonly use it to pay wages, salaries, contractors, and suppliers. It can also be used for bills, taxes, benefits, and other payments.
The term describes the payment method. It does not guarantee instant settlement or availability at a particular hour.
Several parties may be involved:
- Employer: Approves payroll and provides funding.
- Payroll provider: Calculates pay and prepares payment instructions.
- Financial institutions: Send, receive, and post the payment.
- Payment network: Routes the electronic transfer.
- Recipient: Supplies valid account details and authorization.
A payroll dashboard marked “processed” may confirm only that one stage is complete. It does not always mean the receiving institution has made the funds available.
The payroll payment flow
A typical electronic payroll deposit follows these steps:
- The employer approves wages, deductions, account details, and payday.
- The payroll provider prepares payment instructions.
- The instructions are submitted through the relevant payment network.
- The participating financial institutions settle the payment.
- The receiving institution credits the recipient’s account.
Submission, settlement, and account availability are separate events. We recommend confirming what each status label means in the provider’s system.
Direct deposit versus other payment rails
Employers may have several payment options:
- Standard electronic bank payments: Usually require advance submission.
- Faster electronic payments: May have eligibility rules, cutoffs, or additional costs.
- Wire transfers: Follow different timing, cost, and recovery rules.
- Real-time payment services: Depend on participating institutions and provider support.
The fastest rail is not automatically the best fit for payroll. Coverage, cost, deadlines, and correction procedures all matter.
Who is eligible for direct deposit?
Employees, contractors, suppliers, benefit recipients, and other payees may receive direct deposit when the payer’s program and the destination account support electronic credits.
Possible destinations include checking accounts, supported savings accounts, payroll cards, prepaid accounts, and some app-based accounts.
Whether an employer may require direct deposit depends on applicable wage-payment law. Some jurisdictions may require consent or an alternative payment method.
Options without a traditional bank account
A payroll card or eligible prepaid account may be an option for someone without a conventional bank account. Before offering one, we recommend reviewing fees, access to funds, consent requirements, replacement procedures, and local wage rules.
A payment method can be technically valid but still cause problems if accessing wages is difficult or expensive.
Employees versus contractors
Both employees and contractors can receive electronic payments. The payment rail does not determine worker classification.
Classification depends on the working relationship and applicable legal tests. Our guide to paying international contractors covers payment considerations without treating the payment method as a classification decision.
What information and authorization does an employer need?
Direct deposit setup commonly requires:
- The account holder’s name
- The financial institution’s name
- A routing number or local bank code
- The account number and type
- Allocation instructions for split deposits, if supported
- The payee’s authorization
A provider may also request a voided check or use an electronic validation process.
Authorization to send payroll credits does not necessarily authorize the employer to debit the account, recover an overpayment, or make a wage deduction. Separate consent or legal review may be required.
Is a paper direct-deposit form required?
Not in every case. Requirements depend on applicable law, employer procedures, and the provider’s rules.
Where electronic authorization is accepted, employers should retain a clear record of consent, the selected account, and later changes. A dated audit trail is more useful than an untracked attachment.
Stop collecting bank details through email
Email, shared drives, and payroll spreadsheets can expose sensitive account data and obscure who changed it.
We recommend secure self-service enrollment, encryption, role-based access, account-change notifications, and a retained change history. Shor’s international payroll system can centralize employee records and payment workflows without requiring founders to move bank details between inboxes.
Direct deposit timing: Cutoffs, settlement, weekends, and holidays
Direct deposit is not necessarily instant. Payroll teams should work backward from the promised payday and account for deadlines covering:
- Payroll approval
- Employer funding
- Provider processing
- Payment submission
- Bank settlement and posting
Weekends, banking holidays, time zones, compliance reviews, and funding issues can affect timing. Accepting a payroll submission does not always mean a provider can meet the intended payday.
A practical backward payroll calendar
For a Friday payday, the employer may need to approve and fund payroll several business days earlier. The exact schedule depends on the provider, payment rail, receiving bank, jurisdiction, and holiday calendar.
International teams must also consider local closures. Our guide to UK public holidays and payroll deadlines explains why a regular workday in one country may be a banking holiday elsewhere.
Why early access is usually a bank feature
Some institutions make incoming payroll funds available before the stated payday. That usually reflects the receiving institution’s policy rather than a faster payment chosen by the employer.
We recommend promising only the official payday. The receiving institution controls when an early deposit becomes visible or available.
What time does direct deposit arrive, and how can its status be checked?
There is no universal posting hour. A receiving institution may post deposits overnight, in batches, or after internal processing.
How employees can check a deposit
Employees can review the pay statement and official payday, check the receiving account, confirm that payroll has current account details, and contact the payroll team if the payment is missing.
Not every institution displays pending electronic credits. The absence of a pending transaction does not prove that the payment was never submitted.
How employers should trace a missing deposit
Payroll administrators should check the approval time, funding status, intended payment date, destination details, provider status, and any rejection or return notice.
The aim is to determine whether the payment is pending, completed, rejected, returned, or never submitted. Provider terminology varies, so Patriot Payroll’s direct-deposit and international limits should be assessed separately from another provider’s processes.
Prenotes, account validation, and first-payroll controls
Some providers use a prenote or another validation method before sending a live payment. Validation may identify certain account errors, but it can add setup time.
Other methods may include account verification, small test deposits, provider validation tools, or manual review. None removes every risk.
What validation can and cannot confirm
Validation may detect invalid routing information, unsupported account types, or incompatible details. Depending on the method, it may not confirm account ownership or identify a recently closed, frozen, or fraudulently substituted account.
Employers therefore need a fallback payment process when validation cannot be completed before payday.
Controls for bank-detail changes
Bank details should be changed through an authenticated workflow rather than email. Useful controls include employee notifications, extra review for last-minute changes, restricted administrator access, and a retained change history.
Urgency should not override identity checks, especially when a new account is submitted close to payroll cutoff.
Failed direct deposits, returns, and reversals
A missing payment may have been:
- Never submitted
- Rejected before completion
- Returned by the receiving institution
- Posted but later disputed
Possible causes include incorrect account details, closed or frozen accounts, funding problems, compliance reviews, and missed deadlines.
Our recommended response is to identify the status, protect payday, correct information securely, select an approved replacement method, reconcile the original transaction, and document communications.
What happens after incorrect details are submitted?
Invalid details may cause a payment to be returned. If the account number is valid but belongs to someone else, recovery may be more difficult.
Employers should investigate before automatically issuing a duplicate. A controlled exception process can support the worker without creating an avoidable double payment.
When can an employer reverse a deposit?
A reversal is not a general “undo” function. Its availability depends on the payment rail, the type of error, applicable deadlines, and provider procedures.
A reversal is also different from a payroll deduction, repayment agreement, or legal recovery claim. We recommend involving the payroll provider and seeking legal advice where appropriate.
International direct deposit is more than a bank transfer
Outside the United States, payroll may use local clearing systems rather than the same network used for domestic U.S. payments.
International payroll can involve:
- Local bank codes and account formats
- Payment and funding currencies
- Foreign exchange
- Local clearing deadlines and holidays
- Tax withholding and statutory deductions
- Payslip and reporting requirements
A single transfer estimate is rarely enough for a dependable multinational payroll calendar.
Local rails, currencies, and deadlines
Employers must confirm both their payroll approval deadline and the destination country’s banking cutoff. Hiring documentation, payroll registration, account setup, and compliance checks may also need to be completed before the first payment.
Our guide to international employee onboarding timelines explains why this preparation should start well before payday.
Payment method does not solve classification
Transfer frequency, account type, and payment labels do not determine employment status. Classification can affect withholding, benefits, employment protections, and reporting.
Payroll software is not a substitute for legal or tax advice. We recommend reviewing classification before configuring a worker as an employee or contractor.
Common direct deposit questions
Can government payments arrive by direct deposit?
Yes. Government agencies may use direct deposit for benefits, refunds, and other payments. Enrollment, timing, and eligible accounts vary by program, so recipients should follow the relevant agency’s official guidance.
Can direct deposit go to an app, card, or online account?
Possibly. The account must provide valid deposit instructions and support the relevant payment type. Employees should confirm ownership requirements, limits, and payroll compatibility with the receiving institution.
Is there a universal direct-deposit login?
No. Employees should use their employer’s payroll portal or contact the payroll team. Once payroll confirms submission, account-posting questions may need to go to the receiving institution.
Build a payroll process that supports on-time payment
Direct deposit works best when approval, funding, secure account management, and payment deadlines are coordinated. Talk to Shor about international payroll to build a dependable payment workflow for a distributed team.
FAQ
Who is eligible for direct deposit?
Employees, contractors, suppliers, benefit recipients, and other payees may qualify when the payer’s program and receiving account support electronic payments. Legal requirements for consent or alternative payment methods vary.
What time will direct deposit arrive?
There is no universal time. The receiving institution controls when a deposit appears and when the funds become available. Employers should commit to the official payday rather than a specific posting hour.
How do employees know whether a deposit is coming?
They can check their pay statement, official payday, and account activity, then confirm their account details with payroll. Payroll can verify whether the payment was approved, funded, and submitted.
What should an employer do when a deposit fails?
First identify whether the payment was rejected, returned, delayed, or never submitted. Then correct the issue securely, arrange an approved replacement if necessary, and reconcile the original payment.