TL;DR
The eor vs own entity decision cannot be reduced to headcount. An Employer of Record (EOR) often suits businesses that value speed, flexibility, and a simpler market exit. An owned entity deserves closer analysis when operations are durable and direct control creates measurable commercial value. We recommend comparing both routes across several operating periods, including setup, migration, and shutdown costs—not just monthly fees.
Table of contents
- TL;DR
- Table of contents
- EOR vs own entity: the decision in brief
- EOR vs own entity: comparing costs and salaries
- The break-even formula for EOR vs entity
- How long each route takes to launch
- When an EOR is the more practical route
- When to open an entity abroad
- Compliance risks neither option automatically solves
- Switching from an EOR to your own entity
- Decision scenarios for volatile international teams
- EOR vs own entity buyer checklist
- FAQ
- Model your international hiring costs
EOR vs own entity: the decision in brief
An EOR is the local legal employer. It administers employment contracts, payroll, withholding, employer contributions, and required benefits while the client company directs day-to-day work.
Our guide to what an Employer of Record is explains the model in more detail. An EOR is not the same as payroll software or a payroll processor. Payroll services help pay people a business already employs; an EOR becomes the legal employer where the client lacks its own entity.
An owned entity is a locally incorporated company controlled by the expanding business. It hires workers directly and assumes responsibility for employment law, payroll, tax registrations, corporate filings, governance, benefits, and terminations.
Our practical guidance is:
- Use an EOR when hiring speed and reversibility matter most.
- Investigate an entity when demand is durable and local control, contracting, licensing, or long-term savings create measurable value.
- Do not assume either route is always cheaper.
- Do not treat an EOR as protection from every compliance risk.
Quick comparison
| Factor | EOR | Owned entity |
|---|---|---|
| Hiring speed | Usually faster once checks and contracting are complete | Depends on incorporation, banking, registrations, payroll, and licensing |
| Upfront investment | Generally lower | Includes legal, registration, banking, advisory, and setup costs |
| Recurring structure | Often charged per employee or as a percentage of payroll | Fixed compliance overhead plus variable payroll costs |
| Employment contracts | Held by the EOR | Held directly by the entity |
| Operational control | Client manages work within the EOR’s processes | Greater direct control within local law |
| Internal workload | Less local employment administration | Requires finance, HR, tax, governance, and payroll oversight |
| Exit complexity | Employee exits and provider termination | Employee exits plus liquidation, filings, tax clearance, and account closure |
EOR vs own entity: comparing costs and salaries
The common claim that an EOR is faster while an entity is cheaper leaves out too much. A useful model includes taxes, compliance work, foreign exchange, severance exposure, employee migration, and the cost of closing an unsuccessful operation.
Start by separating costs that apply under both routes from those created by the chosen structure. Otherwise, an entity quote may look cheap because it excludes employer taxes, while an EOR illustration looks expensive because it includes them.
A worker’s negotiated gross salary does not inherently change based on the structure. Net pay and total employer cost can still vary because of benefits, currency conversion, local payroll rules, tax treatment, and salary-linked provider fees.
Costs that generally apply under either route
These are employment costs rather than automatic EOR premiums:
- Gross salary, overtime, bonuses, commissions, and allowances
- Employer taxes and social contributions
- Payroll withholding and statutory benefits
- Paid leave and legally required severance
- Optional health, pension, insurance, or equity administration where permitted
Country-specific calculations are essential. Our international Employer Cost Calculator can help organize an initial estimate, but local legal and tax advice should confirm the final model.
EOR-specific costs to verify
EOR pricing may use a flat fee per employee, a percentage of payroll, or a hybrid model with minimum charges. Percentage pricing can be costly for highly paid specialists, even when the underlying administrative work remains similar.
Ask for an itemized proposal covering:
- Monthly fees and minimum charges
- Refundable or nonrefundable deposits
- Foreign-exchange methodology and spread
- Benefit administration and markups
- Onboarding and off-cycle payroll
- Bonus and expense processing
- Immigration support
- Termination handling and exit charges
- Severance funding
Confirm whether employer taxes and statutory severance are included, estimated, or passed through separately. A headline fee is not the total cost of employment.
Owned-entity costs to include
An entity model should include incorporation, legal advice, registration, banking, tax IDs, labor registrations, a registered office, and any required licenses.
Recurring costs can include:
- Accounting, payroll, and corporate tax compliance
- Annual filings and audits
- Local director or company-secretary services
- Insurance and registered-office fees
- Internal finance, HR, legal, and management time
- Payroll software, banking, and payment charges
Include the exit budget as well: liquidation, final accounts, tax clearance, employee terminations, provider cancellation, and account closure. Low monthly overhead does not guarantee a lower lifetime cost.
The break-even formula for EOR vs entity
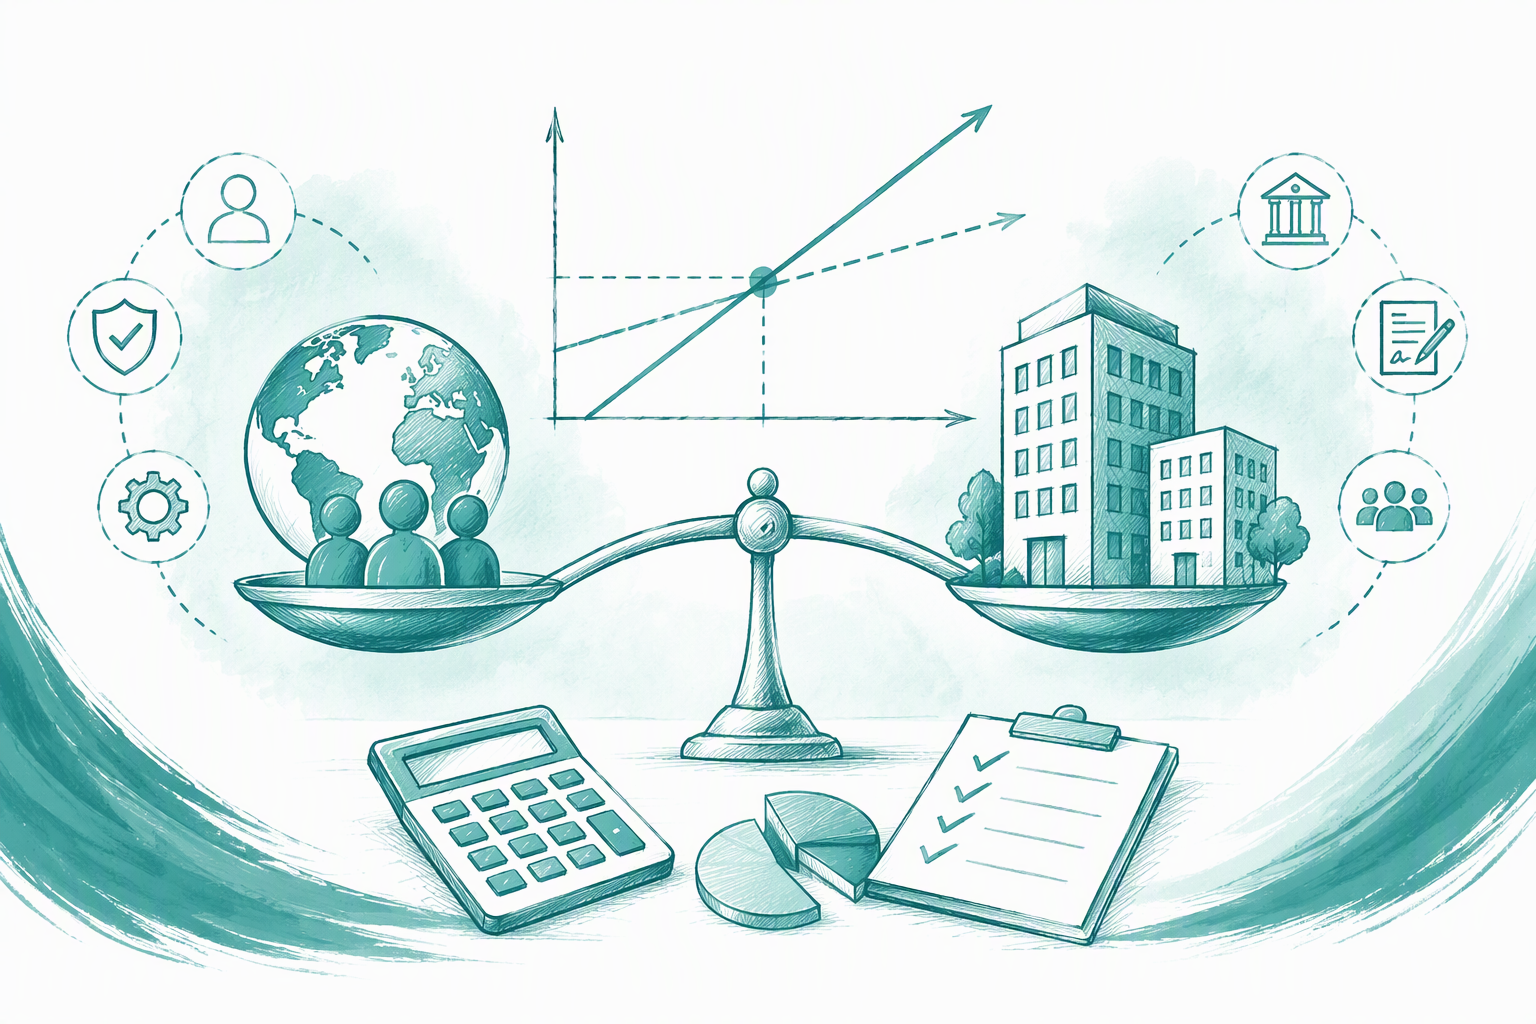
A sound comparison measures the total cost of each route rather than placing an EOR fee beside an accountant’s monthly quote.
EOR route cost:
Employment costs + EOR fees + transaction charges + FX costs + benefit administration + expected termination or migration costs
Entity route cost:
Employment costs + setup costs + fixed compliance costs + payroll administration + internal labor + expected wind-down costs
Because many employment costs appear on both sides, a simplified crossover formula is:
Break-even headcount = annual entity fixed costs ÷ (annual EOR fee per employee − annual entity variable administration cost per employee)
This is a planning tool, not a universal threshold. The result changes with hiring dates, provider pricing, compensation, attrition, currency movements, delayed setup, and the likelihood of leaving the market.
Model several operating periods
One-time entity costs become less significant when operations continue for longer, but only if the market remains viable. We recommend comparing short-, medium-, and long-term scenarios rather than assuming every overseas team becomes permanent.
Use monthly hiring ramps. A team recruited gradually does not create the same EOR costs or potential entity savings as an entire team employed from the first month.
Expected shutdown and migration costs also belong in the model. Contract replacement, employee consultation, payroll cutover, benefit continuity, liquidation, and provider termination are not free.
Test the assumptions behind the crossover
We recommend testing:
- Low, expected, and high headcount
- Different operating periods
- Salary changes under percentage-based pricing
- Expected and elevated attrition
- Exchange-rate movement
- Delayed banking or registration
- Higher compliance and accounting fees
- Early loss of a major customer or contract
A fixed rule such as “open an entity after a certain number of hires” ignores the volatility that often determines the better route.
How long each route takes to launch
An EOR can often support hiring sooner because the legal employer and payroll infrastructure already exist. Onboarding still requires identity checks, employment terms, payroll data, funding, and right-to-work review.
Our guide to international employee onboarding timelines explains the usual process. Immigration, background checks, unusual benefits, or incomplete documents can extend the timeline.
An entity requires several stages. Incorporation alone does not necessarily allow the company to employ or pay workers; banking, tax, labor, and payroll registrations may still be outstanding.
Typical owned-entity setup sequence
The usual sequence is:
- Confirm the entity type, ownership, directors, address, and regulated activities.
- Incorporate and obtain tax identification numbers.
- Open and fund a local bank account.
- Register with labor and social-security authorities.
- Configure payroll and required benefits.
- Obtain relevant licenses or immigration sponsorship registrations.
Requirements vary by country, and some steps cannot run in parallel. We include delayed start dates, lost contract revenue, and management time in the comparison.
What can delay the first payroll
Common blockers include:
- Beneficial-owner and know-your-customer checks
- Bank approval and account funding
- Tax, social-security, or labor registration
- Collective-agreement analysis
- Payroll data collection
- Employment contract review
- Licensing or immigration requirements
The first compliant payroll—not the incorporation certificate—is the meaningful operational milestone.
When an EOR is the more practical route
An EOR is often more practical when employees must start before a local entity and payroll operation can be established. It can also support market testing, uncertain customer contracts, and small teams spread across several countries.
That flexibility can suit startups, staffing firms, data-labeling businesses, and property operators. Their workforces may change around projects, funding, client assignments, or new locations.
An EOR reduces local employment administration, but it does not transfer every tax, licensing, data, or management risk. The client still needs a compliant operating model.
Signals to stay with an EOR longer
Remaining with an EOR may make sense when:
- Demand depends on one customer, project, funding event, or opening.
- Headcount may contract during the planning period.
- The company lacks local finance, HR, payroll, or legal capacity.
- Workers are spread across several low-headcount markets.
- Entity savings disappear after migration and wind-down costs.
- Faster hiring protects revenue or a launch deadline.
High headcount does not prove permanence. A large temporary project may justify less infrastructure than a small but predictable long-term operation.
When to open an entity abroad
There is no universal employee count that determines when to open an entity. The decision should follow evidence of operational certainty and a country-specific commercial, legal, and financial case.
Stable hiring, predictable demand, and sustained savings are useful signals. Other factors may be more decisive:
- Local customer contracting or revenue collection
- Regulated activities and licensing
- Immigration sponsorship
- Tax structuring requirements
- Investor or banking requirements
- Direct control over benefits and employment terms
- A permanent local management function
Direct ownership should solve an identifiable operational problem or create defensible long-term value.
Entity-readiness checklist
Before proceeding, confirm that:
- Demand remains credible under a downside forecast.
- Setup, compliance, administration, and closure are funded.
- A named owner will oversee payroll, tax, employment, accounting, and governance.
- Local advisers have reviewed the operating model.
- Banking and payroll sequencing support the intended start date.
- Employee migration from an existing EOR has been priced.
Why more control also means more liability
An entity owns the employment contracts and can design benefits, policies, and processes within local law. That control can support consistent local operations.
It also creates direct responsibility for payroll errors, tax filings, leave, benefits, consultations, terminations, and audits. Control is valuable only when the business has the systems and expertise to manage it safely.
Compliance risks neither option automatically solves
Permanent-establishment exposure depends on the facts. Local sales activity, contract authority, management functions, fixed places of business, and jurisdiction-specific rules may all matter.
An EOR does not automatically eliminate that risk. An owned entity does not necessarily resolve the parent company’s exposure either.
Both routes require review of:
- Immigration and work authorization
- Sector licensing
- Data protection and cross-border transfers
- Workplace health and safety
- Worker classification
- Co-employment or joint-employer exposure
- Day-to-day management practices
- Local insurance requirements
Country-specific advisers should review the actual roles, authority, customers, workplaces, and revenue activity.
Contracts, IP, confidentiality, and worker direction
The EOR is the legal employer, but the client generally directs practical work and performance. The service agreement and employment contract should allocate responsibilities clearly without contradicting local law.
Confirm how intellectual-property rights and confidentiality obligations pass from the employee through the EOR to the client. A global template may not create an effective local assignment.
Working time, monitoring, discipline, and termination also require local procedures. Managers should know when the legal employer must review an instruction before action is taken.
Risk questions to ask
Ask:
- Will employees negotiate, sell, sign contracts, or manage revenue?
- Does the work require licensing, insurance, or registration?
- Is immigration sponsorship needed?
- Where will employees work, and who controls that workplace?
- Who responds when an instruction conflicts with local law?
- Does the structure protect IP and confidential information?
Switching from an EOR to your own entity
An EOR-to-entity move is a separate project, not an administrative toggle. Depending on local law, it may require termination and rehire, employee consent, consultation, or a protected business-transfer process.
Include these costs in the original break-even model. If the immediate step is changing providers, our guide to switching EOR providers without breaking payroll covers related continuity and cutover risks.
Employee continuity checklist
Account for:
- Recognized tenure and probation status
- Accrued leave and unpaid expenses
- Bonuses and commissions
- Notice and severance rights
- Employee communication, consent, or consultation
- Final EOR payroll
- Health, pension, and statutory benefit continuity
- Equity and immigration arrangements
Employees should understand what changes, what remains protected, and which company becomes responsible on the cutover date.
Payroll cutover checklist
Before transferring employees:
- Activate bank accounts and payroll registrations.
- Confirm the payroll calendar and funding process.
- Reconcile year-to-date earnings and withholding.
- Transfer leave, benefit, and expense records securely.
- Run parallel calculations where practical.
- Plan off-cycle corrections.
- Coordinate final and first payroll dates.
A missed registration or funding deadline can lead to late wages, incorrect withholding, or a benefits gap.
Decision scenarios for volatile international teams
The right structure may differ by country within the same business. Workforce certainty, local activity, and exit cost often matter more than peak headcount.
Startup testing Spain with a small team
An EOR may help a startup hire promptly without waiting for incorporation, banking, registrations, and payroll activation. Recurring provider fees buy flexibility if the market test ends.
Sustained growth may later shift the calculation toward an entity. The model must still include migration, ongoing compliance, and eventual closure.
Staffing or data-labeling team tied to one contract
A staffing or data-labeling company should model staggered starts, attrition, off-cycle payroll, and contract-renewal risk. It should also compare percentage-based and flat EOR pricing.
Peak headcount does not automatically justify an entity if the customer can end the project. Permanent infrastructure built around temporary revenue may create the greater risk.
Property operations across several locations
A property operator may use an EOR for managers and maintenance coordinators across several countries. One stable market may eventually justify an entity because of local contracts, licensing, or durable operations.
Other markets may remain better suited to an EOR. We recommend comparing payroll calendars, allowances, on-call work, overtime, collective rules, and employment requirements country by country.
EOR vs own entity buyer checklist
A sound buying process focuses on country coverage, transparent pricing, service scope, liability allocation, and exit terms. Provider size or a polished dashboard cannot replace those details.
Should an American company use an EOR or open an entity in Spain?
An EOR may suit a company that needs faster hiring or wants to test Spain without permanent infrastructure. An entity deserves analysis when local operations, contracting, licensing, or long-term savings are durable.
Spanish employment, tax, permanent-establishment, collective-agreement, and termination requirements should be assessed for the actual roles. The parent company’s nationality does not decide the structure.
How should EOR costs be assessed?
Pricing may be flat per employee or based on payroll. It varies by country, compensation, benefits, and service scope, so a universal price is misleading.
Request separate figures for employer taxes, statutory benefits, deposits, FX spreads, benefit markups, off-cycle payroll, immigration, severance funding, and termination support.
Does provider size determine fit?
Large EOR providers may offer broad coverage and operational resources, but size does not prove transparent pricing, direct infrastructure, local expertise, or responsive support.
Review the legal-employer structure, payroll controls, data handling, liability allocation, support, pricing, and exit provisions. A detailed comparison such as Shor vs. Oyster illustrates the questions buyers should ask without making brand scale the deciding factor.
What should be verified before signing?
Request a country-specific employment cost illustration and sample invoice. Confirm:
- Contract ownership and IP terms
- Payroll funding deadlines
- Exchange-rate methodology
- Benefits and deposits
- Termination and migration procedures
- Liability limits
- Data handling and support escalation
- Included and pass-through charges
Compare the proposal with a fully loaded entity model across more than one operating scenario.
Model your international hiring costs
Use Shor to build country-specific EOR and entity scenarios, compare international payroll costs, and account for setup, migration, and shutdown expenses. Start modelling your international hiring plan with us today.
FAQ
What is an EOR for employment?
An EOR is a local legal employer that hires workers on another company’s behalf. It handles employment contracts, payroll, withholding, statutory contributions, and required benefits while the client directs everyday work.
Is an EOR always cheaper than opening an entity?
No. An EOR generally requires less setup but charges recurring fees that may rise with headcount or payroll. An entity carries fixed setup and compliance costs but may become economical during durable operations.
Can an EOR prevent permanent-establishment risk?
No. Permanent-establishment exposure depends on the company’s actual activities, including sales, contract authority, management, revenue operations, and workplace arrangements. Country-specific tax advice is essential.
When should a company switch from an EOR to an entity?
We recommend considering a switch when local demand is durable and direct control or commercial requirements create measurable value. The calculation should include employee transfer, payroll cutover, benefits, internal administration, and future wind-down costs.
What should an EOR quote include?
A useful quote separates salary, employer taxes, statutory benefits, EOR fees, deposits, exchange-rate costs, benefit markups, and payroll extras. It should also explain severance funding, termination support, liability, funding deadlines, and exit terms.