TL;DR
Foreign businesses can open an entity in Brazil, but incorporation may be premature for the first few hires. When considering how to open entity Brazil operations, we recommend comparing an owned LTDA with an employer of record, genuine contractor arrangements, and payroll-only support. Base the decision on hiring speed, expected headcount, local commercial activity, operational control, and total compliance cost—not formation fees alone.
Table of contents
- TL;DR
- Table of contents
- Should you open an entity in Brazil—or hire without one?
- LTDA, subsidiary, or branch: What are you actually opening?
- How to open a Brazilian entity: Registration order and timeline
- What does a Brazilian entity really cost?
- Brazil payroll cost: Budget beyond gross salary
- EOR vs payroll-only vs contractors in Brazil
- When does an EOR stop making financial sense?
- FAQ
- Hire in Brazil without rushing into an entity
Should you open an entity in Brazil—or hire without one?
Foreign businesses can establish an entity in Brazil. But when the immediate goal is hiring a small initial team, incorporation can turn a market test into an ongoing accounting, tax, payroll, banking, labor, and governance commitment.
We recommend assessing the decision against practical operating needs:
- How quickly workers need to start
- Expected headcount and hiring pace
- Whether the operation is temporary or permanent
- Whether the business needs local invoicing or customer contracts
- How much direct employment control it requires
- Whether its activities require licenses or local registrations
- Whether management can maintain the entity during quiet periods
- Which collective bargaining rules may apply
There are four common paths: form an owned entity, use an employer of record, engage genuinely independent contractors, or use payroll-only support when a valid local employer already exists.
These models are not interchangeable. Payroll software can calculate and organize payments, but it cannot provide the legal employing structure that a foreign company lacks.
Formation schedules and costs vary by state, municipality, business activity, ownership documents, licensing requirements, bank checks, and the relevant collective bargaining agreement. We are cautious about any provider promising a universal incorporation date or price.
When an owned Brazilian entity makes sense
An owned entity becomes more attractive when a company expects sustained hiring, needs to invoice Brazilian customers, enters recurring local contracts, performs regulated work, or establishes permanent local management.
The main benefit is control. A company can employ workers directly, build local commercial relationships, manage its benefit policies, and potentially improve its per-worker economics as the team grows.
That control brings ongoing obligations. The entity needs governance, bookkeeping, tax filings, payroll processes, legal representation, banking, employment compliance, and a plan for eventual closure.
A property-management business, for example, may need local coordinators to visit sites, work with vendors, and follow operating schedules. Those activities raise questions about licenses, taxation, employment, and authority to enter contracts—not just payroll processing.
When entity-free hiring is the practical first step
An employer of record, or EOR, provides a local employing structure while a company tests demand, builds an initial team, or completes incorporation and payroll setup.
The EOR employs workers locally and manages employment administration within the agreed service scope. The client directs the permitted day-to-day work and remains responsible for sound workforce management, performance, data access, and workplace conduct.
We see an EOR as a market-entry and workforce tool rather than an automatic permanent model. Once headcount becomes predictable, local revenue grows, and the operation looks permanent, an owned entity may offer stronger control and better long-term economics.
For a fuller explanation of the legal-employer model, read our guide to what an employer of record does.
LTDA, subsidiary, or branch: What are you actually opening?
“LTDA” and “subsidiary” describe different concepts. An LTDA is a Brazilian limited-liability company form. A subsidiary is a company owned or controlled by a parent.
A foreign parent can therefore own a Brazilian LTDA, subject to applicable ownership, representation, investment-registration, and industry rules. Calling a business a subsidiary does not identify its legal form.
A branch is different. It is a direct extension of the foreign company rather than a legally separate local subsidiary. A foreign branch generally involves federal authorization and additional formalities, so it is rarely the quick shortcut businesses expect.
Brazilian LTDA owned by a foreign parent
A Brazilian LTDA is organized through articles of association. Its documents address ownership, capital, management powers, decision-making, profit allocation, and transfer restrictions.
When a foreign business owns the company, its corporate records must support the proposed ownership and appointment structure. Foreign owners generally need representation that can be exercised locally, while relevant foreign investment may need to be registered through the applicable Brazilian framework.
The company also needs an authorized person to act for it in Brazil. Foreign ownership does not remove local governance, tax, filing, payroll, or representation duties.
Requirements depend on the owners, managers, origin of the supporting documents, and planned activities. We recommend having Brazilian legal and accounting advisers confirm the structure before filing.
Why a branch is usually more complex
A foreign branch generally requires authorization to operate in Brazil. The process may involve substantial parent-company documentation, translated and registered records, local representatives, and continuing formalities connected to the foreign organization.
Because the branch is an extension of the foreign company, its activities may expose the parent more directly than those of a separately incorporated subsidiary. Choosing a branch is therefore a legal and risk decision, not merely an administrative one.
A branch may still be relevant when legislation, a regulated project, a public contract, or the company’s international structure requires it. Those circumstances call for advice from Brazilian counsel.
Representative office and informal presence risks
Calling an operation a “representative office” does not automatically create a recognized employing or contracting structure. An office with local staff, management authority, sales activity, or contract involvement may still raise labor, licensing, tax, and permanent-establishment questions.
A similar problem arises when a foreign company pays Brazilian workers directly and treats payment processing as the compliance solution. The payment method does not establish who legally employs the workers or determine whether the local activity requires registration.
Before opening an office or appointing local representatives, we recommend reviewing what the staff will do, who can bind the business, where revenue-generating activity occurs, and which licenses may apply.
How to open a Brazilian entity: Registration order and timeline
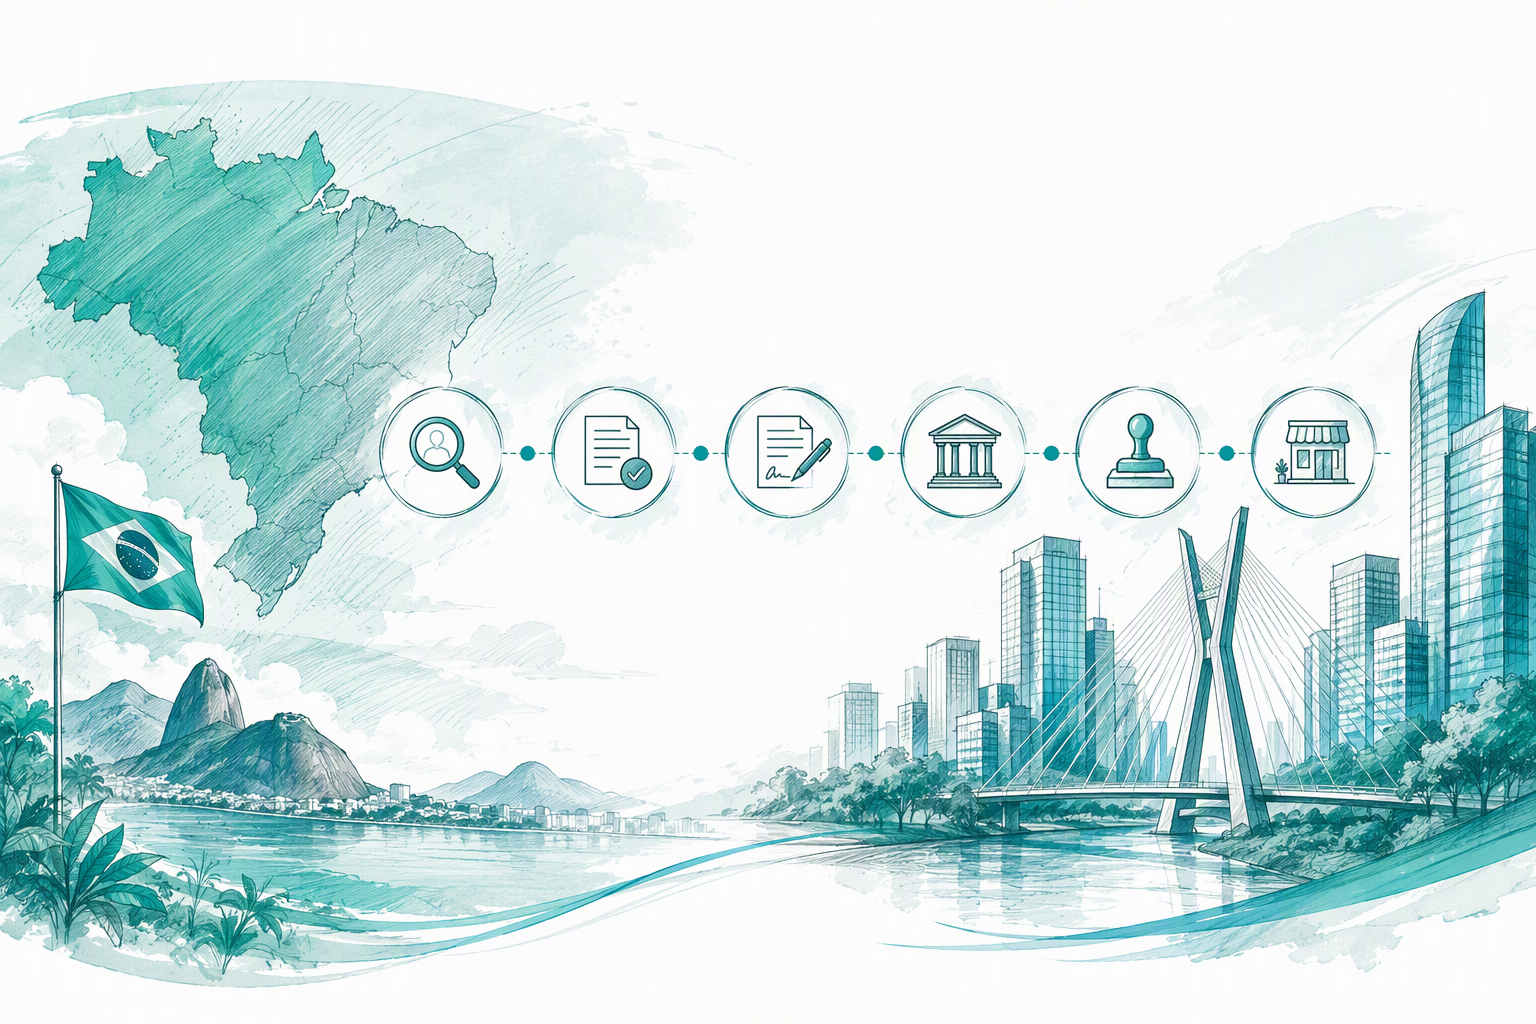
Opening a Brazilian company is a sequence of dependent tasks, not a single filing. The process commonly moves from structural decisions and foreign-document preparation to commercial registration, tax enrollment, local approvals, banking, digital access, and payroll activation.
A fixed timeline is unrealistic. Location, activity, ownership complexity, document corrections, licensing, and bank due diligence can all affect the schedule.
It also helps to separate two milestones:
- Legal incorporation: The company has been formed and has received its core registration.
- Operational readiness: The company can bank, invoice, onboard employees, report payroll, and make required payments.
An LTDA may receive its CNPJ while banking, digital certificates, municipal registration, occupational processes, and payroll configuration remain incomplete. An EOR often provides a shorter route to hiring, although onboarding still depends on complete employee information and documentation.
Step 1—Choose activities, ownership, address, and representation
Start by defining what the company will actually do. Brazil uses CNAE activity codes, which can affect taxation, licensing, payroll treatment, local requirements, and the need for state registration.
The business must also establish its ownership and management model. This includes deciding who will hold quotas, how capital will be contributed, who may sign for the company, and which decisions require owner approval.
Preparation may include:
- A suitable local business address
- A Brazil-resident legal representative where required
- Foreign parent and owner documents
- Powers of attorney
- Records supporting management appointments
- Notarization and apostille or legalization, as applicable
- Sworn Portuguese translations
- Local registration of relevant foreign documents
The list depends on the documents’ country of origin and the parties involved. Incorrectly prepared records can delay later registrations.
Step 2—Complete Junta Comercial and CNPJ registrations
Formation documents are filed with the relevant state commercial registry, or Junta Comercial. The company then obtains its CNPJ through the integrated registration process.
The CNPJ is the entity’s federal tax identification number. Receiving it does not mean the business is fully operational: local registrations, licenses, banking, digital certificates, and employment systems may still be pending.
Foreign owners, administrators, or representatives may also need individual registrations depending on their role and the filing structure. Each person’s requirements should be checked instead of assuming all foreign participants follow the same process.
Names, addresses, powers of attorney, activity descriptions, ownership records, and translated documents should remain consistent across filings. A requested correction can disrupt the wider sequence.
Step 3—Finish local, digital, licensing, and payroll setup
After commercial and federal registration, the company may need municipal registration, service-tax registration, operating permits, state registration, or activity-specific licenses. The correct combination depends on its location and business.
Operational preparation may cover:
- Bank-account approval and access controls
- Digital certificates
- Accounting and tax-reporting configuration
- eSocial processes
- DCTFWeb configuration
- FGTS Digital processes
- Occupational health and safety arrangements
- Employment templates and workplace policies
- Benefit enrollment
- Collective bargaining analysis
- Payroll calendars, calculations, and approvals
This is why we do not treat a CNPJ as proof that payroll can start immediately. Hiring before the reporting and payment infrastructure is ready may create avoidable compliance problems.
What does a Brazilian entity really cost?
The cost to open a company in Brazil is not the same as the cost to own one. Formation quotes may exclude accounting, payroll, address services, representation, banking assistance, licenses, employment support, and eventual liquidation.
We recommend building a total-cost-of-ownership model rather than relying on a single formation figure.
| Cost category | Timing | Inputs to obtain or model |
|---|---|---|
| Foreign-document preparation | Setup | Document volume, apostilles, notarization, translation, registrations |
| Formation and legal work | Setup | Structure, articles, ownership complexity, professional fees |
| Government and registry charges | Setup and event-based | Location, filings, certificates, amendments |
| Address and representation | Setup and recurring | Local address, representative scope, signing support |
| Licensing and operations | Setup and renewal | Activities, location, permits, certificates |
| Accounting and tax compliance | Recurring | Tax regime, transaction volume, reporting complexity |
| Payroll and HR administration | Recurring | Headcount, benefits, collective agreements, reporting |
| Banking and treasury | Setup and recurring | KYC support, payments, controls |
| Internal management time | Recurring | Finance, HR, legal, approvals, vendor management |
| Closure | Exit | Employees, taxes, creditors, deregistration, professional work |
Ask for itemized local quotes. Government charges, professional fees, employment costs, and provider fees should remain separate so the comparison can be reviewed properly.
One-time setup costs
Setup costs may include document legalization, apostilles, sworn translations, registry charges, legal drafting, powers of attorney, representation, address services, digital certificates, banking support, and licensing.
The final amount depends on the location, activities, regulated status, ownership structure, volume of foreign documents, management model, permits, and any corrections required during registration.
A straightforward service business with a simple ownership structure will not necessarily face the same work as a regulated operation with several foreign stakeholders.
Recurring entity and compliance costs
Recurring costs can include bookkeeping, tax filings, payroll administration, representation, corporate maintenance, address services, certificate renewals, occupational compliance, and event-driven filings.
Internal effort also matters. Someone must review payroll, approve payments, maintain employee records, coordinate advisers, answer bank checks, manage benefits, and handle workplace issues.
No employees or revenue does not necessarily mean no cost. A dormant or low-activity company may still have accounting, filing, address, governance, banking, and tax-status obligations.
The overlooked cost of closing the entity
Closure may require employee terminations, final payroll, tax and accounting reconciliation, creditor resolution, registry filings, bank closure, and deregistration.
The work may also reveal unresolved returns, balances, registrations, or employment liabilities that must be addressed. We recommend estimating exit costs before incorporation and including them in the market-entry decision.
Brazil payroll cost: Budget beyond gross salary
Brazilian employment costs should be modeled as separate components. One generic burden percentage can hide differences in industry, tax regime, workplace risk, benefits, and collective bargaining obligations.
A complete budget may include:
- Gross salary
- Applicable employer social-security contributions
- Workplace accident risk contributions
- Applicable third-party contributions
- FGTS
- Thirteenth-salary accrual
- Vacation pay and the constitutional vacation supplement
- Benefits and allowances
- Overtime and working-time costs
- Collective bargaining requirements
- Payroll administration
- Termination reserves
Our international employer cost calculator can help structure the comparison. Final assumptions should still be checked against the role, location, activity, tax regime, and applicable collective agreement.
Monthly employer contributions and payroll deductions
Employer social-security charges, workplace risk contributions, third-party contributions, and FGTS may affect employment cost. Their application and calculation require case-specific review.
Keep employer costs separate from employee deductions. Income tax withheld through payroll, for example, is not an employer benefit cost, even though the employer must calculate, report, and remit it correctly.
Payroll teams must reconcile both employer liabilities and employee withholdings. An amount deducted from salary still carries administrative and reporting duties.
Annual accruals and mandatory paid time
The thirteenth salary and vacation compensation should be accrued during the year rather than treated as unexpected expenses. Vacation budgeting must also account for Brazil’s required constitutional supplement.
Working-time rules can add further cost. Depending on the role, employers may need to manage attendance, overtime, weekly rest, leave, schedules, and evidence supporting an exemption from time controls.
Collective bargaining agreements can also introduce wage floors, benefits, allowances, working-time terms, or adjustment dates. A budget based only on the individual employment agreement may therefore be incomplete.
Termination liabilities and reserves
Termination costs depend on the reason for separation and the employment history. They may include notice, outstanding salary, proportional annual entitlements, accrued vacation compensation, FGTS-related amounts, and other applicable payments.
We recommend modeling several scenarios, including employer-initiated termination, resignation, termination for cause, and the end of a fixed-term arrangement.
Before employment ends, the company or EOR should confirm the procedure, collective agreement, reporting requirements, documentation, and payment deadlines.
EOR vs payroll-only vs contractors in Brazil
The central question is not who sends the payment. It is who signs the employment agreement, carries employer obligations, files payroll reports, and bears worker-classification risk.
| Model | Who signs with the worker? | Who runs payroll? | Who carries employer obligations? |
|---|---|---|---|
| Owned entity | Brazilian entity | Entity or provider | Brazilian entity |
| Employer of record | EOR | EOR | EOR within the service structure |
| Payroll-only | Client’s local employer | Provider or client | Client employer |
| Independent contractor | Contracting party | Not employment payroll | No employer if classification is valid |
Payroll-only support is not an alternative to an entity when no lawful employer exists. Contractors are an entity-free option only when the working relationship is genuinely independent.
Employer of record: A local legal employer
An EOR employs the worker locally while the client directs permitted business activities under a service agreement. Its scope commonly includes onboarding, payroll, benefits administration, employment filings, and offboarding.
The model can support market entry without requiring the client to build corporate and payroll infrastructure first. It does not remove the client’s responsibility to manage performance, conduct, data access, intellectual property, and operational risk.
Commercial terms should explain fees, deposits, benefits, currency handling, expenses, termination costs, and each party’s responsibilities.
Payroll-only provider: Administration without an employing structure
A payroll provider can calculate gross-to-net pay, prepare reports, support filings, and organize payments. Those services are useful once a business has a valid local employer.
They do not make the provider the employer unless the agreement establishes a genuine EOR relationship. Before buying payroll-only support, confirm which entity appears on employment agreements, filings, benefit registrations, and termination documents.
Contractor and PJ hiring risks
Brazilian classification analysis considers the real working relationship, not just the contract label. Personal service, recurring work, compensation, subordination, fixed schedules, exclusivity, close supervision, and integration into the client’s operations may indicate employment.
A PJ agreement does not override working conditions that function like employment. Genuine contractors should retain meaningful independence over how their services are delivered.
We recommend documenting the classification review and ensuring daily practices match the contract. Our guide to paying international contractors explains the payment and documentation controls that support a defensible contractor model.
When does an EOR stop making financial sense?
There is no universal EOR break-even headcount. Provider pricing, salaries, benefits, location, activities, expected duration, internal staffing needs, and employment risks vary too widely.
Nonfinancial triggers matter too. Local customer contracts, procurement requirements, regulated activities, permanent leadership, or local invoicing needs may justify an entity before provider-fee savings do.
A practical break-even model
Compare the entity and EOR over the same period.
Entity cost:
Setup amortization + recurring accounting and compliance + payroll operations + banking + representation + internal HR and legal capacity + management time + expected closure cost
EOR cost:
Provider fees + compensation + statutory employment costs + benefits + onboarding charges + expected termination charges
Handle salary and statutory pass-through costs consistently. Otherwise, one option may look more expensive simply because worker compensation appears on only one side.
We recommend testing low-, base-, and high-growth scenarios rather than assuming the full planned team starts immediately.
Signals that it may be time to form an entity
Formation deserves serious review when the company has:
- Stable or predictable headcount
- A long-term hiring plan
- Recurring Brazilian customer contracts
- Local revenue or invoicing needs
- Permanent local management
- Regulated or licensed activities
- Procurement requirements favoring a local company
- A need for more direct operational control
- Adequate HR, finance, and legal capacity
Legal and tax advisers should review the structure before contracts or employees migrate. Lower provider fees do not automatically make a transfer sensible.
Plan the EOR-to-entity transition before hiring
An EOR-to-entity transition may involve employee consent, termination and rehiring mechanics, service recognition, benefit continuity, payroll cutover, data transfer, and coordinated communication.
The business must also determine how to handle leave balances, expenses, equipment, accrued rights, restrictive covenants, and intellectual-property terms.
We support immediate international hiring while companies collect reliable information about headcount, duration, payroll cost, and local demand. Through Shor’s international payroll platform, teams can avoid treating an uncertain forecast as a reason to build permanent infrastructure immediately.
Hire in Brazil without rushing into an entity
Ready to hire in Brazil but not ready to maintain an LTDA, local banking, payroll registrations, and permanent compliance operations? Talk to us through Shor’s international payroll platform to compare an EOR with an owned Brazilian entity and choose the right route for your team.
FAQ
Can I open a bank account in Brazil from the USA?
Banks may support parts of the process remotely, but a Brazilian corporate account commonly requires a CNPJ, approved representatives, ownership records, and bank-specific KYC. Incorporation does not guarantee approval. The bank may request more documents, local participation, or further verification.
Where can I find the Brazilian CPF database?
Use official Brazilian government or Receita Federal CPF status services rather than unofficial databases. These services provide limited registration-status information, not open access to private tax records. A status check does not replace consent, identity verification, KYC, or professional due diligence.
What is an LTDA in Brazil?
An LTDA is a Brazilian limited-liability company governed by its articles of association and Brazilian law. It is commonly used for foreign-owned subsidiaries. “LTDA” describes the legal form, while “subsidiary” describes the ownership relationship with a parent company.
What is the best business to start in Brazil?
There is no universal answer. The right model depends on demand, competition, licensing, taxation, capital needs, workforce requirements, and the founder’s experience. We recommend testing customer demand and delivery economics before accepting the recurring costs of an entity.
Can a foreign company hire an employee without opening an entity?
An EOR can provide a local employing structure without the foreign company first establishing its own entity. A genuine contractor arrangement may also work when the person operates independently in practice. Payroll-only software cannot supply a missing legal employer, and a contractor agreement cannot cure an employment-like relationship.