TL;DR
Searching for “employer costs Germany” often produces a simple salary uplift. That shortcut can miss payroll levies, accident insurance, administration, paid non-working time and potential offboarding costs. We recommend building an itemized budget that separates recurring payroll, one-time setup expenses and contingent liabilities. Contribution ceilings also matter because some employer charges stop rising once earnings pass the applicable assessment limit.
Table of Contents
- Employer costs Germany: start with the right formula
- What the company actually pays
- How contribution ceilings change the cost curve
- Costs missing from the headline contribution rate
- How to build gross-to-total-cost scenarios
- Why net salary promises create gross-up risk
- Salary cost versus productive labor cost
- Direct German payroll or EOR
- Germany employer cost checks
- FAQ
- Build an itemized Germany hiring budget
Employer costs Germany: start with the right formula
A company may approve a budget by adding a standard percentage to gross salary. Later, payroll levies, accident insurance, administration and provider charges appear. The original budget no longer holds.
We recommend using this formula:
Total employer cost = gross compensation + employer social insurance + payroll levies + accident insurance + provider costs + employment-related operating costs.
Build monthly and annual views with editable fields for salary, work location, health insurer, accident-insurance assumptions, payroll fees and any Employer of Record fee. Our international employer cost calculator offers a useful starting structure.
Separate the result into:
- Recurring payroll costs
- One-time hiring and implementation costs
- Contingent termination and offboarding exposure
Rates, assessment ceilings and insurer-specific charges can change. We always recommend checking current official notices and confirming employee-specific details before approving a budget or signing an offer.
What belongs in total employer cost
Start with gross cash compensation, including fixed salary and taxable bonuses. Then add the expenses economically borne by the employer.
Employee wage tax, church tax where applicable and the employee’s share of social insurance generally come out of gross pay. They affect take-home pay, but they are not extra employer expenses on top of the agreed gross salary.
Accident-insurance premiums and insurer-specific levies should remain editable. They depend on factors such as the employer, insurer, role and risk classification.
Why a flat uplift is unreliable
A standard percentage may provide a rough starting point for core contributions. It does not capture every payroll levy, administrative charge, benefit or EOR fee. It may also ignore the effect of contribution ceilings.
We suggest preparing three scenarios:
- Low: confirmed statutory contributions and fixed fees
- Expected: likely levies, accident premiums and normal payroll work
- High: conservative variable charges, corrections and operational exposure
A range gives finance teams and investors a more useful view than an unsupported single percentage.
What the company actually pays
German payroll typically separates employer expenses from employee deductions. The employer calculates and remits both, but remitting money does not necessarily make it an additional company cost.
Core employer-funded or employer-shared categories can include:
| Contribution or cost | Budget treatment |
|---|---|
| Statutory health insurance | Apply the current employer share up to the relevant ceiling |
| Additional health contribution | Confirm the employee’s insurer and applicable split |
| Pension insurance | Apply the employer share up to its assessment ceiling |
| Unemployment insurance | Apply the employer share up to its assessment ceiling |
| Long-term care insurance | Check the standard split and any regional exception |
| Accident insurance | Estimate separately using the relevant risk classification |
| Payroll levies | Confirm applicability and insurer-specific rates |
Income tax, church tax, any applicable solidarity surcharge and employee social-insurance contributions are payroll withholdings. They should not automatically be added to gross salary as employer expenses.
Health and long-term care insurance
Statutory health insurance includes a general contribution and an additional contribution set by the health insurer. Because the additional amount can vary, our model treats it as an editable field rather than a universal rate.
Long-term care insurance also requires care. Employee circumstances can affect deductions, and the employer-employee split may differ in Saxony. The work location and insurance status therefore belong in the calculation.
Pension and unemployment insurance
Employer pension and unemployment contributions are calculated only up to their applicable assessment ceiling. Their ceiling may differ from the one used for health and long-term care insurance.
As a result, some contributions can keep increasing after others have flattened. A calculator that applies one percentage to the entire salary will not show that distinction.
How contribution ceilings change the cost curve
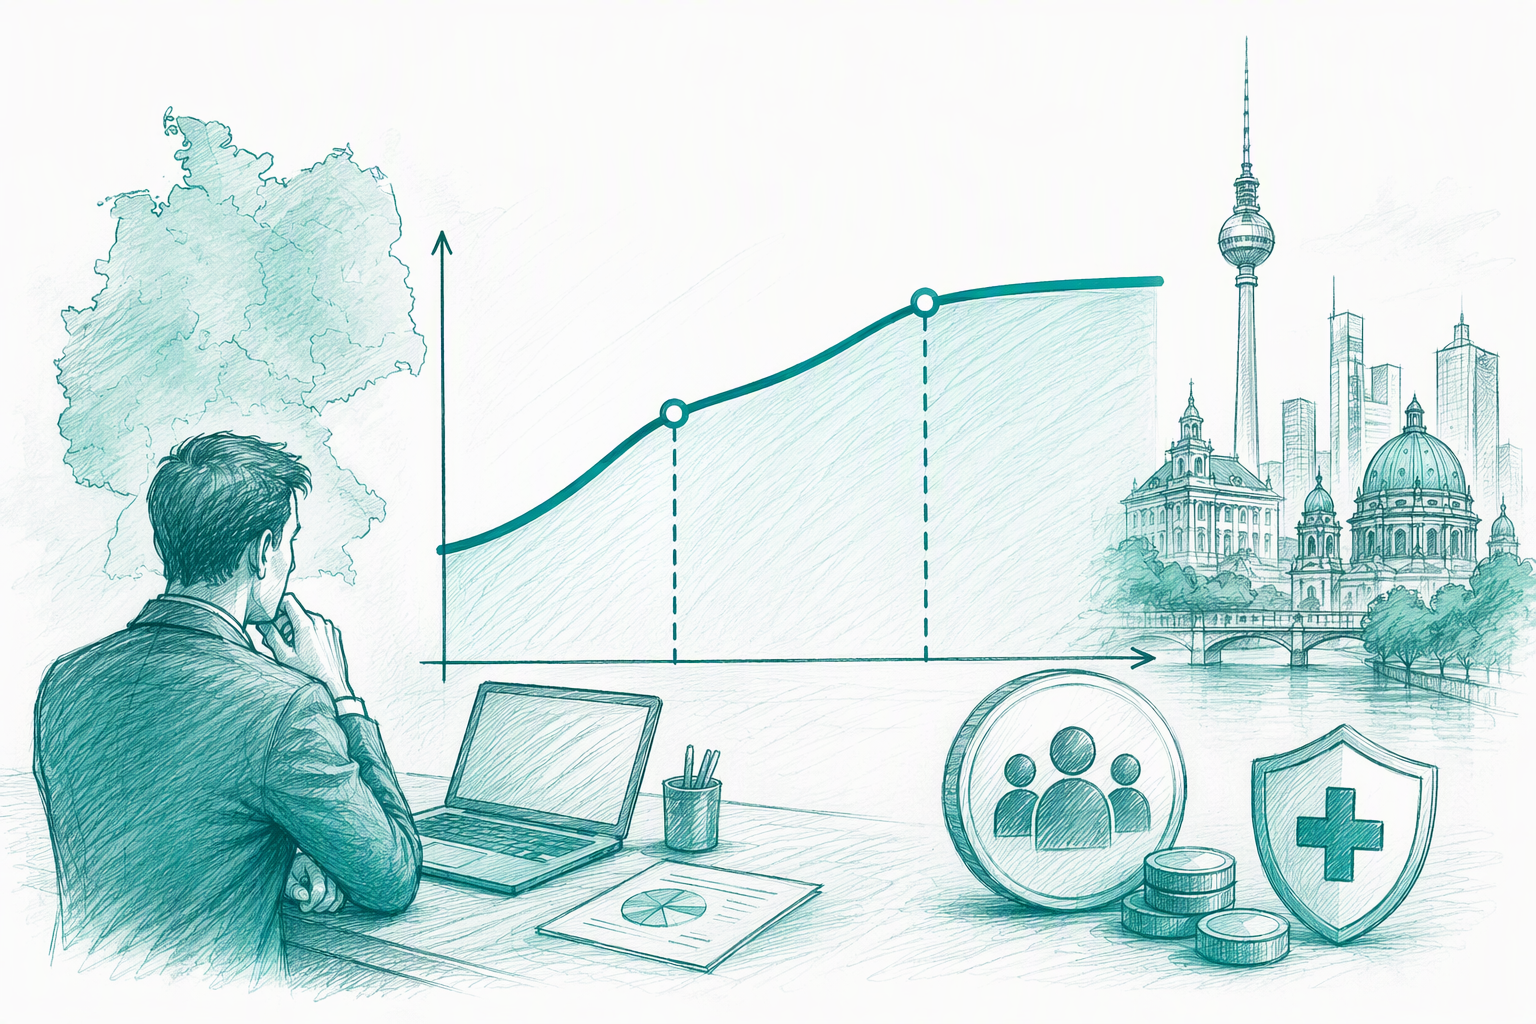
A contribution assessment ceiling is the maximum income used to calculate a particular social-insurance contribution. Earnings above that limit are excluded from the relevant contribution base.
The cost curve generally has three stages:
| Salary band | Typical effect |
|---|---|
| Below the health and care ceiling | Core employer contributions rise with eligible gross pay |
| Between the health-related and pension-related ceilings | Pension and unemployment costs may continue rising |
| Above the highest applicable ceiling | Core percentage-based contributions are generally capped |
This does not mean additional compensation becomes cost-free. Gross salary still increases directly, while bonuses, contractual benefits, provider pricing and some other charges may use different rules or bases.
Why the effective uplift can fall
At lower salaries, several core contributions may apply to each additional unit of eligible pay. Once one assessment ceiling is reached, only the contributions with a higher ceiling continue to rise.
After all relevant ceilings have been reached, the core social-insurance amount may remain stable even as salary increases. The employer’s total cost still rises, but the percentage uplift over gross salary can become smaller.
Costs missing from the headline contribution rate
Core social-insurance contributions are only one layer. Employers may also face payroll levies, statutory accident insurance, payroll administration and compliance costs.
Payroll levies
U1 can support reimbursement of qualifying continued sick-pay expenses and generally concerns eligible smaller employers. The rate and reimbursement arrangement depend on the relevant health insurer.
U2 relates to reimbursement of maternity-associated employer expenses and applies more broadly. The insolvency levy is set separately and may change over time.
We model these items individually rather than hiding them inside a general payroll percentage.
Berufsgenossenschaft accident insurance
Statutory accident insurance is employer-funded through the appropriate Berufsgenossenschaft. The premium depends on factors such as payroll, industry classification and occupational risk.
An office-based role may carry a different risk profile from work involving site visits, physical inspections or contractor coordination. A universal accident-insurance assumption can therefore distort the budget.
Registration and payroll administration
Direct German payroll may require:
- Employer and payroll registrations
- Wage-tax withholding and reporting
- Social-security registrations
- Health-insurer communication
- Payslip production
- Year-end processing
- Corrections and off-cycle runs
Separate setup charges from recurring payroll fees. Special payments, corrections and additional reporting may attract further costs.
Foreign workers on short-term projects also require careful tax and social-security documentation. Missing or incorrect records can create exposure during an audit, so apparent savings should not outweigh compliance checks.
How to build gross-to-total-cost scenarios
A reliable model starts with the employee’s annual gross salary and applies each cost according to its own rules. Avoid using the same contribution base for every line.
Include editable rows for:
- Health, care, pension and unemployment contributions
- Applicable payroll levies
- Accident insurance
- Payroll processing
- Benefits and allowances
- EOR or other provider fees
- One-time onboarding costs
- Offboarding contingencies
Run the calculation for the actual salary under consideration. Then test a lower and higher salary to see where contribution ceilings change the marginal cost.
We also recommend documenting every assumption beside the calculation. Record the source date, insurer, employee location, risk category and any fee exclusions. This makes the model easier to review and update.
Why net salary promises create gross-up risk
German employment agreements commonly define compensation in gross terms. Net pay depends on the employee’s tax, insurance and personal circumstances.
A fixed net promise transfers some of that variability to the employer. We prefer to negotiate gross compensation and budget relocation support, allowances or benefits separately.
What can change net pay
Take-home pay may vary with:
- Tax class
- Church-tax status
- Statutory or private health insurance
- Dependants and payroll records
- Taxable benefits
- Other employee-specific withholding details
Employees on the same gross salary can therefore receive different net amounts. Those differences should not be confused with employer contributions added above gross pay.
Managing an unavoidable gross-up
If a net guarantee is commercially necessary, request a payroll simulation based on documented employee information. Define which taxes and insurance amounts the guarantee covers.
The agreement should also explain what happens when the employee’s circumstances change. Include rules for payroll corrections, retroactive adjustments and changes to insurance or tax status.
Salary cost versus productive labor cost
Paid leave is already included in gross salary, so adding the salary cost of those days again would double count it. However, leave reduces the working time available for that annual cost.
Leave, holidays and sickness
To estimate productive labor cost, begin with working days and deduct contractual vacation, location-specific public holidays, training and expected absence. Divide total annual employer cost by the resulting available days or hours.
German employers may also have continued-remuneration obligations during sickness. Eligible smaller employers may recover part of qualifying costs through U1, depending on their arrangement.
Only add replacement labor where the role genuinely requires coverage. Some work can be deferred; operational or site-facing duties may need temporary support.
Notice and termination exposure
Notice periods, unused leave, garden leave, legal support and possible termination payments are contingent costs rather than automatic monthly contributions.
We recommend keeping a separate scenario reserve based on the contract and likely offboarding process. This preserves visibility without overstating ordinary monthly payroll.
Direct German payroll or EOR
The right employment route depends on headcount, duration, entity plans, internal expertise and exit risk. An EOR can have a higher visible monthly fee while still being practical for a limited hiring plan.
Our guide explains what an Employer of Record is and how its role differs from payroll software.
Direct-employment model
Direct employment may involve entity maintenance, bookkeeping, tax filings, social reporting, payroll registration and local advice. Companies with established German infrastructure should exclude sunk costs when comparing options.
Fixed setup and compliance costs can become more economical when spread across a larger workforce. They may be harder to justify for an isolated or short-term hire.
EOR invoice model
Review more than the advertised monthly fee. Ask about:
- Setup and onboarding
- Deposits
- Foreign-exchange margins
- Benefits administration
- Payroll adjustments
- Offboarding or transfer
- Termination support
A refundable deposit may not be a final expense, but it still ties up cash. We recommend comparing both routes over the expected employment period using the same assumptions.
Germany employer cost checks
Before approving a hire, confirm the salary, work location, insurer, employment route and occupational risk. Check which levies apply and whether the quote includes payroll corrections, onboarding and offboarding.
For an EOR, request an itemized invoice example and the exchange-rate policy. For direct payroll, identify setup work, recurring administration and internal compliance ownership.
Finally, keep employee deductions separate from employer expenses. This prevents take-home-pay estimates from inflating the company budget.
Build an itemized Germany hiring budget
Use Shor’s international payroll platform to request a transparent Germany employment quote covering statutory contributions, payroll levies, provider fees, deposits and offboarding costs. Compare the full recurring, one-time and contingent cost before approving the hire.
FAQ
How much does an employee cost above gross salary in Germany?
There is no universal uplift. The result depends on salary, contribution ceilings, health insurance, applicable levies, accident risk, benefits and payroll delivery. We recommend an itemized calculation rather than a flat percentage.
Are employee taxes an extra employer cost?
Generally, no. The employer withholds and remits employee taxes and employee social-insurance contributions, but these amounts normally come from gross compensation rather than being added above it.
Do employer contributions stop increasing at higher salaries?
Individual social-insurance contributions stop increasing after earnings reach their respective assessment ceilings. Salary, benefits, provider fees and other employment costs can continue to rise.
Is an EOR cheaper than direct German payroll?
Sometimes. An EOR may suit a small or temporary hiring plan without local infrastructure. Direct payroll may be more economical when an established entity and larger workforce can absorb fixed compliance costs.
Should an employment offer guarantee net salary?
We generally advise against it. Net pay depends on personal tax and insurance details. If a guarantee is necessary, document its scope, assumptions and adjustment rules clearly.