TL;DR
The nine states with no income tax on wages are Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. They are not tax-free. Property and sales taxes, insurance, business levies, and payroll programs can offset the savings. For founders, we recommend checking each employee’s physical work location and the company’s resulting registration obligations before running payroll.
Table of Contents
- The 9 states with no income tax in 2026
- No individual income tax does not mean no business tax
- How much could you actually save by moving?
- What payroll obligations remain when a state has no wage withholding?
- Can your employer’s state still tax you after you move?
- Relocating requires more than changing your address
- Which no-income-tax state is the best fit?
- Founder checklist before hiring in a no-income-tax state
- FAQ
- Make the work state part of every payroll decision
The 9 states with no income tax in 2026
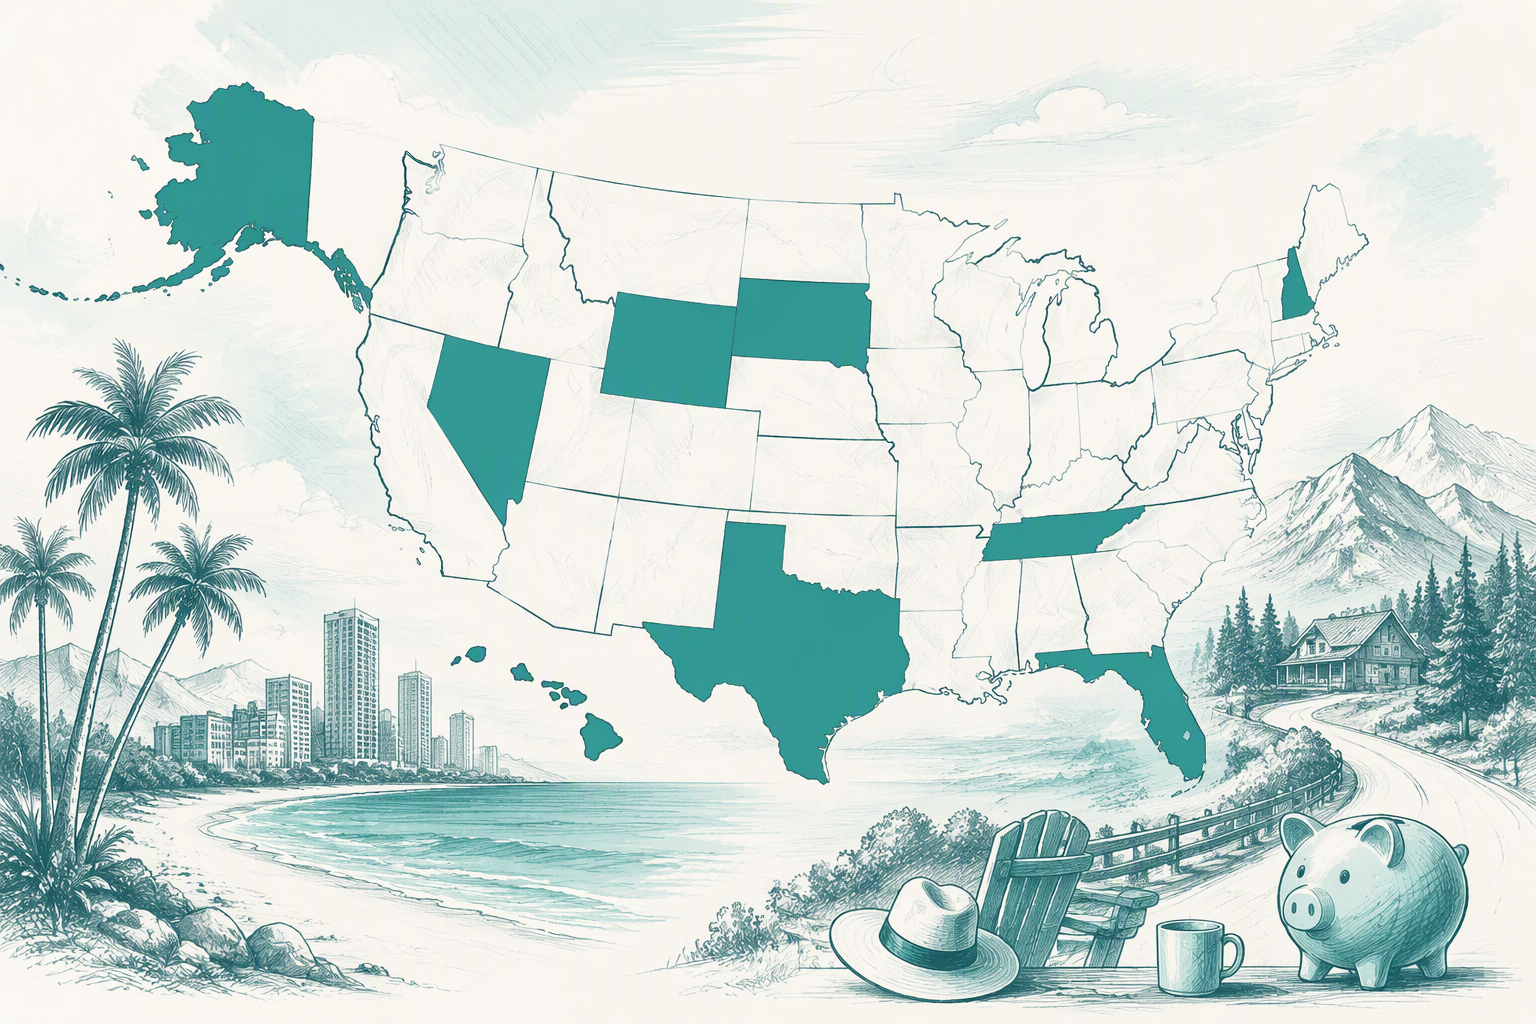
The nine states that do not impose a broad individual income tax on wages are:
- Alaska
- Florida
- Nevada
- New Hampshire
- South Dakota
- Tennessee
- Texas
- Washington
- Wyoming
Calling these states “tax-free” is misleading. Residents and businesses may still pay property taxes, sales taxes, business levies, payroll-related charges, insurance costs, tolls, and other fees. Local taxes can also change the total burden.
| State | Wage income tax | Costs and taxes to review |
|---|---|---|
| Alaska | None | Local sales and property taxes, business taxes, payroll programs |
| Florida | None | Sales and property taxes, insurance, tolls, business taxes |
| Nevada | None | Sales and property taxes, business levies, registration costs |
| New Hampshire | None | Property taxes, business taxes, payroll obligations |
| South Dakota | None | Sales and property taxes, industry-specific business taxes |
| Tennessee | None | Sales and property taxes, franchise and excise taxes |
| Texas | None | Property and sales taxes, franchise tax, payroll obligations |
| Washington | None | Sales taxes, business taxes, payroll programs, certain capital gains |
| Wyoming | None | Sales and property taxes, business and industry-specific levies |
Tax rules and program requirements change, so we recommend confirming current details with the relevant state agencies.
What “no income tax” actually means
The label generally means a state does not impose a broad individual tax on salaries and wages. It does not settle how the state treats:
- Capital gains
- Retirement income
- Pass-through business income
- Corporate revenue or profit
- Gross receipts
- Property
- Purchases
Those categories fall under different tax systems. A founder’s salary may avoid state income-tax withholding while the company still owes business or payroll-related taxes.
Why New Hampshire is on the 2026 list
New Hampshire is included because it no longer imposes a broad individual tax on wages, interest, or dividends. Older comparisons may describe its former tax on interest and dividends, so checking the date of any tax guide matters.
The state still has business-level taxes and local property taxes. Its place on the list does not mean residents or companies operate without state and local tax costs.
No individual income tax does not mean no business tax
Individual income tax, employee withholding, corporate tax, gross-receipts tax, pass-through taxation, and employer payroll tax are separate systems. Removing one does not remove the others.
That distinction matters when choosing where to hire, operate, or form a company. Entity type, revenue, payroll, industry, location, and filing rules can all create obligations.
Texas franchise tax, Washington B&O tax, and Nevada commerce tax
Texas has a franchise-tax system for taxable entities doing business in the state. A company may still have reporting obligations even when it does not owe tax.
Washington’s business and occupation tax generally focuses on gross receipts rather than net profit. Classification, sourcing, deductions, and local rules can affect the calculation.
Nevada may apply its commerce tax to businesses that cross the relevant revenue threshold. Other payroll-related business taxes can also apply. We recommend checking current thresholds and classifications rather than assuming the lack of individual income tax extends to the company.
Pass-through owners still need a multi-state analysis
Forming an LLC in Wyoming, Texas, or another no-income-tax state does not erase obligations where its owners live or where the company operates. The review may include nexus, income sourcing, apportionment, foreign qualification, residency, and entity-level elections.
Equity compensation adds complexity when employees work across states or move before vesting. Our guide to vesting schedules, ownership, taxes, and departures explains why payroll and tax records should reflect the relevant service periods.
How much could you actually save by moving?
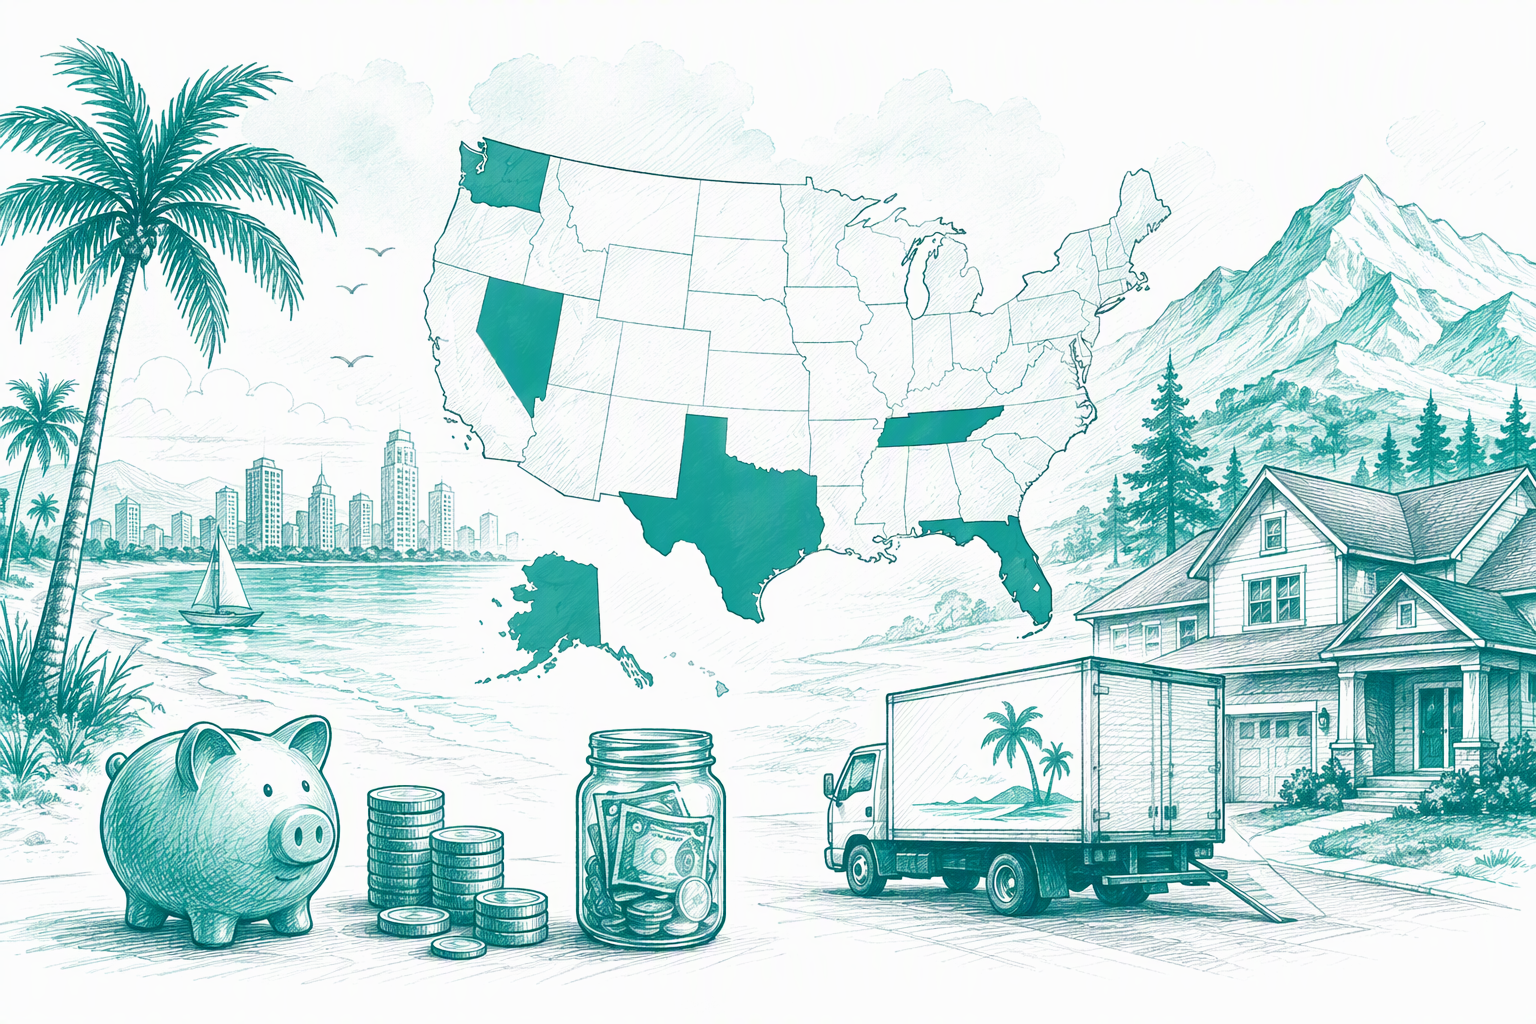
A useful comparison goes beyond applying the former state’s top tax rate to a salary:
Former-state income tax avoided − added housing, property tax, sales tax, insurance, transportation, fees, and compliance costs = estimated net savings
Taxable income, filing status, deductions, credits, and marginal brackets affect the result. A published top rate may apply to only part of a person’s income.
Higher earners may receive a larger dollar benefit from eliminating state income tax. For other households, housing, insurance, sales taxes, and fixed fees may absorb much of the apparent saving.
Example: an employee moving to Texas
Start by estimating the state income tax that would no longer apply. Then compare changes in:
- Rent or mortgage payments
- Property tax
- Home, renters, and auto insurance
- Taxable purchases
- Utilities and transportation
- Tolls and local fees
- Moving and compliance expenses
This produces a more realistic estimate than looking at income tax alone. Part-year residency, income sourcing, deductions, and filing status can also change the outcome.
Property tax, sales tax, insurance, and housing can reverse the result
Homeowners should compare purchase prices, assessments, exemptions, maintenance, and insurance. Renters should also account for these costs because landlords may reflect them in rent.
Insurance deserves location-specific quotes, particularly in areas exposed to hurricanes, floods, wildfires, hail, or other hazards. In our view, comparing actual homes and policies is more useful than relying on statewide averages.
What payroll obligations remain when a state has no wage withholding?
Payroll compliance generally depends on where an employee physically performs the work, not only on the employer’s headquarters, incorporation state, or mailing address.
Even without state wage withholding, employers may face:
- Payroll and labor registrations
- State unemployment insurance
- Wage reporting
- Paid-leave or employee-benefit premiums
- Workers’ compensation
- Local obligations
- Business registrations and returns
We recommend verifying agency requirements whenever a worker starts working in a new state.
A single remote employee can trigger registration and nexus
Hiring one remote employee may create unemployment, workers’ compensation, payroll-registration, foreign-qualification, or tax-nexus questions. The absence of individual wage withholding does not resolve them.
Different tax systems can use different nexus standards. Payroll registration does not automatically determine sales, franchise, corporate, or gross-receipts tax exposure.
Workforce changes create additional compliance risks. Our employer guide to furlough compliance covers pay, benefits, notice, and related legal questions.
Unemployment, paid leave, and workers’ compensation still apply
Employers may still need unemployment insurance and workers’ compensation coverage. Some states also operate paid-leave or other payroll-funded programs.
Coverage should match the employee’s actual work state. A multistate policy may require updates when a worker moves or changes assignments. Employers planning extended leave should also review our practical employer guide to sabbatical pay and compliance.
Can your employer’s state still tax you after you move?
A no-income-tax destination generally will not tax wages. However, the employer’s state may continue treating some income as sourced there under its own rules.
Some states consider where services are performed, where an employee is assigned, and whether remote work is for the employer’s benefit. These tests are state-specific and should be reviewed before payroll withholding changes.
Example: moving to Florida while keeping an out-of-state employer
If an employee keeps an out-of-state job after moving to Florida, the employer should determine:
- Where the employee performs services
- Which office the employee is assigned to
- Why the remote arrangement exists
- How often the employee returns to the former state
- How payroll records identify workdays
Florida’s lack of wage tax does not control another state’s sourcing analysis.
Documents that support your actual work location
Helpful records include employment agreements, remote-work approvals, assigned-office documents, travel calendars, timesheets, and payroll work-state coding.
Documentation supports the facts but does not override tax law. Payroll, HR, and tax records should remain consistent.
Relocating requires more than changing your address
Domicile generally means a person’s permanent home. Statutory residency may apply under separate tests involving a dwelling, day counts, or other connections.
A former state may challenge a claimed move, require a part-year return, or continue taxing income sourced there after residency ends.
Evidence that supports a bona fide move
Relevant evidence may include:
- A primary home purchase or lease
- Driver’s licence and vehicle registration
- Voter registration
- Homestead filings
- Updated financial and professional records
- Family and personal-property location
- Business and community ties
- Detailed travel logs
No single document controls the outcome when the broader facts point elsewhere.
Part-year returns and income earned after the move
Income may need to be allocated using workdays, service periods, transaction dates, or other sourcing rules. Moving during the year does not automatically make the entire year free from former-state tax.
Keep clear records for bonuses, equity compensation, deferred compensation, business sales, and investment transactions that cross the move date.
Which no-income-tax state is the best fit?
There is no universal winner. We recommend comparing income type, housing, insurance, business structure, work location, expected purchases, and intended length of residence.
| Reader | Main factors to compare |
|---|---|
| Employee | Take-home pay, housing, insurance, sales tax, income sourcing |
| Founder | Business taxes, registrations, payroll programs, nexus |
| Investor | Capital-gains treatment, asset type, sourcing, residency |
| Retiree | Housing, healthcare, insurance, property taxes, estate planning |
Best fit for employees and founders
Employees should compare take-home pay with recurring living costs and possible employer-state taxation.
Founders need to add unemployment insurance, workers’ compensation, entity filings, business taxes, and administrative work. Our comparisons of Shorpay and Papaya Global and Shorpay and Oyster HR outline practical questions for distributed payroll.
Best fit for investors and retirees
Investors should review capital-gains rules, exemptions, sourcing, and transaction timing. No wage tax does not guarantee that every investment gain avoids state taxation.
Retirees should compare healthcare access, housing, property-tax relief, insurance, sales taxes, and estate plans. The lowest income-tax bill may not produce the lowest annual cost.
Founder checklist before hiring in a no-income-tax state
We treat each new work state as a compliance event. Shorpay can help organise distributed payroll data and recurring workflows, but software does not replace state-specific legal or tax advice.
Before the employee starts
Confirm:
- Physical work location and local jurisdiction.
- Employing entity and worker classification.
- Compensation, benefits, travel, and client assignments.
- Business-registration requirements.
- Payroll and unemployment accounts.
- Leave and workers’ compensation coverage.
- Business-tax and nexus exposure.
During payroll setup and ongoing compliance
Code the correct work state, collect required forms, and track filings, payments, notices, and reconciliations.
Reassess the setup whenever an employee moves, travels regularly, transfers to a client site, changes roles, takes leave, or separates.
Make the work state part of every payroll decision
Before hiring or relocating an employee, map the physical work location to payroll, unemployment, leave, workers’ compensation, registration, and business-tax requirements. Use Shorpay to keep distributed payroll data and compliance workflows aligned as your team grows.
FAQ
What is the most tax-friendly state?
There is no single answer. The best choice depends on income, investments, property, spending, insurance, and business activity. We recommend comparing total annual costs using personal figures.
Is living in a state with no income tax always cheaper?
No. Property taxes, sales taxes, housing, insurance, tolls, and fees may offset the income-tax saving.
Which no-income-tax state is best for retirement?
That depends on housing, healthcare, insurance, property-tax relief, sales taxes, estate planning, and proximity to family. No state is automatically best for every retiree.
Do no-income-tax states tax Social Security or 401(k) distributions?
The nine states do not impose a broad individual state income tax on those payments. Federal tax may still apply, and other living costs remain relevant.