TL;DR
In an eor vs umbrella company comparison, the two models are not interchangeable. An employer of record (EOR) generally employs staff in countries where a business lacks its own entity. A UK umbrella company commonly employs contractors completing temporary agency assignments. We recommend comparing the employing entity, contract chain, total cost and retained liabilities rather than relying on a provider’s label.
Table of contents
- EOR vs umbrella company: the short answer
- EOR vs umbrella company comparison table
- Who signs each contract, employs the worker, and controls the work?
- Who is liable when payroll, tax, or employment compliance goes wrong?
- Umbrella company pay explained: from assignment rate to take-home pay
- EOR pricing: calculate the total employment cost, not just the monthly fee
- UK umbrella companies, PAYE, agency workers, and IR35
- Which hiring model should you use?
- FAQ
- Build the right international hiring model
EOR vs umbrella company: the short answer
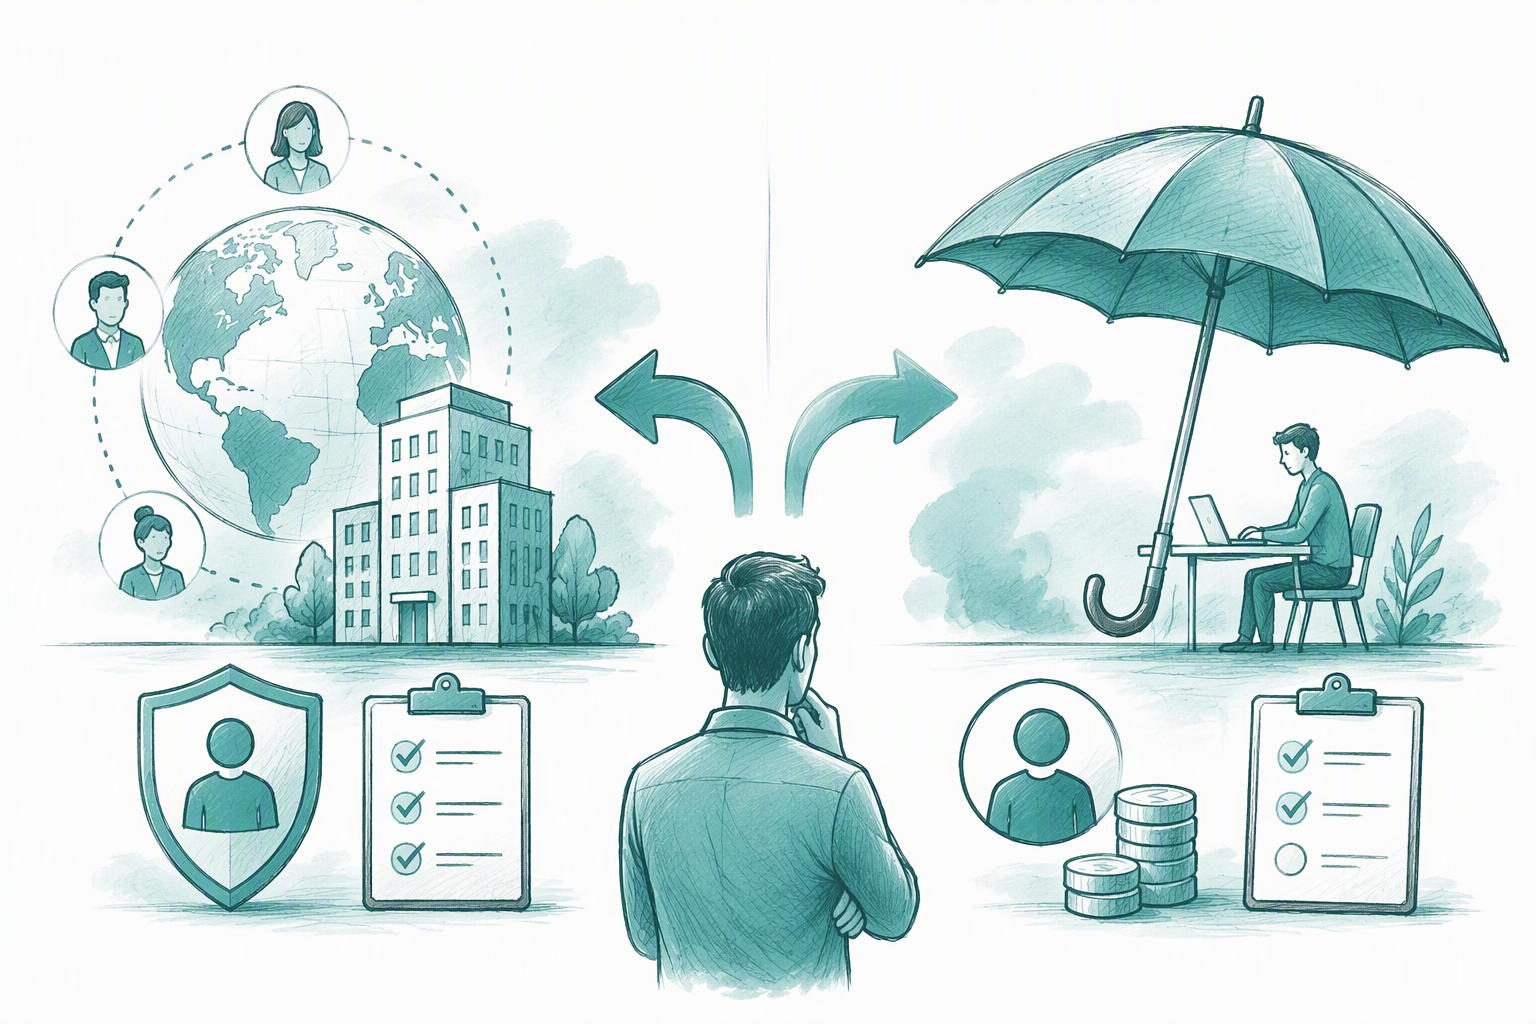
The right model depends on the worker, country and assignment. An umbrella company is not simply a cheaper EOR. Umbrellas are commonly associated with UK agency contractors paid through PAYE, while an EOR typically employs a worker in a country where the client lacks an employing entity.
An EOR should have an appropriate local structure or clearly disclose any local partner involved. Our guide to employers of record explains how this employment model works.
Neither arrangement transfers every risk. The client still controls much of the day-to-day work and may retain responsibilities involving safety, discrimination, immigration, worker status or corporate tax.
Choose an EOR when
- The business needs an employee abroad but lacks a local entity.
- The role requires local payroll, benefits, leave and termination administration.
- The provider can identify the employing entity and explain its registrations.
- The working relationship resembles employment rather than independent contracting.
For example, a US company hiring an employee in France may use a properly established French EOR. A UK-style umbrella arrangement does not, by itself, satisfy French employment requirements.
Consider an umbrella company when
- A worker is completing a suitable UK agency assignment.
- The worker, agency and end client understand the rate, deductions and contracts.
- The arrangement is not being used to disguise the worker’s actual status.
- The provider gives clear explanations rather than promising unusually high take-home pay.
EOR vs umbrella company comparison table
| Issue | Employer of record | Umbrella company |
|---|---|---|
| Primary use | Employing staff for a client in a particular country | Paying workers completing agency assignments |
| Typical worker | International employee | UK contractor or agency worker |
| Legal employer | Identified local EOR entity | Umbrella named in the employment contract |
| Contract chain | Client–EOR and EOR–employee | Worker–umbrella, umbrella–agency and agency–client |
| Payroll | Local withholding and filings | Usually PAYE and related payroll administration |
| Fees | Flat or percentage-based service fee, plus employment costs | Margin included within the assignment-rate reconciliation |
| Daily control | Usually exercised by the client | Usually exercised by the end client |
| Liability | Divided by law and contract | Divided among the parties according to law, contract and conduct |
| Best fit | Hiring employees where no local entity exists | Suitable UK temporary assignments |
Provider terminology is not proof of compliance. We recommend checking contracts, registrations, bank flows, payroll processes and actual working practices.
The differences that matter most
An EOR model is built around employing staff for a client in a specified country. A UK umbrella arrangement usually centres on employing workers who perform assignments sourced through agencies.
Costs also work differently. An EOR’s monthly fee cannot be compared directly with an umbrella’s margin without considering salary, employer costs, benefits, deductions, foreign exchange and exit charges.
What the two models have in common
Both models may process payroll, withhold taxes, issue payslips and appear as the employer in written agreements. Both rely on accurate information about hours, pay, roles and worker circumstances.
Neither can correct misleading contracts or unlawful client instructions. Calling a provider the “legal employer” does not remove every responsibility from the business directing the work.
Who signs each contract, employs the worker, and controls the work?
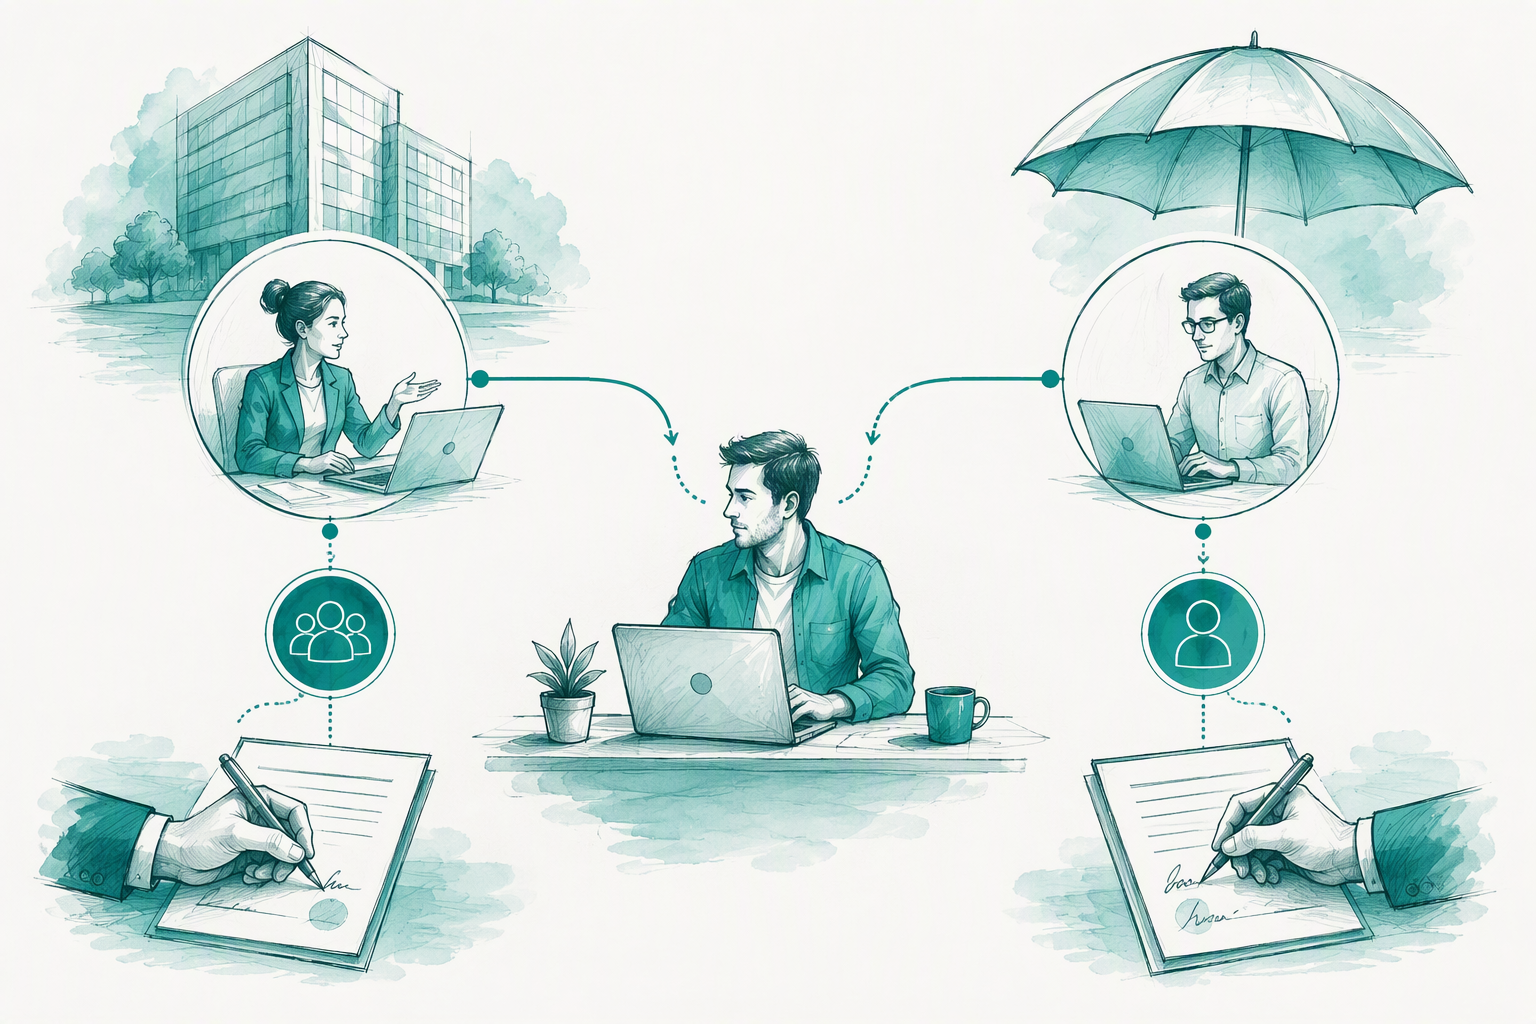
The contractual employer and the organisation controlling daily work may be different. That separation is central to comparing an umbrella company with an EOR.
The EOR contract chain
The usual structure includes:
- A services agreement between the client and EOR.
- A local employment agreement between the EOR entity and employee.
- Operational instructions from the client.
The client generally provides role details, compensation decisions, performance feedback and leave information. The EOR administers formal employment processes within its contractual scope and applicable local law.
We also examine indemnities, liability caps and exclusions. Some contracts return costs to the client when its instructions contribute to a tax, conduct, classification or dismissal dispute.
The umbrella contract chain
A common UK structure includes:
- An employment contract between the worker and umbrella.
- A commercial contract between the umbrella and agency.
- A contract between the agency and end client.
- Assignment terms for the placement.
Information about hours, rates, expenses and assignment dates passes through this chain. Errors can flow into payroll, so the documents and workplace practices need to align.
Who is liable when payroll, tax, or employment compliance goes wrong?
Responsibility depends on applicable law, contractual terms and each party’s conduct. A provider may accept responsibility for payroll administration, but private contracts do not necessarily prevent claims by workers or authorities.
Before signing, we recommend reviewing registrations, insurance, indemnities, liability caps, audit rights and complaint procedures.
What the provider normally handles
Depending on the country and contract, the provider may handle:
- Payroll calculations and payslips
- Tax withholding and employer filings
- Statutory benefit administration
- Employment documentation
- Formal leave and termination processes
- Employment-record maintenance
These tasks depend on accurate client instructions. Incorrect hours, pay details or performance records can still produce incorrect or delayed outcomes.
What remains with the client or end client
The client remains responsible for truthful role information, lawful management, accurate compensation inputs and safe working conditions. Its actions can also contribute to discrimination, harassment, safety or worker-status claims.
Corporate tax and immigration require separate attention. We never assume that payroll processing automatically resolves permanent-establishment exposure, work authorisation or sponsorship obligations.
Umbrella company pay explained: from assignment rate to take-home pay
An umbrella assignment rate is not necessarily the worker’s salary or taxable gross pay. It is a commercial amount used to fund relevant employment costs, the umbrella’s margin and gross compensation.
Even when the margin is deducted before gross pay is calculated, it reduces the assignment-rate balance available for compensation.
Illustrative assignment-rate waterfall
Rather than relying on headline take-home estimates, follow the rate through each stage:
- Assignment amount, with VAT treatment clearly identified
- Relevant employer costs and holiday-pay funding
- Umbrella margin
- Taxable gross pay
- PAYE, employee National Insurance, pension and authorised deductions
- Net take-home pay
The treatment of each item depends on current rules, assignment terms and personal circumstances. Providers should supply a clear reconciliation instead of presenting the assignment rate as salary.
Payslip and Key Information Document checks
Compare the agency’s Key Information Document, assignment terms, reconciliation and payslip. Check for:
- Unexplained deductions
- Gross pay changes that do not match hours or rates
- Undisclosed holiday-pay treatment
- Charges missing from pre-assignment documents
- Payments described as loans, grants, advances or non-taxable credits
We treat promises of unusually high take-home pay as a warning sign requiring careful review.
EOR pricing: calculate the total employment cost, not just the monthly fee
EOR pricing may use a flat charge or a percentage of payroll. Neither method shows the full cost on its own.
Include salary, employer taxes, statutory benefits, supplemental benefits, platform fees and foreign-exchange costs. Our international employer cost calculator helps model the underlying employment cost before provider extras.
Questions to ask for a comparable quote
Ask each provider:
- Which billing currency and exchange-rate source apply?
- Is an FX spread added?
- Which benefits and services are included?
- Which costs are estimates?
- Are deposits required, and when are they returned?
- Do payroll amendments or off-cycle payments cost extra?
- What charges apply when employment ends?
Model the cost of exit before hiring
Consider notice, accrued leave, severance, consultation and required filings under local law. Confirm whether termination requires prefunding or an additional fee.
Ending a commercial EOR contract does not necessarily end local employment immediately. If a vendor change is needed, use a controlled EOR provider transition process to protect payroll continuity and employment records.
UK umbrella companies, PAYE, agency workers, and IR35
PAYE and umbrella employment are not alternatives. PAYE is a tax-withholding system; an umbrella company is an employment and payroll arrangement that generally operates PAYE.
An agency may require workers to use an approved payroll route for a particular assignment. That commercial condition is different from a universal legal requirement. Current official guidance should be checked before making decisions about PAYE, agency work, holiday pay, pensions or off-payroll rules.
Is PAYE or umbrella better?
The useful comparison is direct PAYE employment by an agency or end client versus PAYE employment through an umbrella. We suggest comparing total compensation, deductions, rights, assignment access and contract clarity.
Can a worker be forced to use an umbrella company?
An agency or end client may make an approved umbrella a condition of accessing an assignment. Workers can ask whether direct PAYE or another approved route is available and should review all disclosures before accepting.
Umbrella compliance red flags
- Guaranteed take-home pay that appears inconsistent with ordinary PAYE
- Payments presented as loans, grants or tax-free credits
- No clearly identified employer
- Missing contracts or incomplete payslips
- Undisclosed deductions
- Unclear holiday-pay treatment
- Claims that PAYE resolves every status or IR35 concern
Which hiring model should you use?
Options include setting up an entity, using an EOR, engaging an independent contractor or working through a staffing or umbrella arrangement. We assess country, duration, control, intellectual property, immigration, tax exposure and exit plans.
Decision rules for cross-border hiring
An EOR may suit an employee in a supported country before a local entity is justified. Entity setup may become more appropriate when operations are long-term or commercially substantial.
Independent contractor status should be used only where the facts support genuine independence. Staffing agencies and umbrella arrangements may suit temporary UK assignments, while direct agency PAYE can also be appropriate.
Buyer due-diligence checklist
Before selecting a provider:
- Identify the employing entity and registrations.
- Confirm bank flows, insurance and subcontractors.
- Request the complete fee schedule and FX policy.
- Review sample contracts, payslips and benefits.
- Document responsibility for leave, performance and complaints.
- Confirm immigration responsibilities.
- Review termination, transfer and deposit procedures.
- Examine indemnities, liability caps and audit rights.
At Shor, we help founders make international payroll costs and responsibilities clearer. We focus on the actual country and employment structure rather than forcing every hire into the same model.
Frequently asked comparison questions
An “umbrella LLC” is not a standard synonym for a UK umbrella company or EOR. A limited company is also different: its shareholders own the business, whereas an umbrella generally employs and pays the worker.
A provider can support overseas workers only where its structure complies with the relevant country’s requirements. The key question is which entity employs the worker, not whether the provider markets itself as global.
Build the right international hiring model
Map the country, worker status, contract chain, total cost and retained liabilities before choosing a provider. Explore Shor’s international payroll platform to assess a practical structure for hiring and paying your overseas team.
FAQ
What are the disadvantages of an umbrella LLC?
An umbrella LLC may refer to a corporate or asset-holding structure rather than an employment service. Its disadvantages depend on the jurisdiction and may include administrative complexity, tax consequences and an unsuitable separation of liabilities.
What is the difference between a limited company and an umbrella company?
A limited company is owned by its shareholders and has its own accounting and tax responsibilities. Under a UK umbrella arrangement, the worker is generally employed by the umbrella, which operates PAYE.
Is PAYE or umbrella better?
Neither is inherently better because they describe different things. Compare direct PAYE employment with umbrella employment based on compensation, deductions, rights and contract clarity.
Can I be forced to use an umbrella company?
An agency or client may require an approved umbrella for a specific assignment. Ask about alternative payroll routes and verify legal claims using current official guidance.
Can an umbrella company employ overseas workers?
Only where an appropriate entity and arrangement comply with the worker’s local laws. A UK umbrella contract alone does not satisfy another country’s employment, payroll or immigration requirements.
Does an EOR remove permanent-establishment risk?
No. An EOR can administer employment and payroll, but the worker’s activities may still create corporate-tax questions requiring country-specific advice.