TL;DR
To pay contractors in Colombia without avoidable disputes, agree on the invoice amount, settlement currency, fee allocation, conversion method, and required net receipt before sending funds. A USD-denominated invoice does not guarantee USD delivery. We recommend choosing a payment method based on what the contractor will receive and how easily the finance team can reconcile it—not simply the lowest advertised fee.
Table of contents
- TL;DR
- Table of contents
- How to pay contractors in Colombia without a surprise shortfall
- USD wire or local COP payout: which delivers the agreed amount?
- A repeatable Colombia contractor payment workflow
- Documents to collect before paying a Colombian contractor
- Contract terms that prevent payment disputes
- Contractor or employee? Test the working relationship before paying
- Tax, withholding, social security, and company exposure
- What does a contractor payment actually deliver?
- FAQ
- Make Colombian contractor payouts predictable
How to pay contractors in Colombia without a surprise shortfall
Before initiating payment, agree on five points: the gross obligation, settlement currency, fee allocation, conversion method, and amount the contractor should receive. “USD 2,000 per month” is incomplete if the contract does not explain whether that figure is the invoice value, funded amount, or guaranteed net receipt.
A USD contract also does not mean dollars will reach the contractor. Delivery depends on the receiving account, payment rail, intermediary banks, provider capabilities, and receiving-bank rules.
We use international payroll infrastructure to make recurring approvals and payout records easier to manage. We do not assume one payment rail is always cheapest. Our guide to paying international contractors explains how currency, compliance, and reconciliation affect the full cost.
| Method | Main advantage | Main risk | Best fit |
|---|---|---|---|
| USD wire | May allow direct USD delivery | Intermediary and receiving deductions can be unclear | Contractor can hold USD and accepts settlement variability |
| Fintech transfer | Pricing may be clearer than a bank wire | Currency and account support vary | Occasional payments with confirmed delivery terms |
| Local COP payout | Delivers spendable local currency | FX method and timing must be clear | Contractor uses COP and wants a predictable receipt |
| Contractor payment platform | Centralizes approvals and records | Costs may exceed a basic transfer fee | Teams managing recurring or batch payments |
The details to confirm before sending funds
Finance should record:
- Invoice amount and currency.
- Payout currency and expected contractor receipt.
- Sender, platform, intermediary, and receiving fees.
- FX source, spread, and rate-lock point.
- Expected settlement date and payment reference.
If a material detail is unknown, the payment is not yet predictable. Ask whether the contractor expects a gross payment or a guaranteed net amount before funding it.
Why the cheapest quote may cost more operationally
A low visible fee does not always produce a low total cost. Failed transfers, unidentified deposits, missing references, manual reconciliation, and disputes over shortfalls all consume time.
Teams paying multiple Colombian contractors should use batch approvals, unique references, and a defined exception process rather than relying on payment screenshots and manually updated spreadsheets.
USD wire or local COP payout: which delivers the agreed amount?
Paying a Colombian contractor in USD is not automatically better. If the contractor only has a COP account, a USD transfer may be converted by the receiving bank after applicable deductions and at a rate the parties did not confirm.
A disclosed COP payout can be more predictable for someone who spends in pesos. The payer can record the original USD obligation, conversion rate, fee, and final COP delivery before releasing the payment.
| Factor | USD wire | Local COP payout |
|---|---|---|
| Settlement currency | USD only when the account and rail support it | COP |
| Intermediary deductions | Possible | May be included in provider pricing |
| FX timing | May occur at the receiving bank | Set or disclosed by the provider |
| Receiving fees | Bank-dependent | Provider- and bank-dependent |
| Traceability | Bank or SWIFT reference | Provider reference and local confirmation |
Neither method has a universal delivery time or exchange rate. Banking cutoffs, reviews, holidays, provider rules, and incorrect account details can all affect settlement.
When a USD payment makes sense
A USD payment may work when:
- The contractor has an account that can receive and hold USD.
- The contract allocates sender, intermediary, and receiving fees.
- Both parties accept potential timing or deduction differences.
- Finance can reconcile the funded amount against the final receipt.
Confirm account capabilities directly. An account showing a USD balance option may not support every type of international transfer.
When a COP payout is more predictable
A COP payout may be cleaner when the contractor needs pesos and the provider discloses the rate and fee before funding. It also gives finance a record connecting the USD obligation to the delivered COP amount.
What matters is the agreed receipt, not the currency label. A local payout can be more effective than a nominally cheaper wire if it prevents unexplained deductions.
Contract wording for currency and fees
Separate pricing from delivery:
The service fee is denominated in USD. Payment may be settled in COP using the provider’s disclosed exchange rate at the stated rate-lock point. The client bears [specified fees], while the contractor bears [specified fees]. Rejected payments, incorrect bank details, and shortfalls will be handled through the agreed correction process.
The contract should also address exchange-rate changes after a rejection, deadlines for corrected details, and responsibility for unexpected deductions.
A repeatable Colombia contractor payment workflow
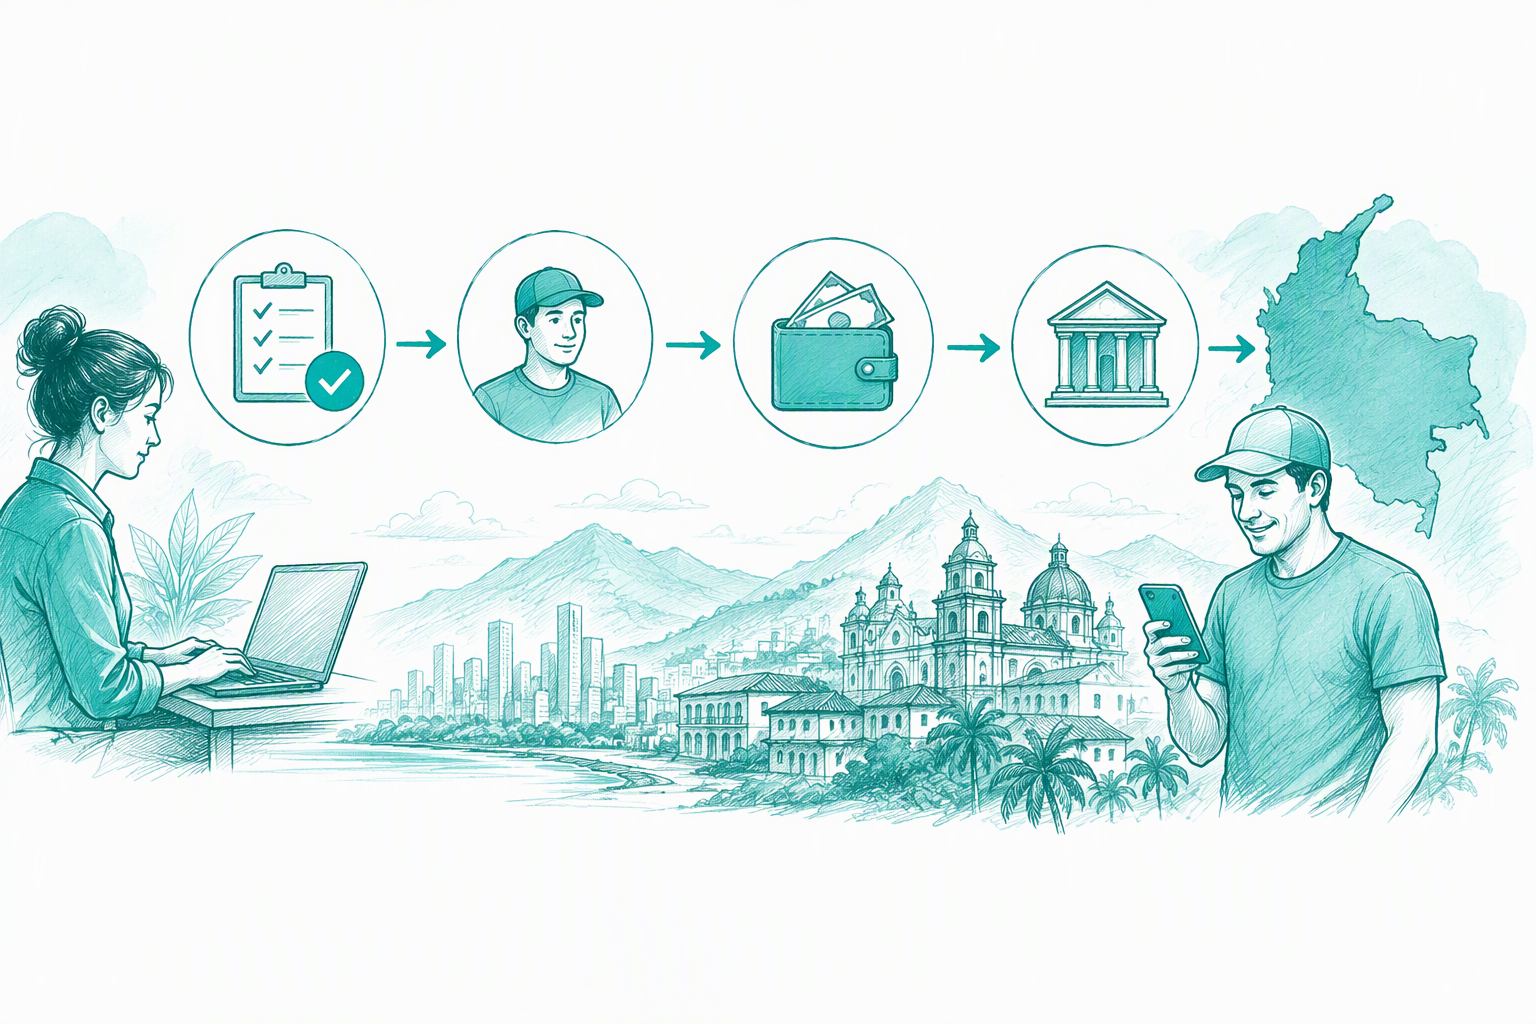
A reliable process separates onboarding, work approval, invoice validation, payment execution, and record retention. A platform can standardize these steps, but it cannot decide whether a worker is legally a contractor or determine which taxes apply.
Before the first payment
Complete the following:
- Confirm the contractor’s legal name, identity details, tax information, and account ownership.
- Sign the services agreement and define invoice requirements.
- Confirm invoice currency, payout currency, fees, and expected receipt.
- Complete appropriate identity, sanctions, and banking checks.
- Decide whether the role needs an employment-status review.
Use a controlled onboarding channel rather than collecting sensitive bank details through informal messages.
For every payment cycle
Approve the deliverable or milestone, then validate the invoice, reference, exchange rate, fees, and expected payout.
Retain the invoice, approval, funded amount, FX record, transfer confirmation, final delivery record, and notes about any delay or correction. These records are more useful than a screenshot showing only that a transfer was initiated.
For recurring payments, establish submission cutoffs, approval owners, unique references, and escalation rules. With Shor’s international payroll platform, teams can organize repeatable payment execution and payout records instead of rebuilding the process each month.
Documents to collect before paying a Colombian contractor
Separate the permanent onboarding file from payment-cycle records. Requirements can vary according to the contractor’s tax and invoicing status, the payer’s location, local presence, and the services performed.
Identity, tax, banking, and contract records should be encrypted, access-controlled, and retained under a documented policy.
Core onboarding file
The file may include:
- Identity and legal-name information.
- RUT or other applicable tax details.
- Signed services agreement.
- Intellectual-property and confidentiality terms.
- Verified bank or payout details.
- Evidence that the account belongs to the contractor.
Collect only what the process requires. Sensitive records should not remain in shared inboxes or unrestricted folders.
Invoice and DIAN checks
Confirm whether the contractor must issue a DIAN-compliant electronic invoice based on current rules and their circumstances. Do not assume every contractor follows the same invoicing process.
A contractor invoice is distinct from the Electronic Payroll Payment Support Document associated with employment-related tax support. It is also separate from PILA, which is used in connection with social-security contributions.
We recommend checking current DIAN guidance and obtaining advice from a qualified Colombian professional where the payer’s obligations are unclear.
Social-security evidence
Independent workers may have health, pension, or occupational-risk obligations. Depending on the engagement and the payer’s compliance controls, the company may request relevant contribution evidence.
Collecting evidence does not resolve misclassification. Questions about contribution bases, risk classifications, or payer responsibilities require local advice.
Contract terms that prevent payment disputes
A practical contractor agreement should cover scope, deliverables, acceptance, invoicing, currency, FX, fees, intellectual property, confidentiality, data security, termination, and disputes.
Spanish or bilingual drafting may improve comprehension, although the appropriate language depends on the parties and governing-law arrangements. We recommend Colombian legal review rather than relying on an unchanged global template.
Payment and acceptance clauses
Define milestones, completion evidence, acceptance windows, invoice timing, due dates, currencies, FX timing, fee responsibility, and correction procedures. The agreement should also explain what happens when bank details are wrong or a payment is rejected.
Autonomy and working methods
Describe outcomes rather than imposing employee-style controls. The written agreement should match daily operations.
An autonomy clause offers little protection if the company requires fixed hours, exclusivity, a mandatory location, and constant supervision. Classification depends on the full working relationship, not just the contract’s title.
Intellectual property, confidentiality, and termination
Address ownership or assignment of work product, confidentiality, data security, information return or deletion, termination notice, and final payment. Governing-law and dispute-resolution provisions should be reviewed by qualified counsel because local mandatory rules and cross-border enforcement may affect them.
Contractor or employee? Test the working relationship before paying
Calling someone a contractor does not settle their legal status. Colombian advisers or authorities may consider how the relationship operates, including the degree of direction, supervision, integration, and independence.
Potential warning signs include fixed schedules, controlled methods, continuing exclusivity, mandatory work locations, and employee-style performance management. Paying through an international contractor platform does not remove this risk.
Indicators of genuine independence
A contractor arrangement may be more defensible when:
- The worker controls their methods and organizes their time.
- Services relate to defined projects, outcomes, or deliverables.
- The contractor can serve other clients.
- The contractor carries genuine independent-business responsibilities.
- Acceptance focuses on results rather than daily supervision.
These are general indicators, not a complete legal test.
Pause onboarding when a role requires indefinite availability, close daily direction, exclusivity, or employee-style management. If that control is essential, consider direct employment or review what an employer of record does.
Tax, withholding, social security, and company exposure
Contractor income tax, social security, payer obligations, and company-level exposure are separate issues. A foreign company should not assume that operating without a Colombian entity removes every local concern.
The analysis can depend on tax residence, service location, payer status, local presence, contract authority, income-source rules, and applicable treaties. A Colombian entity may also have different withholding, reporting, or support-document duties from a foreign payer.
Shor facilitates payment execution and recordkeeping. We do not determine tax residence, worker classification, withholding liability, or permanent-establishment exposure.
Ask where the contractor performs the services, what invoicing status applies, and which social-security registrations or evidence may be relevant. For the payer, review whether anyone in Colombia negotiates contracts, binds the company, makes management decisions, or otherwise exercises local authority.
Retain contracts, invoices, approvals, tax details, relevant contribution evidence, FX records, payment confirmations, exception notes, and significant professional advice. An international employer cost calculator can support budget planning, but it does not replace Colombian tax or legal advice.
What does a contractor payment actually deliver?
A quoted contractor fee is not the same as an employee salary. Contractors may fund their own leave, equipment, administration, insurance, downtime, taxes, and social contributions.
Build rates around the role, experience, scope, skill scarcity, required availability, business costs, payment costs, and value of the deliverables. State whether the price is gross, net of transfer fees, or a guaranteed receipt.
For a hypothetical USD-denominated invoice, a wire may arrive after intermediary or receiving deductions and then be converted by the bank. A disclosed local payout instead records the provider fee, rate-lock point, and expected COP delivery before funding. If the agreement guarantees a net amount, the payer may need to cover deductions that would otherwise create a shortfall.
Make Colombian contractor payouts predictable
Define the currency, fees, FX method, and required receipt before the next payment. Talk to us about a repeatable international payroll workflow for Colombian contractors, recurring batches, and organized payout records.
FAQ
Can we pay a Colombian freelancer in USD?
The parties may price services in USD, subject to applicable rules and provider requirements. The contractor may still receive COP. Confirm account capabilities, payout currency, conversion method, fees, rate timing, and the required receipt first.
Can we hire a contractor in Colombia without a local entity?
A foreign company may be able to enter a services arrangement without opening a Colombian entity. That does not eliminate classification, tax, reporting, or company-exposure questions. We recommend reviewing the arrangement with qualified counsel.
Does paying through a platform remove misclassification risk?
No. Classification depends on the legal and operational facts, not the transfer method. A platform can manage approvals, payment evidence, FX records, and reconciliation.
What payment records should we retain?
Keep the agreement, invoice, work approval, funded amount, currency conversion details, fees, payment reference, delivery confirmation, and notes about rejected or corrected payments.
How often should the process be reviewed?
Review it whenever the engagement changes or relevant Colombian tax, labor, social-security, invoicing, or foreign-exchange rules are updated. Periodic review with Colombian advisers can help keep contracts and operating practices aligned.