TL;DR
To pay contractors in Kenya reliably, focus on what reaches the contractor, not only what leaves the company account. We recommend separating contract currency from settlement currency, reviewing fees and foreign exchange costs, confirming tax and worker-classification treatment, and keeping a complete payment record.
Table of Contents
- TL;DR
- Table of Contents
- How to pay contractors in Kenya without losing track of the net amount
- Can you pay freelancers in Kenya in USD? Three settlement scenarios
- USD or KES pricing: choose the contract currency before the payment rail
- Compare Kenyan contractor payout rails by landed cost and control
- Kenyan withholding tax: determine whether the payer must deduct before sending funds
- Build a reconciliation record for every Kenyan contractor payment
- Before you hire a contractor in Kenya, test the real working relationship
- When repeated Kenyan hiring requires a bigger compliance decision
- FAQ
- Control your next Kenyan contractor payment
How to pay contractors in Kenya without losing track of the net amount
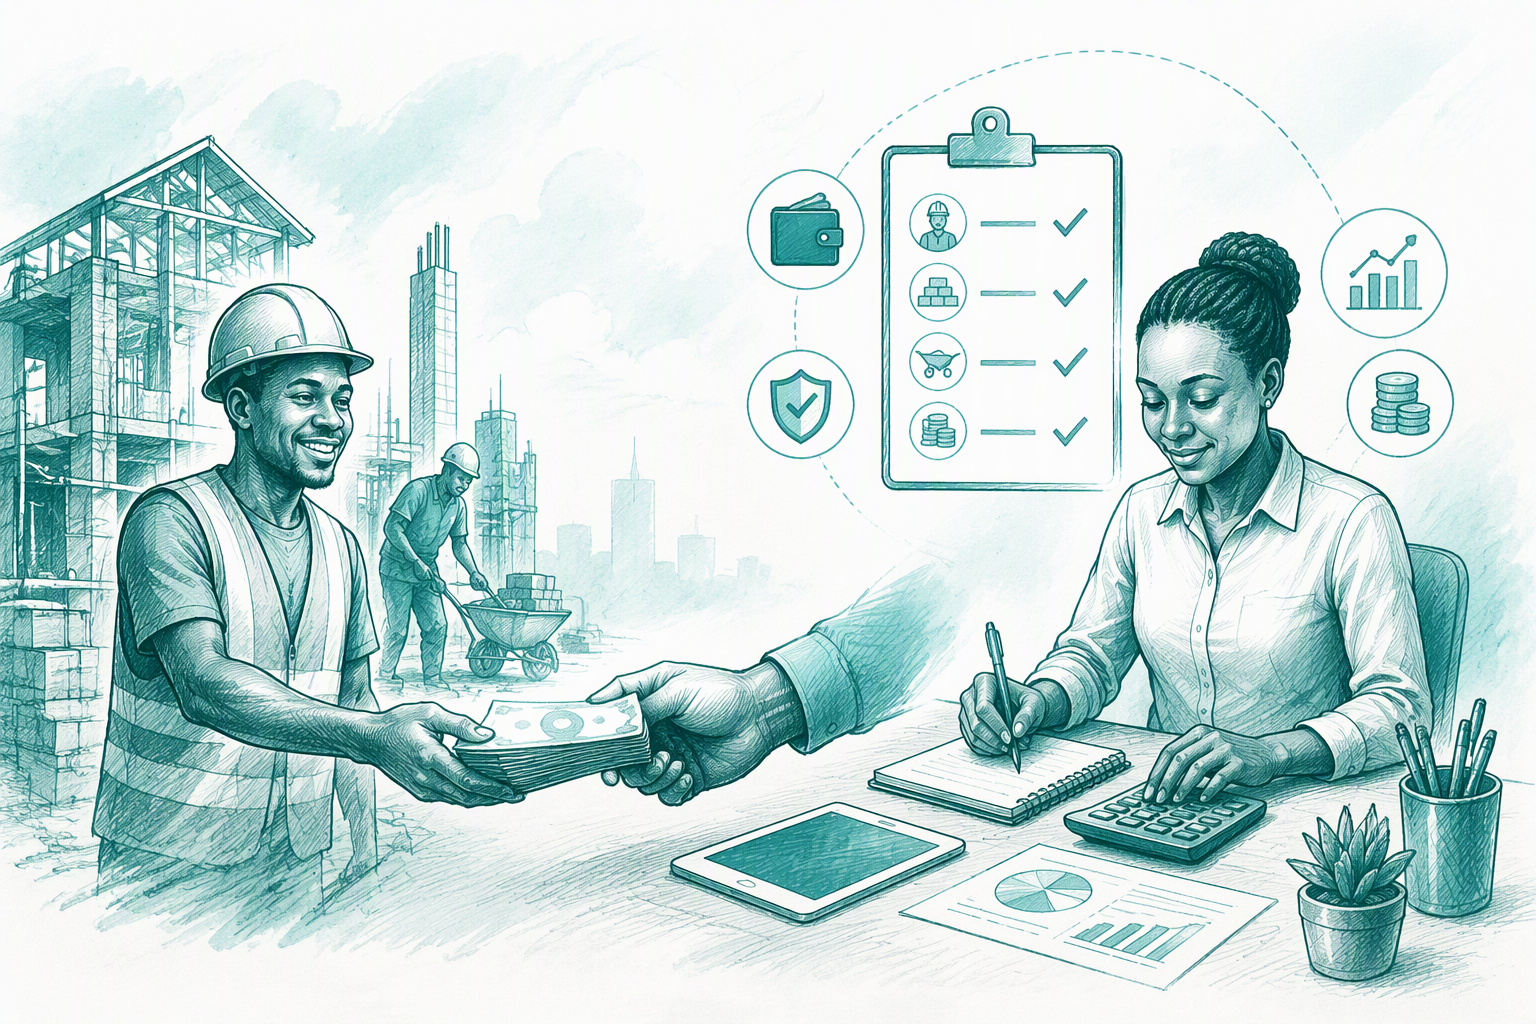
A provider may mark a payment complete while the contractor is still waiting for funds. The delay could sit with the sender, an intermediary, a compliance review, or the receiving institution.
Our approach is practical: calculate, document, and reconcile what the contractor receives. Track these figures separately:
- Invoice amount: The contractor’s billed gross fee.
- Amount funded: What the company provides to the payment service.
- Amount sent: What leaves the sender after upfront charges.
- Amount settled: What the receiving institution processes.
- Amount received: What is ultimately credited to the contractor.
A “USD payment” could refer to USD pricing, funding, transfer, or receipt. Those are different outcomes.
We assess the effective cost across sender fees, intermediary deductions, recipient fees, FX costs, and operational work. That work can include tracing delayed payouts, correcting rejected transfers, resolving duplicates, and reconciling records. Our guide to paying international contractors covers the wider cross-border workflow.
Sent amount versus received amount
A completed status only confirms that a provider processed its part of the transaction. It does not necessarily show the final currency or credited amount.
Keep the sender’s receipt, then confirm the settlement result through provider data or contractor confirmation. That final figure determines whether the invoice has been fully paid.
Decide who bears each payment cost
Payment terms usually take one of these forms:
- Sender pays: The company aims to cover the charges.
- Recipient pays: Charges reduce the contractor’s proceeds.
- Shared fees: Each party covers specified costs.
Intermediary deductions may still be difficult to predict. We recommend stating whether the invoice is a gross obligation or whether the contractor must receive a fixed net amount.
Can you pay freelancers in Kenya in USD? Three settlement scenarios
USD pricing and payment may be available, depending on the receiving account, payout rail, conversion process, and financial-institution checks.
Before the first payment, confirm:
- The account currency and owner
- Whether the account accepts international transfers
- The required bank and routing details
- Potential incoming-transfer charges
- Whether the payment will remain in USD or convert to KES
USD sent to a Kenyan USD account
A USD-denominated account may allow a contractor to retain dollars rather than converting immediately. It does not remove the possibility of sender fees, intermediary deductions, recipient charges, or compliance reviews.
International wires may pass through intermediary banks. As a result, the landed amount may be unclear when the payer approves the transfer.
USD sent to a KES bank account
Funds sent to a KES account must be converted somewhere in the payment chain. Establish whether the sender’s provider, an intermediary, or the recipient bank controls that conversion.
We recommend comparing the quoted customer rate with a neutral reference rate from the same time. This helps reveal the FX cost hidden beyond the advertised transfer fee.
USD-funded mobile-money payout
A mobile-money payout funded in USD may be converted and delivered in KES. Describe it as a local-currency payout unless the provider confirms otherwise.
Check current transaction limits, wallet restrictions, name matching, phone details, conversion terms, reversal procedures, and available payment evidence.
USD or KES pricing: choose the contract currency before the payment rail
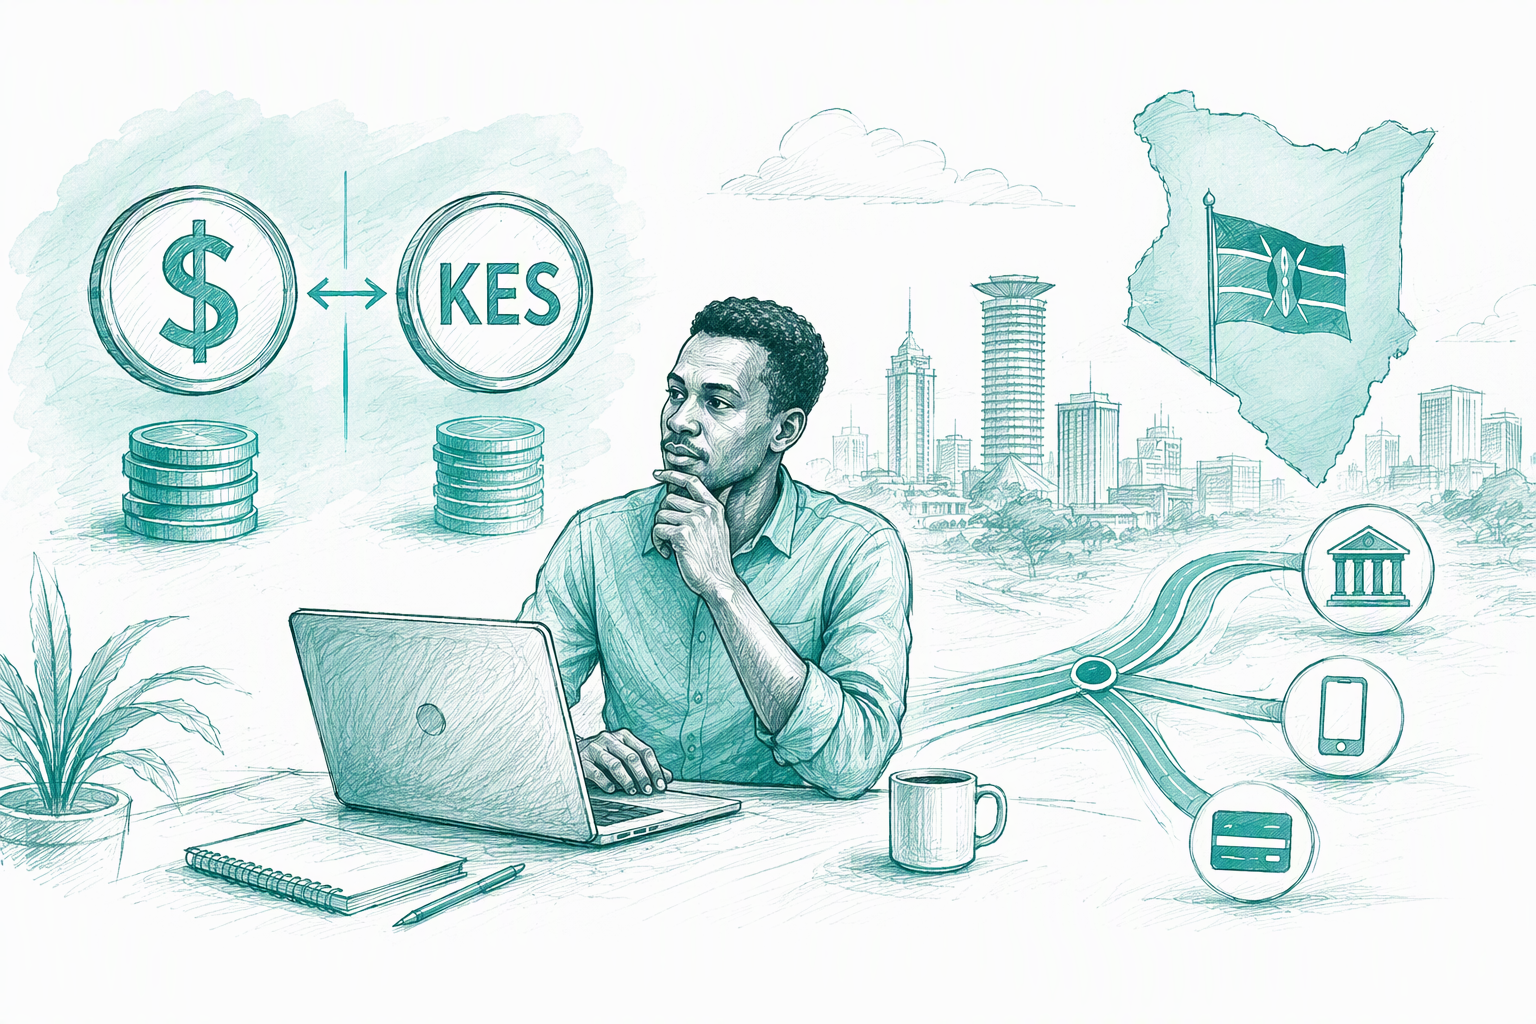
Contract currency determines how the work is priced. Settlement currency determines how the contractor receives the payment.
USD pricing can shift some currency risk away from the contractor, although fees and conversion costs may still reduce take-home pay. KES pricing fixes the local-currency fee while placing more exchange-rate risk on the payer.
For cross-currency arrangements, document:
- The exchange-rate source and timestamp
- Who performs the conversion
- Any disclosed spread or markup
- The rounding rule
- Who bears transfer and recipient fees
Calculate the effective FX cost
A low transfer fee does not prove that a payment is inexpensive. The provider may also earn money through the exchange rate.
We compare the amount funded with the final KES payout and a neutral rate from the same period. This shows the combined effect of fees and FX pricing without relying on the advertised fee alone.
Gross invoice versus guaranteed net receipt
With a gross invoice, payment charges may reduce the contractor’s proceeds unless the agreement says otherwise. A guaranteed net receipt requires the payer to cover or reimburse relevant costs.
Because intermediary deductions can be uncertain, we recommend defining how shortfalls will be handled rather than promising an outcome the payment rail cannot guarantee.
Compare Kenyan contractor payout rails by landed cost and control
The right rail depends on invoice value, urgency, receiving currency, account type, and required reconciliation evidence.
| Payout rail | Receiving currency | Fee and FX visibility | Main control issue | Reconciliation data |
|---|---|---|---|---|
| International bank wire | USD or KES | Intermediary costs may be unclear | Reviews, deductions, and tracing | Strong sender record; landed amount may need confirmation |
| Local KES bank payout | KES | Often clearer when quoted upfront | Account validation and returns | Usually includes provider and bank references |
| Mobile-money payout | Usually KES | Conversion terms require review | Wallet, identity, limit, and reversal rules | Evidence varies by provider |
For large or recurring payouts, we recommend using account verification or a small validation payment where appropriate.
International wire to a Kenyan bank
International wires may suit cases where USD receipt or conventional bank documentation matters. Correspondent routing and recipient-side deductions can weaken cost certainty.
Ask whether the chosen fee instruction guarantees the net amount. It may not control charges applied elsewhere in the banking chain.
Local KES bank payout
A local KES payout can work well when the contractor wants spendable local currency and the payer can inspect the conversion before approval.
Confirm whether the quoted payout is fixed or only estimated. The distinction matters when reconciling the invoice.
Mobile-money payout
Mobile money may provide convenient access to KES for contractors with compatible registered wallets. Check current limits, exact identity matching, reversal procedures, and downloadable payment evidence. A screenshot alone may not support a full audit trail.
Kenyan withholding tax: determine whether the payer must deduct before sending funds
There is no universal withholding answer for every Kenyan contractor payment. Treatment can depend on the payer, payee, service, contract, work location, tax status, and the company’s connection to Kenya.
We separate two questions:
- Must the payer deduct and remit Kenyan tax?
- How must the contractor handle their own reporting and tax obligations?
Identify the legal payer, classify the service and payee, establish where the work occurs, and check current Kenyan rules and any relevant treaty. Do not deduct tax solely because the contractor lives in Kenya, but do not assume an offshore payer can never have local obligations.
Evidence to collect before the first payment
Collect the contractor’s legal name, address, tax information where appropriate, invoice, service description, work location, and proof that the receiving account belongs to the contracting party.
Keep a written conclusion on withholding treatment, supported by a qualified adviser where necessary.
If withholding is required
Record the gross fee, deduction basis, amount withheld, net payment, remittance date, and supporting certificate or receipt where required.
Treat the invoice, tax remittance, and contractor payout as one transaction set. This prevents a valid tax deduction from appearing as an unexplained underpayment.
Build a reconciliation record for every Kenyan contractor payment
A reliable audit trail connects the agreement, approved work, invoice, exchange rate, fees, payout, and receipt confirmation.
Preserve:
- Contractor and invoice IDs
- Service period
- Gross amount and invoice currency
- Settlement currency
- Reference and applied FX rates
- Sender and deducted fees
- Payout reference and date
- Settlement status
- Confirmed received amount
When evaluating Shor’s international payroll platform, we recommend looking beyond transfer initiation. Our platform can bring agreements, invoices, approvals, exchange-rate information, payout records, and statuses into one workflow.
Records for batch contractor payouts
For batch payments, retain a ledger entry for each contractor rather than recording only the total.
Every payout should map to an invoice. If invoices are combined or split across transfers, document the allocation clearly.
Confirm the amount received
Use provider settlement data where available. If recipient-side deductions are not visible, ask the contractor to confirm the credited amount and currency.
Tracking repeated shortfalls helps us evaluate whether to change rails, revise payment terms, or cover predictable costs.
Before you hire a contractor in Kenya, test the real working relationship
A contractor agreement does not settle worker classification on its own. The practical relationship also matters.
Review control over hours and methods, supervision, exclusivity, integration into operations, financial risk, equipment, benefits, continuity, and economic dependence.
Where the facts look more like employment, pause and assess direct employment or an employer-of-record structure.
Clauses that support a genuine contractor relationship
The agreement should cover deliverables, acceptance criteria, payment, control over methods, confidentiality, data protection, intellectual property, termination, disputes, and tax responsibilities.
The working arrangement must remain consistent with those terms.
First-payment onboarding checks
Verify identity, contracting-party details, invoice information, account or wallet ownership, authority to provide the services, and sanctions status where applicable.
Only collect sensitive documents with suitable access, security, and retention controls.
When repeated Kenyan hiring requires a bigger compliance decision
A genuine independent contractor does not automatically require a Kenyan entity. The answer depends on local activities and the wider operating model.
Warning signs can include contract-signing authority, revenue-generating sales work, a fixed business location, dependent-agent activity, or a growing locally managed team.
Possible paths include continuing with genuine contractors, using an EOR for employment-like roles, or assessing Kenyan entity and payroll setup. An international employer cost calculator can help compare the financial shape of employment.
When an employer-of-record structure may be safer
An EOR may be more suitable when a role requires fixed hours, ongoing supervision, benefits, close management, or deep integration into regular operations.
It can support employment administration without an immediate local entity, although separate corporate-tax questions may still require advice.
When to request Kenyan legal or tax advice
Seek advice before giving local personnel authority to sign contracts, establishing a fixed location, building a recurring team, or assigning core sales functions.
Reassess when the facts change. Advice for one independent consultant may not apply to a managed local team.
Control your next Kenyan contractor payment
Model the net receipt, confirm compliance treatment, and keep every approval and payout record together. Use Shor to manage international contractor payments through one coordinated workflow.
FAQ
Can a foreign company pay a Kenyan contractor in USD?
Potentially. Confirm that the receiving account accepts USD transfers and review possible intermediary, recipient, and compliance requirements. USD invoicing does not guarantee USD receipt.
What is the cheapest way to pay contractors in Kenya?
There is no universally cheapest method. Compare the final amount received after fees, FX costs, deductions, failed-payment handling, and reconciliation work.
Does a foreign company have to withhold Kenyan tax?
Not automatically. The answer depends on the payer’s status, Kenyan presence, service, payee, work location, current rules, and any applicable treaty.
Is a Kenyan contractor agreement enough to prevent employee classification?
No. The written agreement matters, but actual control, supervision, exclusivity, integration, and financial independence also affect classification.
Can contractors receive USD through mobile money in Kenya?
A USD-funded mobile-money payment may be converted into KES. Confirm the delivered currency, exchange rate, limits, identity requirements, and payout evidence with the provider.