TL;DR
Smart goals objectives turn broad ambitions into measurable work. A goal describes the destination; a SMART objective defines the result, scope, owner, deadline, and safeguards needed to move towards it. We recommend choosing one primary outcome, setting clear quality and compliance guardrails, and reviewing progress often enough to catch risks before they affect workers or customers.
Table of contents
- Smart goals objectives: what they mean and why the difference matters
- The five SMART criteria: specific, measurable, achievable, relevant, and time-bound
- How to write a SMART objective: formula, baseline, owner, deadline, and guardrail
- Five SMART goals examples for work
- SMART payroll objectives for accuracy, timeliness, compliance, and cost
- International payroll and hiring objectives across countries
- Industry-specific SMART objectives for staffing, data labeling, and property management
- How to measure SMART objectives without drowning in KPIs
- Keep SMART goals active with regular reviews and checkpoints
- FAQ
- Turn global payroll goals into controlled execution
Smart goals objectives: what they mean and why the difference matters
“Improve payroll accuracy” is not yet an objective. It has no baseline, target, owner, scope, or deadline.
A goal is the destination. “Build reliable global payroll” is a goal. A SMART objective is a defined result that advances it, such as reducing preventable payroll errors by an agreed deadline while protecting on-time payments.
Separating goals from objectives prevents teams from treating broad ambitions as executable plans. It also exposes trade-offs. Faster processing should not cause incorrect deductions, late payments, or rushed reviews.
Legal compliance is different from performance improvement. Correct classification, registrations, statutory benefits, filings, and tax deadlines are operating requirements, not bonus achievements.
SMART goals versus SMART objectives
One strategic goal can contain several SMART objectives. A global payroll reliability goal might cover:
- Preventable error rates
- On-time worker payments
- Correction times
- Processing cost per active worker
- Country-launch readiness
Teams often use “SMART goal” and “SMART objective” interchangeably. That is rarely a problem in casual discussion, but precision matters when assigning ownership, approving budgets, building reports, and evaluating progress.
Why vague business goals fail
“Improve payroll,” “hire faster,” and “reduce vacancies” provide no definition of success. They also fail to identify who owns the result or which shortcuts are unacceptable.
That ambiguity creates competing priorities and hidden costs. Recruiting may reduce hiring time by exceeding its budget. Payroll may lower processing costs while corrections increase. Property teams may reduce vacancies by cutting necessary preparation work.
The five SMART criteria: specific, measurable, achievable, relevant, and time-bound
SMART stands for specific, measurable, achievable, relevant, and time-bound. We treat these criteria as practical tests rather than a writing exercise.
An objective to reduce preventable payroll errors, for example, should define the affected workforce, measurement method, target, deadline, and payment safeguards.
- Specific: It identifies the process, scope, owner, and intended result.
- Measurable: It uses a consistent formula and reliable data source.
- Achievable: It reflects available resources, capacity, and constraints.
- Relevant: It supports a meaningful business goal.
- Time-bound: It includes a deadline and appropriate checkpoints.
Measurable does not mean tracking everything. Too many metrics make it harder to see what needs attention.
Specific and measurable
Define the process, affected group, metric, data source, and unit. For payroll, explain whether “error rate” refers to incorrect payslips, affected workers, transactions, or material errors requiring correction.
Useful measures include rates, medians, counts, service levels, and normalized costs. Keep the formula consistent across reporting periods, particularly when comparing several countries or currencies.
Achievable and relevant
Achievable should not mean effortless. Compare the target with previous performance, approved budgets, staffing, system capacity, payroll calendars, and external dependencies.
A demanding target can still be credible when the operating plan supports it. We recommend guardrails for legal readiness, work quality, team capacity, and worker impact so the headline result cannot be achieved through harmful shortcuts.
Time-bound
Set a final deadline and interim checkpoints. Payroll teams may need more frequent checks as a cutoff approaches, while longer projects can use a broader review cadence.
International work also depends on registrations, implementation lead times, statutory calendars, funding windows, and start dates. Our guide to how long EOR onboarding takes can help teams avoid deadlines that ignore essential setup work.
How to write a SMART objective: formula, baseline, owner, deadline, and guardrail
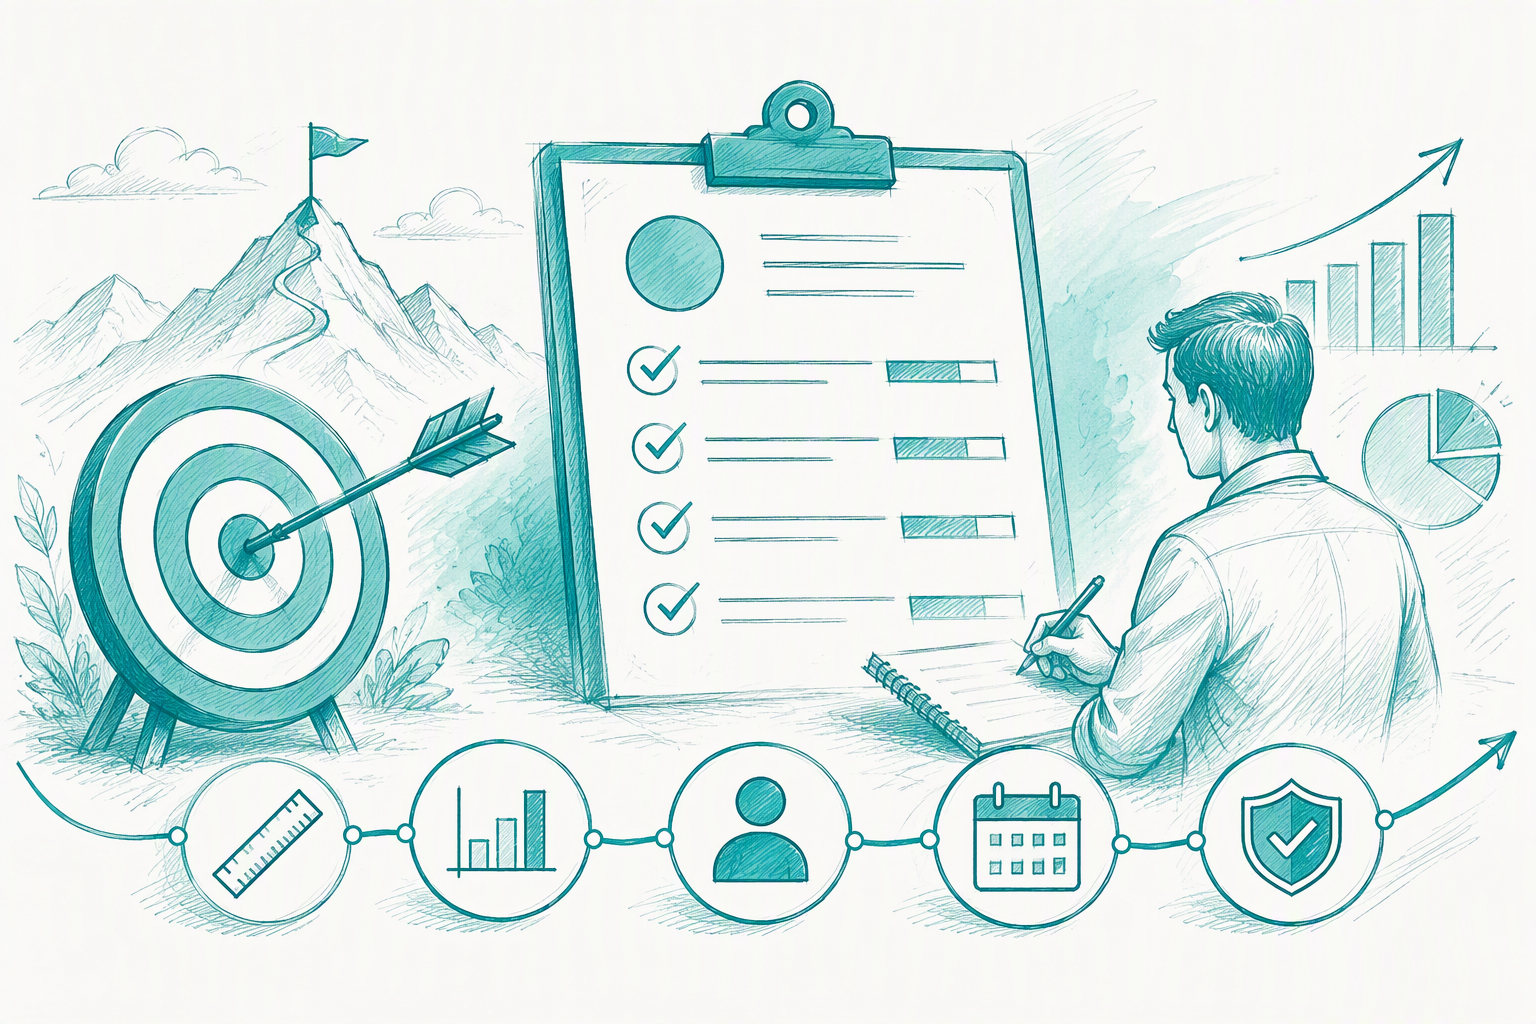
Use this formula:
By [deadline], [owner] will move [metric] from [baseline] to [target] for [scope] through [actions], while maintaining [guardrails].
Choose one primary outcome. Add only the guardrails needed to expose likely side effects.
An objective card should include:
- Goal: The broader business destination
- Metric definition: Formula, inclusions, and exclusions
- Baseline and target: Current performance and intended result
- Owner: One accountable decision-maker
- Contributors: Teams controlling important inputs
- Deadline and checkpoints: Final date and review cadence
- Data source: The system or record used for reporting
- Budget: Approved spending and capacity
- Dependencies: Vendors, registrations, data, or approvals
- Escalation trigger: The condition requiring intervention
Rewrite a vague goal in five steps
Turn “improve payroll” into an objective by:
- Defining a preventable payroll error.
- Calculating the current error rate.
- Agreeing on a credible target and deadline.
- Naming an accountable owner.
- Adding payment and correction guardrails.
The result might be: “Reduce the preventable payroll error rate from its current baseline to the approved target by the agreed deadline, while protecting on-time payments and resolving material corrections within the service level.”
For “hire faster,” define when the clock starts and stops, identify the owner, and protect budget and retention. Otherwise, the team may improve speed without improving hiring outcomes.
Test whether the target is ambitious but credible
Compare the target with recent performance and known constraints. Record which people, software, integrations, budget, or workflow changes will support the improvement.
Reject targets that depend on unapproved resources. International hiring objectives must also account for engagement models, registrations, contracts, worker data, and payroll setup. Our country guides can help teams identify local dependencies.
Add guardrails before approving the objective
Relevant guardrails may cover:
- Payment timeliness and payroll accuracy
- Work quality and rework
- Overtime and team capacity
- Worker or contractor retention
- Gross margin and approved budget
- Classification and compliance readiness
Define the response in advance. If the primary metric improves while a guardrail fails, pause the affected action, investigate, and require approval before continuing.
Five SMART goals examples for work
These illustrative examples cover finance, operations, people, readiness, and service. Each team should replace the placeholders with verified baselines and approved targets.
1. Reduce preventable payroll errors
Reduce preventable payroll errors from the verified baseline to an approved target by the deadline. Assign ownership to payroll operations, strengthen input validation, and protect on-time payments and correction service levels.
A blanket zero-error target can be counterproductive. Definitions vary, source data may be wrong, and unrealistic targets may discourage prompt reporting and correction.
2. Lower payroll processing cost safely
Reduce total payroll cost per active worker through verified process savings. Define whether the calculation includes software, bank fees, foreign exchange, internal labour, and corrections.
Accuracy and payment timeliness should remain guardrails. Teams can model country-specific employment spend with an international employer cost calculator before approving a target.
3. Shorten hiring and onboarding time
Reduce the median time from approved requisition to accepted offer by removing avoidable approval delays and reviewing the recruitment pipeline regularly.
For international hiring, measure acceptance-to-payroll-ready time separately. A quick offer provides little value if missing documents, classification questions, or registration work delay the start.
4. Improve staffing fill rate
Increase the fill rate for approved assignments by the agreed deadline while maintaining credential, overtime, margin, and retention standards.
Segment results by client, role, location, and urgency. A blended figure can hide persistent problems in smaller or higher-risk markets.
5. Improve tenant service operations
Meet defined response levels for maintenance requests by improving routing and vendor follow-up. Assign different service levels by priority and protect safety, documentation, budget, and resident communication.
Urgent safety issues should not compete with routine requests under one average resolution metric.
SMART payroll objectives for accuracy, timeliness, compliance, and cost
Strong payroll objectives cover accuracy, payment timeliness, correction speed, processing efficiency, and issue prevention. They distinguish controllable improvements from statutory duties that must always be completed.
Accuracy and correction objectives
Define key terms before reporting:
- Preventable error: An error the payroll process could reasonably have avoided
- Material error: A mistake exceeding an approved financial or worker-impact threshold
- Off-cycle correction: A payment processed outside the normal cycle
- Workers affected: Distinct workers whose expected pay changed because of an error
Track correction time with the error rate. Otherwise, a team may report fewer recorded errors while worker issues remain unresolved.
On-time payment objectives
Measure timeliness by whether workers receive the expected funds on the scheduled date, not merely when a bank file is submitted.
Missing time data, unresolved approvals, invalid bank details, funding problems, and late changes are useful warning signals. They should trigger action before cutoff.
Payroll cost-control objectives
State which costs are included so finance does not compare incompatible figures. Savings are only meaningful when accuracy and timeliness remain stable. Shifting work into unpaid overtime or unexpected worker deductions is not a genuine saving.
International payroll and hiring objectives across countries
Global objectives must reflect different currencies, pay frequencies, registrations, benefits, filings, and local cutoffs. Country-level reporting helps prevent strong performance in one market from concealing failures elsewhere.
Classification reviews, registrations, required benefits, and statutory filings are gates, not optional stretch goals.
Country-launch readiness objectives
A country-launch objective should cover payroll setup, registration workflows, worker-data validation, and filing calendars before the intended start date.
Track:
- Entity or engagement model
- Worker classification
- Registrations and contracts
- Worker and banking data
- Funding and payment rails
- Filing and payroll calendars
- Documented legal or tax review
Expansion should not continue while material legal or classification questions remain unresolved. The appropriate route may involve employment or contracting, so teams should understand how to pay international contractors before setting onboarding targets.
Multi-currency payment objectives
Measure whether each worker received the correct amount, on time, in the expected currency. Monitor failed payments, unexpected deductions, resolution times, and foreign-exchange variance against the approved method.
Segment reporting by country, currency, pay date, and payment rail. Headquarters totals can conceal worker-level failures.
Monthly compliance and cost checkpoints
We recommend reviewing upcoming filings, registration status, payroll inputs, funding, unresolved notices, and cost variance regularly, with more frequent checks near deadlines.
Shor’s international payroll platform gives founders a clearer operating view across countries while keeping local payment and compliance dependencies visible.
Industry-specific SMART objectives for staffing, data labeling, and property management
Different operating models need different measures. A generic productivity target can damage margins, quality, worker experience, or tenant service.
Staffing-firm objectives
Staffing firms may track time-to-fill, fill rate, redeployment, assignment completion, gross margin, and retention. Results should be segmented by client, role, location, and urgency.
Data-labeling workforce objectives
A useful objective can focus on increasing accepted labeling throughput by an approved deadline while maintaining quality, meeting the client service level, and paying contributors accurately.
Pair throughput with rework, turnaround time, and payment accuracy. Separate available task volume from worker-controlled productivity.
Property-management objectives
Property managers may set objectives for rent collection, vacancy, maintenance response, make-ready time, and contractor payment accuracy.
Cost targets must not bypass safety requirements, applicable notices, or tenant protections. Fast contractor payments should still require correct invoices and documented work.
How to measure SMART objectives without drowning in KPIs
We recommend one primary outcome, a limited set of guardrails, and only the leading indicators needed to support action. Define each formula, source, reporting frequency, and segment before launch.
Leading versus lagging indicators
Leading indicators reveal developing problems, such as missing payroll inputs, unresolved approvals, open shifts, aging candidates, or overdue work orders.
Lagging indicators show results, including on-time payment, payroll accuracy, fill rate, retention, vacancy, and rent collection. Leading indicators support intervention but do not replace outcomes.
Build a useful objective dashboard
Display the baseline, current result, target, trend, checkpoint status, and guardrail breaches. Use written threshold definitions rather than subjective status updates.
Segment data where aggregation could hide risk. Country, client, property, role, currency, and worker-type views often expose issues concealed by a company-wide average.
Assign shared ownership fairly
Give one person final accountability while documenting finance, HR, operations, legal, vendor, and local-partner dependencies.
Do not hold one employee responsible for a system-wide failure outside their authority. Payroll accuracy, onboarding, and staffing outcomes usually require shared execution.
Keep SMART goals active with regular reviews and checkpoints
SMART objectives should not disappear into an annual plan. We recommend a review cadence based on risk, deadlines, and operational complexity.
Each review should result in a decision: continue, revise, pause, or retire the objective.
A practical review cadence
Inspect urgent indicators and blocked dependencies frequently. Review costs, capacity, compliance readiness, and guardrails at scheduled checkpoints. At the end of each planning cycle, assess results and resource assumptions before setting the next target.
Monitoring should become more frequent as risk or a deadline approaches.
Rules for changing a target
Do not lower a target simply because progress is behind plan. First determine whether execution failed or the original assumptions became invalid.
Revision may be justified when the baseline was wrong, scope changed materially, legal requirements shifted, or necessary resources were not approved. Record the reason, approver, revised target, and effect on related objectives.
Close the objective properly
Document the final result, business impact, guardrail performance, and unresolved risks. Record which process changes produced the improvement.
Successful improvements should become standard operating controls rather than recycled objectives.
Turn global payroll goals into controlled execution
Choose one international payroll outcome, confirm its baseline, assign an owner, and define its deadline and guardrails. Then use Shor’s international payroll platform to manage country-level payment, cost, and compliance dependencies in one place.
FAQ
What are five SMART goals examples?
Examples include reducing payroll errors, lowering payroll costs safely, shortening hiring time, improving staffing fill rates, and meeting maintenance service levels. Each needs a verified baseline, approved target, owner, deadline, scope, and guardrails.
What makes an objective SMART?
A SMART objective is specific, measurable, achievable, relevant, and time-bound. It should also identify accountability and prevent damaging trade-offs.
What are good work goals?
Good work goals address a real operating constraint, such as unreliable payroll, slow onboarding, unfilled shifts, or overdue maintenance. The related objectives should reflect available resources and legal requirements.
Can SMART goals cover soft skills?
Yes, but soft skills often need observable behaviours and structured feedback rather than a simple output metric. For example, a communication objective could focus on completing agreed stakeholder check-ins and applying documented feedback.
Can a SMART objective still be a bad objective?
Yes. A measurable speed or cost target may satisfy the framework while increasing errors, legal exposure, overtime, churn, or poor customer outcomes. Relevant guardrails are essential.