TL;DR
The single touch payroll meaning is straightforward: Single Touch Payroll (STP) is Australia’s digital system for sending employee pay, PAYG withholding and super liability information to the Australian Taxation Office (ATO) as part of each pay cycle. It reports payroll data; it does not automatically transfer wages, tax or super. Employers still need to check the ATO response, pay each liability separately and finalise employee records after the income year.
Table of Contents
- Single touch payroll meaning for employers
- What information is sent to the ATO through STP?
- Who must be included in STP reporting?
- How an STP-enabled pay run works
- What STP does not pay automatically
- How to fix rejected, late or incorrect STP reports
- Why STP still requires end-of-year finalisation
- STP for overseas companies employing Australian staff
- STP records and employer responsibilities
- FAQ
- Run Australian payroll with the full compliance picture
Single touch payroll meaning for employers
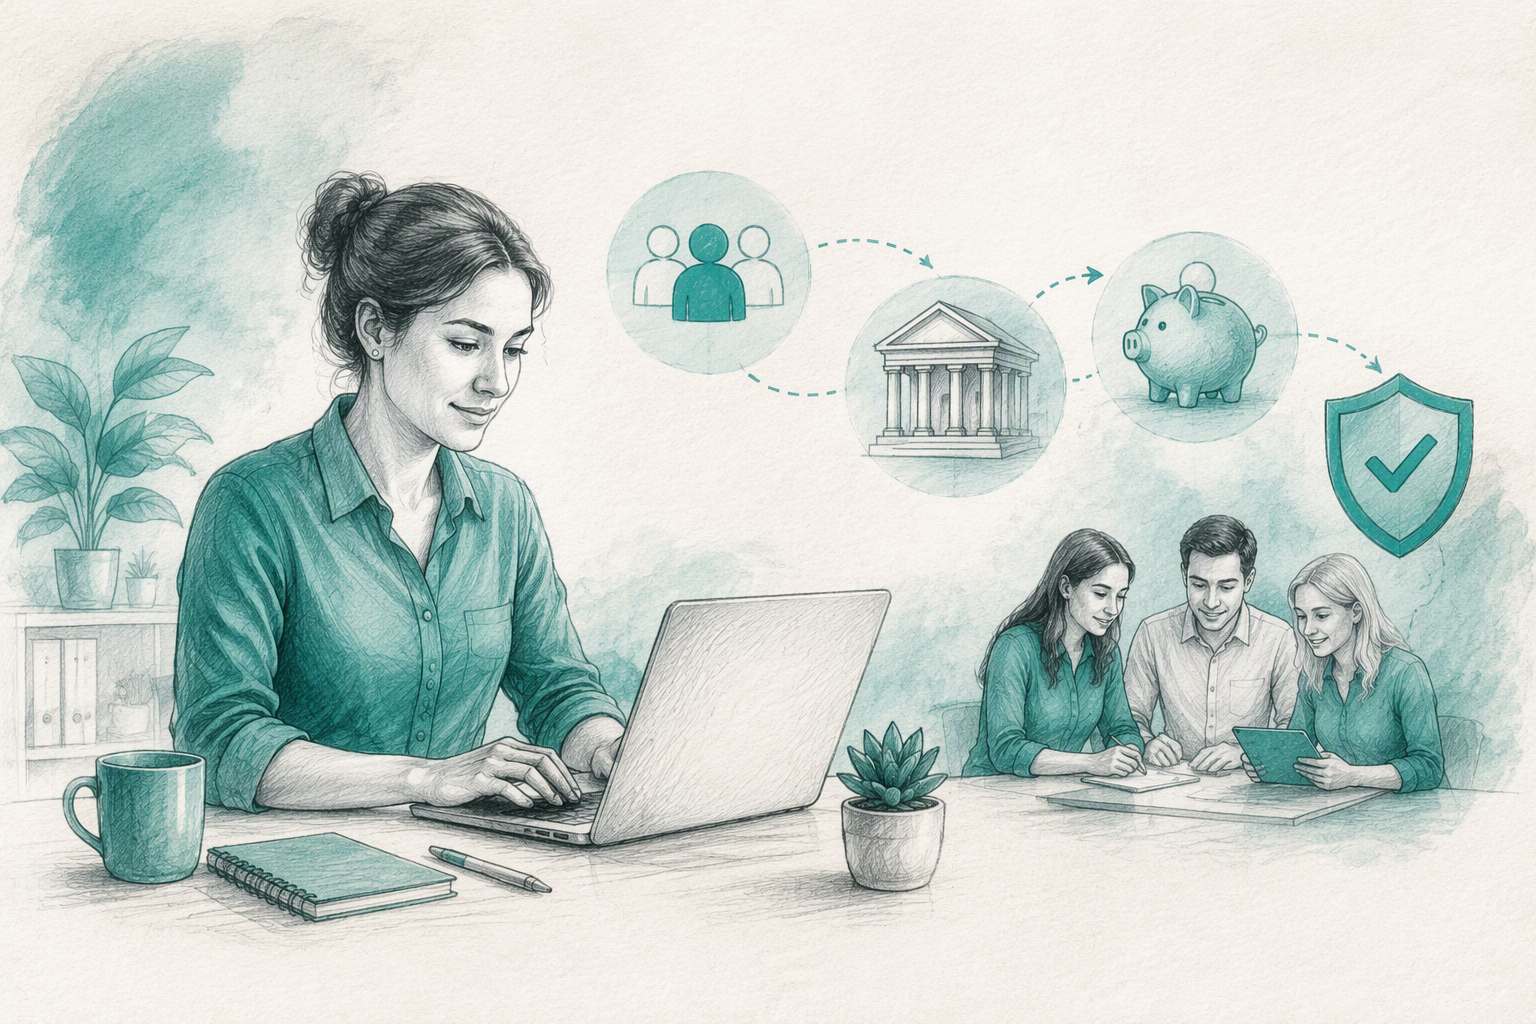
Single Touch Payroll is the electronic reporting of employee payroll information to the ATO through compatible payroll software or a sending service provider. Employers prepare and authorise the data, the software transmits it, and the ATO processes the report.
The phrase “single touch” refers to reporting being integrated with the pay cycle. It does not mean one transaction pays employees, the ATO and super funds simultaneously.
STP is also different from instant pay or earned-wage-access services. Those products affect when workers receive wages. STP records what the employer paid, withheld and became liable to contribute.
The short definition for employers
STP reports employee pay, PAYG withholding and relevant super information to the ATO each pay cycle. It replaced much of the previous annual payroll reporting process and gives employees access to updated income information through ATO online services linked to myGov.
What “single touch” does not mean
STP is not:
- A bank transfer for wages, PAYG withholding and super
- Proof that every payroll calculation is correct
- Confirmation that workers have been classified correctly
- Evidence that reported liabilities have been paid
- A replacement for employment and record-keeping obligations
An STP report may be accepted even if the employer has used an inaccurate income type or payment category.
What information is sent to the ATO through STP?
STP reports generally contain employee payment amounts, PAYG withholding and relevant super liability information. The information is commonly maintained as year-to-date values, with each report updating the employee’s record.
Core amounts reported each payday
Depending on the payroll and payment, a report may cover:
- Employee earnings
- PAYG withholding
- Super liability information
- Relevant employer super contribution fields
- Updated year-to-date totals
The report communicates payroll information. It does not send a super contribution to an employee’s fund.
Important STP Phase 2 fields
STP Phase 2 provides more detail about how and why an employee was paid. Fields may distinguish between income types, employment arrangements and payment components such as leave, allowances, overtime, bonuses, commissions, salary sacrifice and lump sums.
Correct setup matters. We recommend reviewing payroll categories rather than assuming the software will identify an incorrect classification.
Who must be included in STP reporting?
Employers generally report eligible employees through STP regardless of business size. The working relationship and applicable withholding rules determine the correct treatment—not the label used in a contract or the frequency of payment.
Employees, casuals and closely held payees
Permanent, part-time and casual employees may all need to be included. Casual status affects employment conditions and pay components, but it does not by itself remove someone from payroll reporting.
Closely held payees may also fall within STP. Different reporting arrangements can apply, so we recommend checking the current rules for the employer’s circumstances.
Contractors, labour-hire workers and voluntary agreements
A contractor who submits an invoice is not automatically an employee, but calling a worker a contractor does not settle their legal status either.
Employers may need to distinguish between:
- Genuine independent contractors
- Employees incorrectly described as contractors
- Workers supplied under labour-hire arrangements
- Contractors covered by voluntary PAYG withholding agreements
Classification affects more than STP. It can also influence withholding, super and employment obligations, so professional advice may be appropriate.
How an STP-enabled pay run works
A practical payroll workflow is:
- Maintain current worker, tax, super and employment records.
- Calculate earnings, deductions, withholding, super and net pay.
- Review and approve the pay run.
- Authorise employee payments.
- Transmit the STP report.
- Review the ATO response.
- Pay tax and super through their separate processes.
- Reconcile payroll, banking and liability records.
The payday workflow
Before processing payroll, check employee details, tax settings, super information and payment categories. After calculation, review unexpected amounts and confirm that deductions and salary-sacrifice items have been treated correctly.
We also recommend retaining submission receipts, response details and error messages. A completed pay run is not the same as a verified ATO submission.
Submitted, accepted and rejected reports
Status labels vary between platforms. A submitted or pending report may still be awaiting an ATO response. An accepted report has passed the ATO’s processing checks, while a rejected report generally requires review and correction.
Acceptance confirms processing, not the legal accuracy of every amount or employment arrangement.
What STP does not pay automatically
Reporting an amount is different from transferring money. An employer can have an accepted STP report while wages, withholding or super remain unpaid.
Reporting versus remitting PAYG withholding
An STP report tells the ATO how much PAYG withholding was recorded through payroll. The employer must still remit the amount through the relevant ATO payment and activity-statement process.
Payroll records, STP reports and ATO accounts should reconcile, but they represent separate steps.
Reporting versus paying super
STP may report the super liability generated by payroll. The employer must still send the contribution through an appropriate payment process and deal with any rejected, refunded or unmatched contributions.
A successful STP submission does not correct a missing or late super payment.
How to fix rejected, late or incorrect STP reports
Start by identifying whether the problem relates to transmission, payroll data or worker classification. Repeatedly sending unchanged information will not resolve an error in the source records.
Payroll event versus update event
A payroll event reports information connected with a payment. An update event adjusts employee year-to-date information without recording another payment.
Depending on the error and payroll product, an employer may correct the information through a later pay event, an update event or another supported correction process. Keep a record of what changed and which submission corrected it.
An accepted report can still be inaccurate
A report can pass processing checks while containing an incorrect employment basis, income type or payment component. We recommend reconciling STP totals against:
- Payroll registers
- Employee payments
- PAYG withholding liabilities
- Super liabilities and contributions
- Accounting balances
- Employment records and worker classifications
Why STP still requires end-of-year finalisation
Pay-cycle reports build each employee’s year-to-date record. Finalisation tells the ATO that the employer considers the information for the income year complete and correct.
The pre-finalisation checklist
Before finalising, employers should:
- Reconcile pay, withholding and super liability totals
- Check employee identity and tax information
- Review income types and tax treatments
- Confirm cessation details where relevant
- Correct duplicate, missing or misclassified payments
- Resolve rejected reports
- Verify year-to-date balances
We recommend confirming that the ATO accepted the finalisation rather than treating submission as the last step.
What employees see in myGov
Employees generally access an income statement through ATO online services linked to myGov instead of receiving a traditional payment summary. Before finalisation, the statement may not be marked as tax ready. Once finalisation has been accepted, its status should update accordingly.
STP for overseas companies employing Australian staff
STP is one part of Australian payroll compliance, not a complete employment solution. An overseas company may need to consider direct employment, an Australian subsidiary or another lawful arrangement.
Our comparison of an EOR versus a foreign subsidiary explains how control, cost and compliance considerations can change as an Australian team grows.
What an international employer must decide before the first pay run
Key questions include:
- Which entity is the legal employer?
- Which Australian registrations are required?
- Is the worker an employee or contractor?
- How will wages, withholding and super be managed?
- Which employment, insurance and record-keeping rules apply?
- Are state or territory obligations relevant?
An Employer of Record may be suitable in some circumstances, but it should not replace appropriate legal and tax analysis.
STP is evidence of reporting, not complete compliance
An accepted report does not prove that wages and super were paid or that every surrounding employment obligation was met. We recommend reconciling STP acceptance with bank payments, tax remittances, super contributions and local employment records.
STP records and employer responsibilities
Keep enough evidence to reconstruct each pay run, submission and correction. That may include payroll calculations, employee declarations, STP receipts, ATO responses, bank records, super payment evidence and reconciliations.
Retention requirements can vary by record type and applicable law. Employers should check current ATO, Fair Work, super, workers’ compensation and payroll tax requirements rather than relying on one retention period for every document.
Run Australian payroll with the full compliance picture
Connect STP reporting with accurate classifications, completed payments and reliable records. Talk to Shor about building a practical Australian payroll process for your international team.
FAQ
How does payroll work with STP?
Employers calculate and approve payroll, pay employees, submit the STP information and review the ATO response. PAYG withholding and super are then paid through separate processes, followed by reconciliation.
What is STP in the workplace?
STP is the employer’s digital reporting channel to the ATO for employee pay, PAYG withholding and relevant super information. It does not determine employment rights or automatically transfer liabilities.
Does STP pay employee super?
No. STP reports relevant super liability information. The employer must still send contributions to the appropriate fund through a separate payment process.
How do I finalise STP in QuickBooks or another platform?
First reconcile annual payroll totals and correct employee records. Then create and submit the platform’s STP finalisation declaration and confirm ATO acceptance. Use the product’s current documentation for exact menu names.
Is instant pay the same as Single Touch Payroll?
No. Instant pay affects when workers receive earnings. STP concerns payroll reporting to the ATO. Using instant pay does not remove withholding, super, reporting or record-keeping obligations.