TL;DR
A subsidiary is a separate legal company controlled by a parent company. Businesses often use subsidiaries to enter markets, manage specific operations, hold assets, sign contracts, and hire locally. Incorporation alone, however, does not solve payroll, tax, licensing, governance, or liability issues. We recommend comparing the subsidiary’s full setup, operating, and closure costs with other lawful structures before committing.
Table of Contents
- TL;DR
- Table of Contents
- What is a subsidiary? A plain-English definition
- How parent companies own and control subsidiaries
- Subsidiary vs branch, division, affiliate, and other structures
- Does a subsidiary protect the parent company?
- Using a local subsidiary to hire and run international payroll
- The real cost and timeline of forming a subsidiary
- Subsidiary tax, accounting, funding, and reporting obligations
- When does a subsidiary make sense for international expansion?
- Subsidiary FAQ and quick glossary
- FAQ
- Plan international hiring beyond incorporation
What is a subsidiary? A plain-English definition
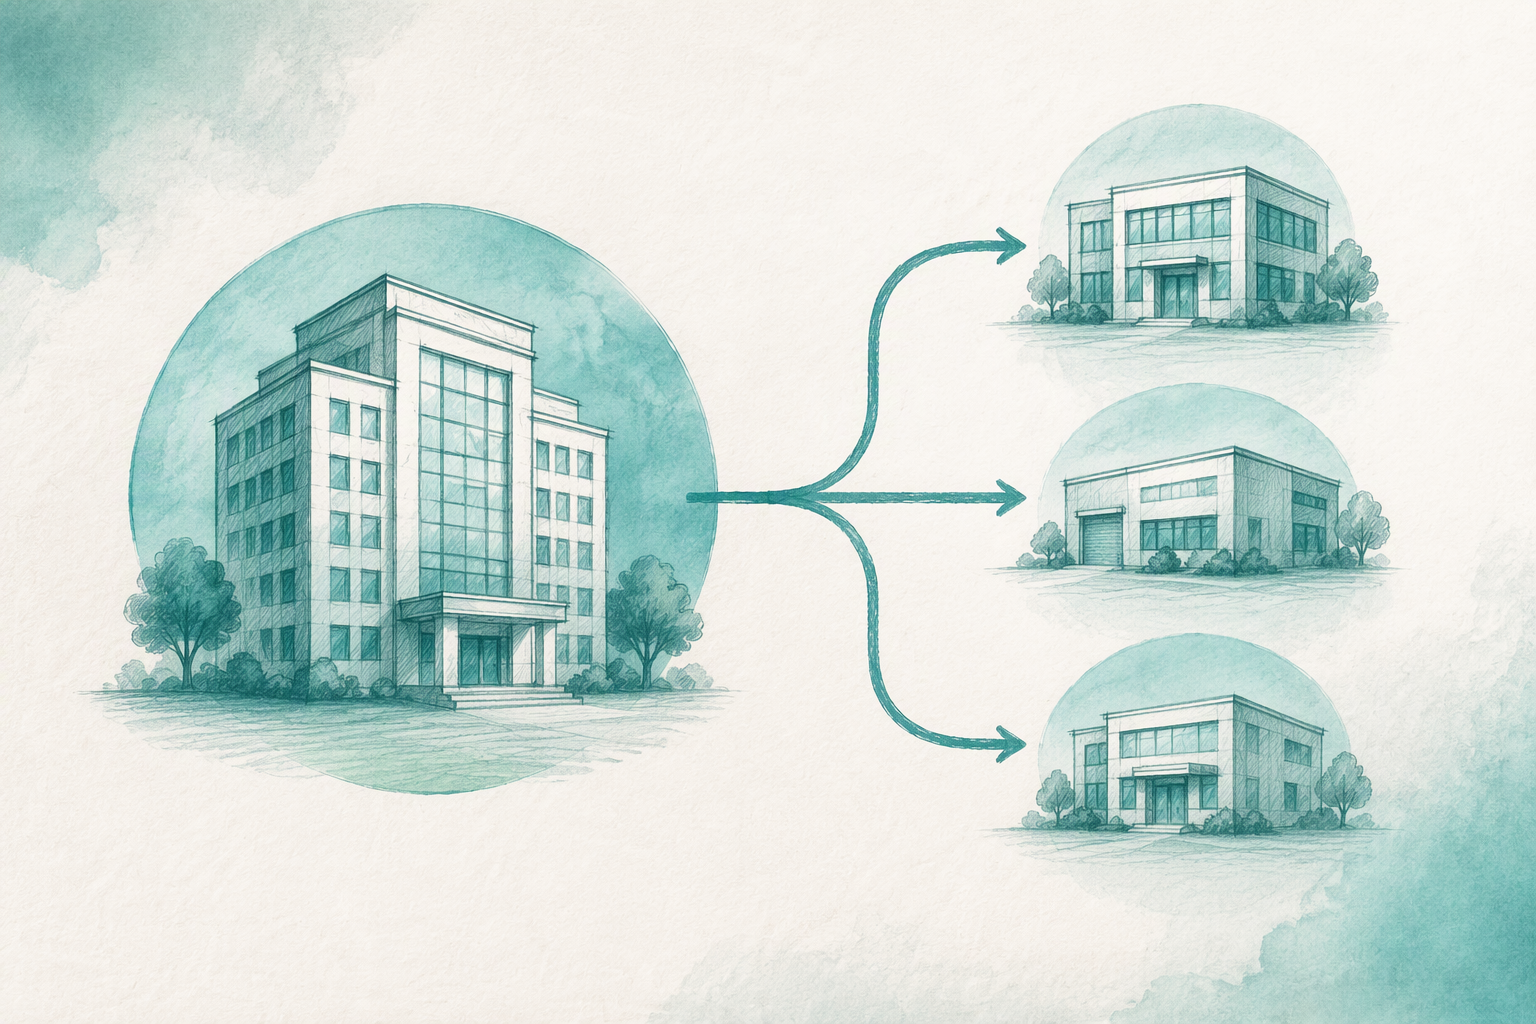
A subsidiary is a separate company controlled by another entity, called its parent or holding company. The parent may exercise control through ownership, voting rights, board appointment powers, contracts, or a combination of these mechanisms.
As a distinct legal entity, a subsidiary can generally sign contracts, own assets, hire employees, borrow money, incur debt, sue, and be sued in its own name, subject to local law. Its parent can influence its policies, management, and operations without turning the two companies into one legal person.
The precise meaning of “control” depends on the context. Corporate statutes, accounting standards, tax rules, employment laws, and individual contracts may apply different tests.
A basic ownership structure looks like this:
Parent Company
      |
      v
  Subsidiary
The parent controls the company, but the subsidiary retains its own local obligations. That distinction helps identify the correct contracting party, employer, taxpayer, borrower, or regulated business.
A simple subsidiary example
Suppose a US software company owns a UK company. The UK subsidiary signs local employment agreements, runs UK payroll, files required returns, and enters customer or supplier contracts in its own name.
The US parent may still manage group strategy and consolidated reporting. The UK subsidiary, however, remains the local legal employer and must meet the employment, tax, pension, benefits, and reporting requirements that apply to it.
A payroll platform can support calculations, payslips, deductions, and reporting workflows. It does not replace the legal employer or remove that employer’s statutory responsibilities.
Direct and indirect subsidiaries
A direct subsidiary is owned or controlled directly by its parent. An indirect subsidiary sits farther down the ownership chain:
Parent Company
      |
      v
  Company A
      |
      v
  Company B
Company B is a direct subsidiary of Company A and an indirect subsidiary of the parent. This distinction can affect governance, ownership disclosures, financial reporting, intercompany agreements, and tax analysis.
How parent companies own and control subsidiaries
Equity ownership is only one form of control. Other mechanisms may include:
- Voting rights
- Rights to appoint or remove directors
- Contractual control
- Veto rights over reserved decisions
- Financing arrangements
- Shareholder agreement rights
Majority voting control commonly creates a parent-subsidiary relationship, but an ownership percentage may not settle every legal or accounting question.
A parent may set group strategy, budgets, risk standards, and reporting requirements. The subsidiary’s directors must still perform their local duties and follow applicable approval, recordkeeping, meeting, and filing rules.
Wholly owned versus partially owned subsidiaries
A wholly owned subsidiary has all its equity held by one parent or corporate group. This may simplify shareholder decisions, but it does not erase the subsidiary’s separate identity.
A partially owned subsidiary has minority shareholders. Those shareholders may have information, consent, board nomination, dividend, or exit rights. We recommend checking the constitutional documents and shareholder agreement rather than assuming that a majority owner can act without restriction.
Subsidiary, joint venture, sister company, and holding company
A joint venture usually involves shared ownership or governance between multiple parties. Whether it also qualifies as a subsidiary depends on who controls it and which legal or accounting rules apply.
Sister companies are subsidiaries controlled by the same parent. A holding company, meanwhile, exists primarily to own interests in other companies and may have few operations of its own.
Legal control versus financial consolidation
A corporate group may include a subsidiary’s results in consolidated financial statements. That accounting treatment does not merge the companies into one legal person.
Accounting definitions of control may also differ from corporate-law tests. Finance and legal teams should align consolidation decisions with ownership records, local books, and statutory reporting.
Subsidiary vs branch, division, affiliate, and other structures
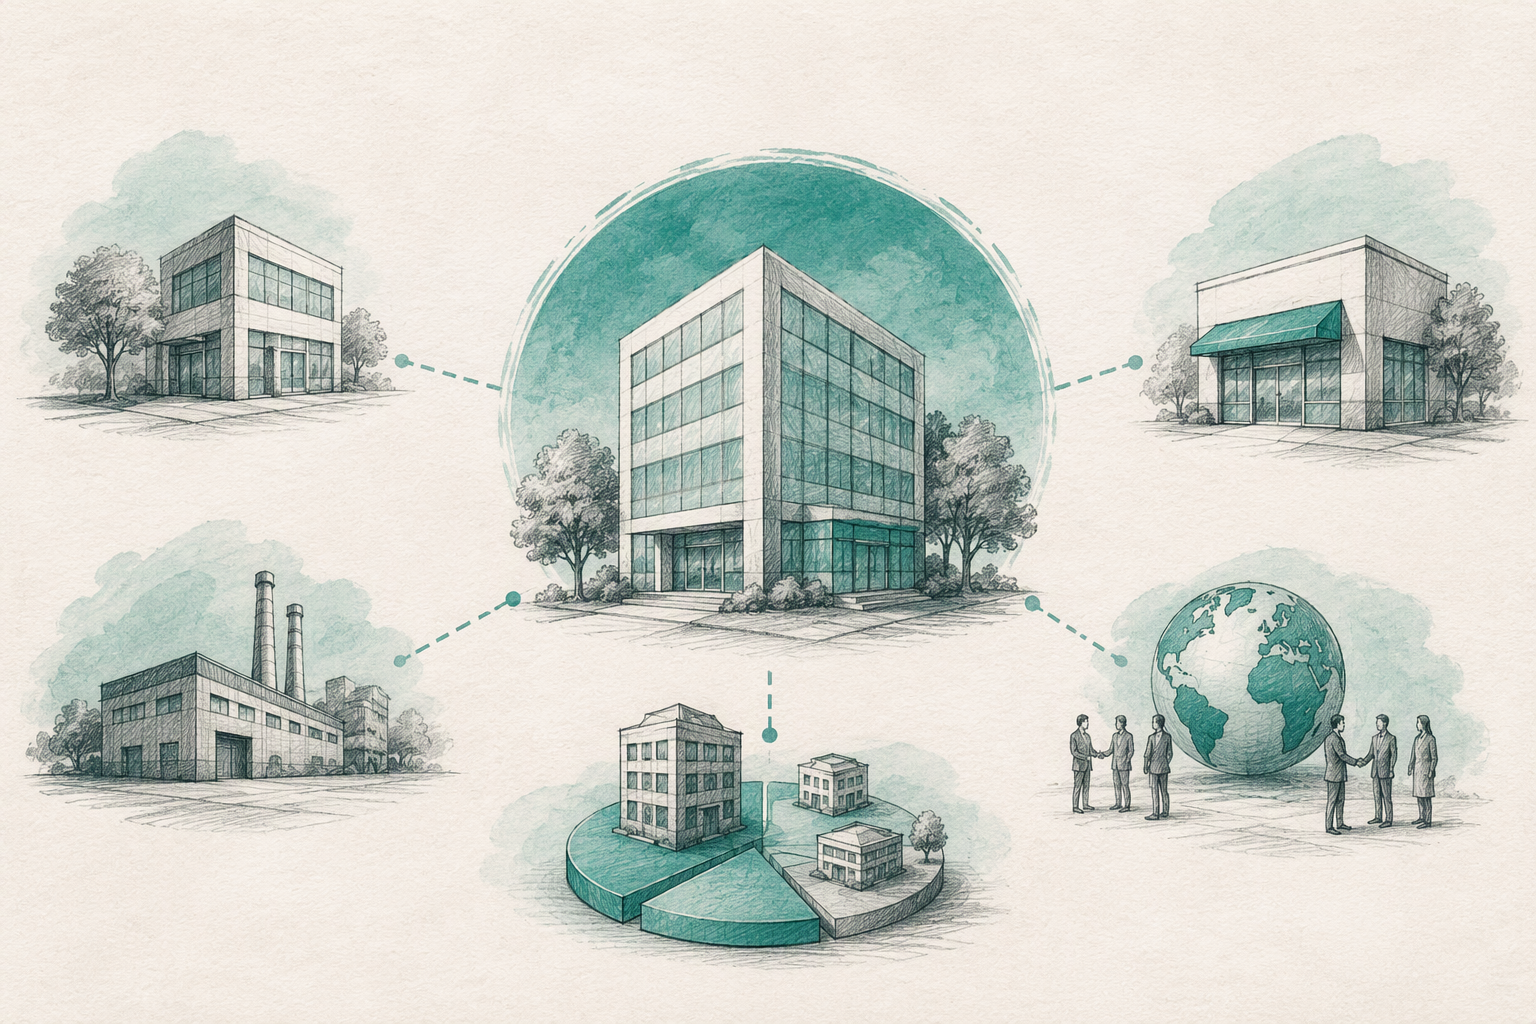
A subsidiary is not interchangeable with a branch, division, affiliate, joint venture, contractor arrangement, or third-party employment model.
| Factor | Subsidiary | Branch | Division | Affiliate or joint venture | Third-party employment model |
|---|---|---|---|---|---|
| Legal identity | Usually separate | Usually part of foreign company | Internal unit | Depends on structure | Provider is legal employer |
| Ownership | Parent controls entity | No separate ownership | No separate ownership | May be shared or related | Client does not own provider |
| Contracting | Signs in its own name | Foreign company contracts through branch | Company signs | Depends on structure | Provider signs employment contract |
| Payroll | Subsidiary is employer | Foreign company is employer | Company is employer | Depends on employing entity | Provider handles employer payroll |
| Governance | Corporate formalities apply | Branch representative | Internal management | Negotiated governance | Service agreement and local rules |
| Closure | Liquidation or deregistration | Branch deregistration | Internal reorganization | Agreed transfer or wind-down | Offboarding process |
“Affiliate” is a broad relationship term. Depending on the relevant definition, it may include parents, subsidiaries, sister companies, or businesses connected through significant ownership.
The right structure depends on the country, planned activity, duration, management authority, regulation, customer requirements, and tax exposure. No option is automatically the safest.
Subsidiary versus branch office
A subsidiary is generally a separate legal company. A branch is usually an extension of a foreign company registered to operate locally.
Both may require registration, bookkeeping, payroll setup, tax filings, and licenses. A branch can expose the foreign company more directly, while a subsidiary brings separate governance and closure obligations.
Subsidiary versus division
A division is an internal business unit rather than a separate company. Its employees, assets, contracts, and debts generally belong to the company containing it.
Businesses use divisions to organize products, regions, or customer groups. Creating one does not establish a separate legal employer or liability boundary.
Subsidiary versus affiliate
A subsidiary may be described as an affiliate because it is related through control. Not every affiliate is a subsidiary, because affiliation does not always require control.
The definition in the relevant contract, statute, or accounting standard governs. This matters when “affiliate” clauses cover data access, confidentiality, guarantees, restrictive covenants, or service rights.
Subsidiary versus third-party employment model
An employer-of-record arrangement may support hiring in some markets without immediately forming an entity. Our guide to what an employer of record is explains the provider’s employer role and the client’s operational involvement.
An EOR is not a universal substitute for a subsidiary. Reviews should consider local employment rules, labor-leasing restrictions, immigration, worker activities, customer requirements, and potential taxable presence.
Contractor status also depends on the working relationship, not just the agreement’s title. Local authorities may consider control, integration, financial dependence, and working methods.
Before choosing, compare the real cost and risk of an EOR versus a foreign subsidiary. A sound comparison includes recurring compliance, operational limits, and exit costs—not only filing fees and monthly service charges.
Does a subsidiary protect the parent company?
A subsidiary’s separate identity can contain many contractual and operational liabilities within that company. Creditors will generally pursue the entity that incurred an obligation or signed the relevant contract.
That separation is not an absolute shield. Parent exposure depends on local law, contractual commitments, actual conduct, and the way the group operates.
When the parent may still face exposure
Potential sources of exposure include:
- Parent guarantees
- Direct parent misconduct
- Joint contractual obligations
- Mixed bank accounts or finances
- Poor entity-level records
- Failure to follow corporate formalities
- Misleading statements about responsibility
- Inadequate funding, where relevant under local law
Courts and regulators may examine actual conduct and control rather than relying only on an organization chart. We would not treat a general explanation of the “corporate veil” as a substitute for country-specific legal advice.
Operational centralization does not erase legal separation
A group can share HR, finance, IT, security, and payroll systems while maintaining separate legal employers. Problems arise when records no longer show which entity is acting.
Contracts, invoices, approvals, bank transfers, employee files, and filings should name the correct company. Shared systems should preserve clear entity attribution.
Governance controls that support separation
Useful controls include:
- Properly appointed subsidiary boards
- Documented shareholder approvals
- Delegated authority rules
- Written intercompany agreements
- Entity-specific accounting records
- Documented capital and loan funding
- Separate registrations and bank flows
Public statements and employee communications should also identify which company employs staff or provides a service.
Using a local subsidiary to hire and run international payroll
A local subsidiary may employ workers, but incorporation does not make it ready to hire or pay them. Employer, tax, social-insurance, pension, insurance, and workplace registrations may still be required.
Payroll administration is distinct from the employer’s legal duties. Employment agreements, statutory benefits, withholding, contributions, immigration, leave, and reporting remain country-specific.
What must happen before the first payday
Our launch checklist typically covers:
- Employer, payroll-tax, social-security, pension, and insurance registrations
- Compliant employment agreements and policies
- Worker notices, benefits, leave rules, and payroll data
- Bank access and payroll funding
- Pay frequency and payslip requirements
- Withholding, returns, and remittance processes
- Data, language, and record-retention requirements
Teams should assign responsibility before issuing offers. Delays in banking, benefits, tax numbers, or payroll registration can prevent compliant payment even after incorporation.
Payroll items founders often underestimate
Payroll can include salary, overtime, holiday pay, bonuses, commissions, expenses, severance, equity awards, and director remuneration. Collective agreements may add further obligations.
The operating model should identify who approves payroll, files each return, funds payments, and handles corrections or penalties. Cross-border funding also introduces currency deadlines and exchange-rate risk.
Sector-specific checks
Staffing businesses may need labor-leasing permissions and clear allocations of workplace and supervision duties. Data-labeling companies should review worker classification, data security, and international transfers.
Property managers may face licensing, insurance, tenant-deposit, rent-collection, and client-money rules. Payroll registration does not resolve these industry requirements.
The real cost and timeline of forming a subsidiary
There is no universal price or timeline for creating a subsidiary. The outcome depends on the country, ownership structure, industry, planned headcount, licensing, document availability, and compliance reviews.
Country-level analysis is essential. For example, whether to open an entity in Mexico or hire without one depends on the operating model, not merely expected headcount.
One-time setup costs
Initial costs may include incorporation, legal and tax advice, translations, notarization, capital, foreign ownership approvals, directors, a registered office, licenses, bank onboarding, payroll implementation, employment documents, benefits, and intercompany agreements.
A low filing quote rarely represents the full launch budget.
Recurring operating costs
Ongoing costs may include bookkeeping, tax returns, statutory accounts, payroll, benefits administration, local directors, insurance, banking, ownership reporting, audits, transfer-pricing support, recordkeeping, and regulatory renewals.
These obligations can continue during slow hiring periods or while an entity is dormant.
Exit and closure costs
Closure may involve employee termination, final payroll, tax clearance, creditor settlement, contract termination, deregistration, liquidation, record retention, and bank closure.
We recommend including a closure reserve in the original business case rather than treating exit as a future problem.
Subsidiary tax, accounting, funding, and reporting obligations
A subsidiary commonly maintains local books, returns, statutory accounts, and filing calendars. Its results may also feed into the parent’s consolidated reporting.
Local activity can create tax exposure before an entity is formed. Opening a subsidiary does not necessarily resolve historical issues or prevent the parent from creating separate exposure through its own activities.
How money moves between parent and subsidiary
Common routes include share capital, intercompany loans, service charges, expense recharges, royalties, dividends, and payroll funding.
These are not casual transfers. Each transaction needs suitable documentation, approval, pricing, and accounting treatment. Withholding taxes, treaty access, deductibility, solvency, and profit repatriation may also require specialist advice.
Transfer pricing and intercompany agreements
Written agreements should cover services, intellectual property, financing, staff support, and expense allocation between group companies.
Transfer-pricing rules vary by country, transaction, and group profile. Unsupported charges can create accounting, tax, and audit problems even where extensive documentation is not required.
Reporting, audit, and ownership disclosures
Compliance teams should confirm requirements for annual accounts, tax returns, beneficial ownership reports, local records, audits, public disclosures, and regulatory reports.
Group reporting does not replace local statutory filings.
When does a subsidiary make sense for international expansion?
There is no universal employee-count threshold that requires every business to incorporate. The decision depends on activity, duration, contracting authority, tax exposure, licensing, immigration, investor expectations, and procurement rules.
For example, businesses deciding whether to open an entity in Colombia before hiring should begin with local operating and employment requirements.
Horizon 1: Testing a market
For an early market test, we assess the planned duration, worker activities, customer commitments, management authority, contractor classification, and possible tax exposure.
A temporary arrangement is not automatically unregulated. Employment, tax, immigration, and licensing rules still apply.
Horizon 2: Scaling a durable local team
Sustained hiring may strengthen the case for a permanent local structure. Relevant factors include management presence, benefits, customer contracts, worker tenure, payroll costs, and third-party employment limits.
Rules differ by market. A review of whether to incorporate in the Philippines or hire without an entity may therefore produce a different answer from the same review elsewhere.
Horizon 3: Regulated or contract-intensive operations
A subsidiary may become more useful when a business needs local licenses, visa sponsorship, domestic contracts, procurement eligibility, property operations, staffing permissions, or local data commitments.
Customers, lenders, investors, or insurers may also request a local entity or parent guarantee. Such requirements can affect both commercial value and parent risk.
Questions to answer before choosing a structure
Before proceeding, we recommend answering:
- Who is the legal employer?
- Which entity signs each contract?
- Where are management decisions made?
- Could local activity create taxable presence?
- Who owns the intellectual property?
- Which entity funds payroll?
- Who documents intercompany charges?
- Which registrations, licenses, benefits, and bank accounts are needed?
- What happens on sale, insolvency, or closure?
- Must the parent guarantee local obligations?
If these answers remain unclear, the entity diagram is not yet an operating model.
Subsidiary FAQ and quick glossary
What does subsidiary mean in business?
A subsidiary is a separate company controlled by a parent company. Subject to local law, it can contract, own property, hire workers, and incur obligations in its own name.
What is a synonym for subsidiary?
“Controlled company” may fit some contexts. “Affiliate” is a common approximation, but it is broader and not always legally equivalent.
How do you pronounce subsidiary, and what is the plural?
A common US pronunciation is “suhb-SID-ee-air-ee.” The plural is “subsidiaries.”
What is the opposite of a subsidiary?
“Parent company” is the usual relational opposite. A company can also be both a subsidiary of one entity and the parent of another.
What does subsidiary mean in government?
It may describe a subordinate, related, or controlled body. The exact meaning depends on the relevant statute, agency, or administrative framework.
Quick glossary
- Parent company: An entity that controls a subsidiary.
- Holding company: A company primarily used to own interests in other companies.
- Affiliate: A related entity; control is not always required.
- Sister company: Another subsidiary controlled by the same parent.
- Branch: A local extension of a foreign company.
- Division: An internal business unit without separate legal identity.
- Joint venture: An operation or entity under shared ownership or governance.
- Permanent establishment: A tax concept under which local activity may create taxable presence.
- Legal employer: The entity responsible for the employment relationship.
- Beneficial owner: The person who ultimately owns or controls an entity under applicable rules.
Plan international hiring beyond incorporation
Before forming a subsidiary, map the complete route from registration to the first payday, recurring compliance, and eventual closure. Talk to Shorpay about building an international payroll operation around the legal employer structure selected with your local advisers.
FAQ
What does “subsidiary” mean?
A subsidiary is a legally separate company controlled by a parent. Control may arise through shares, voting rights, board powers, contracts, or a combination of arrangements.
What is the meaning of subsidiary in one word?
“Controlled” is the closest one-word description, although it is incomplete. A subsidiary is generally a separate legal entity, not simply a controlled department.
Is a subsidiary legally separate from its parent company?
Generally, yes. That separation can contain many liabilities within the subsidiary, but guarantees, direct parent conduct, mixed finances, shared obligations, or local legal rules may still expose the parent.
Does hiring employees abroad require a subsidiary?
Not always. The answer depends on employment rules, worker activities, duration, immigration, licensing, contracts, tax exposure, and lawful third-party employment options in the relevant country.
Can a subsidiary run payroll immediately after incorporation?
Often, further work is required. The company may need employer, tax, social-security, pension, insurance, banking, and payroll registrations before it can pay employees compliantly.