TL;DR
Vesting determines when someone earns nonforfeitable rights to equity or another benefit. Vested equity is not always owned stock: a vested option, for example, may only provide the right to buy shares. We recommend managing approvals, vesting calculations, termination terms, taxable events, and payroll reporting as one controlled process, especially for international teams.
Table of contents
- TL;DR
- What is vesting? Meaning in plain English
- How equity vesting works: A dated example
- Vesting schedule types
- Vested does not always mean owned
- What happens when employment ends?
- Acceleration during an acquisition
- Does vesting trigger tax or payroll obligations?
- Cross-border vesting for international teams
- How founders should track vesting
- FAQ
- Build a reliable vesting and payroll workflow
What is vesting? Meaning in plain English
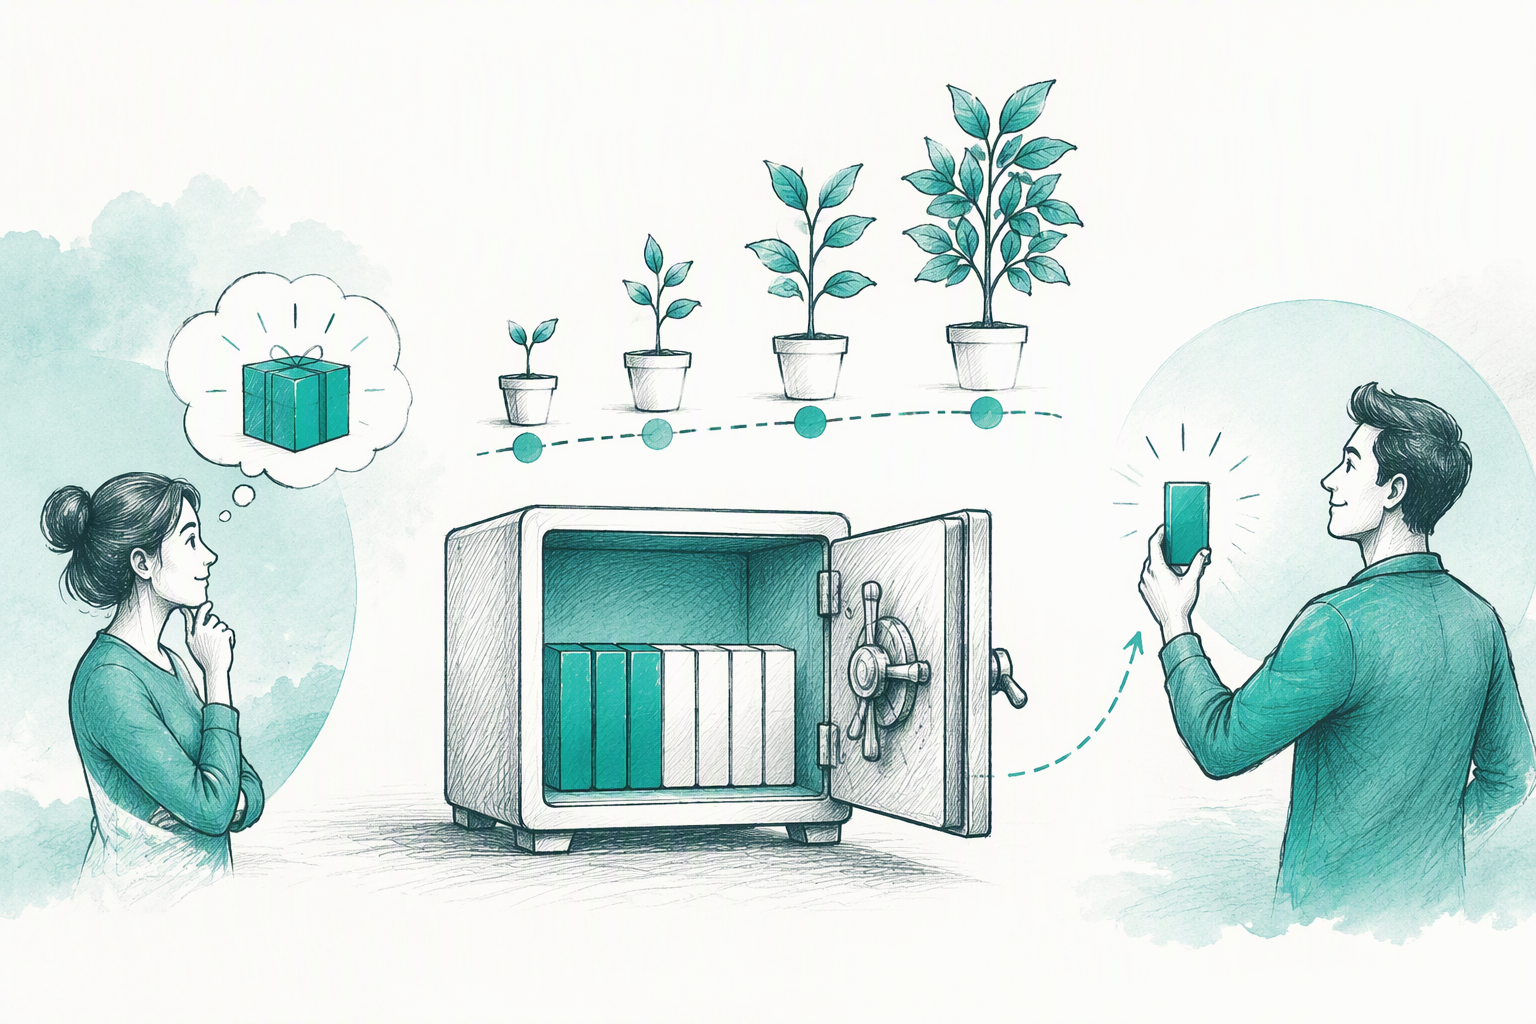
Vesting is the process through which a person earns nonforfeitable rights to equity, retirement contributions, or another benefit. Those rights may accrue over time, after a milestone, or once several conditions have been satisfied.
Companies use vesting to encourage continued contribution, align workers and investors, and prevent departing workers from retaining unearned equity. The plan and award documents control the schedule.
The central caveat is simple: vested does not always mean owned. A vested option may only give its holder the right to purchase shares later.
Vested versus invested
“Vested” means a right has been earned and is no longer subject to forfeiture under the relevant terms. “Invested” means money or assets have been committed in pursuit of a return.
Someone can be vested in company stock options while also being invested in an index fund. The words describe different financial and legal positions.
Vesting in the context of investments
Employee benefit vesting concerns when rights become nonforfeitable. Securities bought through an ordinary brokerage account generally belong to the purchaser without an employment-based vesting period.
Purchased investments can still be subject to settlement rules, lockups, transfer restrictions, or securities laws. Those limitations are not the same as vesting.
How equity vesting works: A dated example
Assume an employee receives 48,000 options on January 15, 2026. The award vests over four years, with a one-year cliff followed by monthly vesting.
Nothing vests before January 15, 2027. On that date, 12,000 options vest at once. Another 1,000 vest each month for the next 36 months.
| Date | Service point | Vested options | Unvested options |
|---|---|---|---|
| January 15, 2026 | Grant | 0 | 48,000 |
| January 15, 2027 | Cliff | 12,000 | 36,000 |
| July 15, 2027 | 18 months | 18,000 | 30,000 |
| January 15, 2028 | 24 months | 24,000 | 24,000 |
| January 15, 2030 | 48 months | 48,000 | 0 |
This example assumes that the grant date and vesting commencement date are identical. The documents should also address installment dates, rounding, service credit, and partial months.
Leaving before or after the cliff
If the employee leaves before the cliff, none of the options in this example would vest. If employment ends after six monthly installments following the cliff, 18,000 options would be vested and 30,000 would remain unvested.
The last working day does not always settle the calculation. Notice periods, approved leave, service interruptions, and the plan’s definition of continuous service can affect the result.
A common convention, not a universal rule
Startups often use multi-year schedules with an initial cliff, but no single schedule suits every company or role. Prior-service credit, milestone conditions, shorter cliffs, or front-loaded vesting may sometimes be more appropriate.
We recommend modelling early, mid-schedule, and late departures before approving a grant. That makes the retention and dilution effects easier to assess.
Vesting schedule types
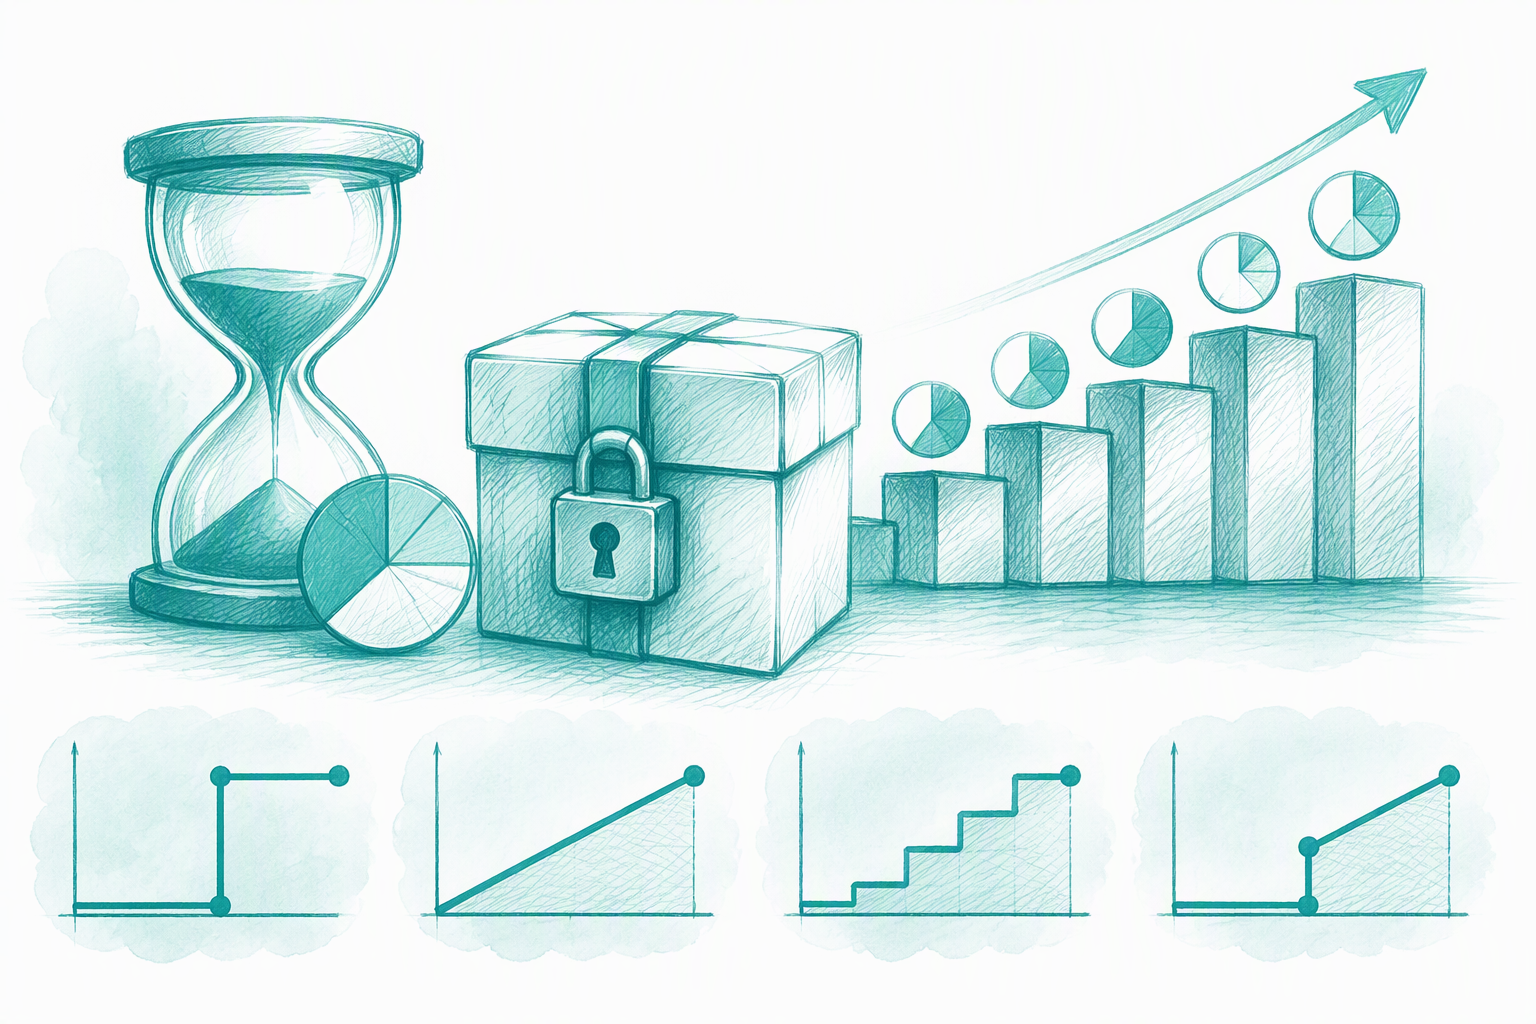
Common vesting structures include:
- Cliff vesting: Nothing vests until a specified date, when part or all of the award vests.
- Graded vesting: Rights accrue in installments over time.
- Monthly or quarterly vesting: Awards vest at regular intervals after any cliff.
- Milestone vesting: Vesting depends on an operational, financial, or other defined result.
- Hybrid vesting: Both time and performance conditions apply.
Milestones should be objective and auditable. The documents should state the measurement period, required evidence, and who can confirm that the condition has been met.
Choosing a schedule
We consider seniority, replacement risk, expected contribution timing, local hiring practices, and the balance between cash and equity. Applying identical terms to founders, executives, project specialists, and long-term employees can create poor incentives.
Details that change the calculation
Every award should define its commencement date, frequency, cliff, rounding method, treatment of partial periods, leaves, service interruptions, and prior-service credit.
Board approvals, signed agreements, grant records, and cap-table entries must agree. A clean cap table cannot fix an incorrectly approved or documented grant.
Vested does not always mean owned
Grant, vesting, exercise, settlement, ownership, and sale are separate events. The legal documents matter more than a dashboard label.
| Award | What vesting generally provides | When shares may be owned |
|---|---|---|
| Stock option | An earned right to buy shares | After exercise and issuance |
| Restricted stock | Release from forfeiture or repurchase risk | Potentially from grant |
| RSU | Satisfaction of specified conditions | After settlement into shares |
Stock options
A vested option is not automatically a share. The holder may still need to exercise, pay the strike price, cover applicable taxes, follow company procedures, and act before the option expires.
Some plans allow early exercise. Shares may then be issued while remaining subject to repurchase or forfeiture under the original schedule.
Restricted stock and founder reverse vesting
Restricted stock may be owned at grant but subject to a company repurchase right. As the stock vests, that right generally falls away for the vested portion.
Founder reverse vesting commonly uses this structure. If a founder leaves early, the company may be entitled to repurchase the unvested shares under the agreement.
RSUs
RSUs are contractual units rather than issued shares. Vesting satisfies specified conditions, while settlement converts the units into shares or another form of value.
Those events can occur on different dates, affecting ownership, withholding, and reporting.
What happens when employment ends?
Unvested awards commonly stop vesting and are forfeited or repurchased, depending on the award. Vested options may remain exercisable only for the period stated in the documents.
Resignation, dismissal, disability, death, retirement, and approved leave may receive different treatment. We recommend giving departing workers exact quantities, dates, procedures, and deadlines rather than saying only that they “keep what is vested.”
Post-termination exercise periods
A former employee may need to fund the strike price and taxes within a limited period. Missing the contractual deadline can cause vested options to lapse.
Confirm the effective service termination date, option expiration date, exercise process, and notification requirements for each departure.
Founder departures and repurchase rights
For a departing founder, calculate vested and unvested shares as of the legally effective date. Then review the repurchase price, approval process, payment terms, and transfer documents.
The cap table should be updated only after the required repurchase or cancellation steps are completed.
Acceleration during an acquisition
Acceleration allows some or all of an award to vest early after a specified event. It is a negotiated protection, not an automatic benefit.
Single-trigger acceleration
Single-trigger acceleration applies after one event, commonly a change of control. Alternatives include partial acceleration or acceleration only when a buyer does not assume or replace the award.
Double-trigger acceleration
Double-trigger acceleration generally requires both a change of control and a qualifying termination. It can protect a worker who loses a role while preserving the retention incentive if employment continues.
The agreement should define the triggers, protection period, qualifying termination, and accelerated portion clearly.
Does vesting trigger tax or payroll obligations?
Equity events can create compensation income, withholding, employer reporting, social contribution, and cash-funding obligations. The timing depends on the award, transaction, individual, and jurisdiction.
Relevant events may include a restricted stock grant or vesting date, option exercise, RSU settlement, share sale, or relocation during the vesting period.
83(b) elections
Some US taxpayers receiving eligible property may be able to elect taxation at transfer rather than as restrictions lapse. The election is subject to a strict filing deadline and is not generally available for standard RSUs because no property is transferred at grant.
Whether an election makes sense depends on value, purchase price, forfeiture risk, liquidity, and personal tax circumstances. We recommend obtaining individual tax advice promptly.
Payroll touchpoints
Restricted stock, option exercises, and RSU settlements can receive different tax treatment. A later share sale may create another reporting event.
Our preferred process reconciles legal, tax, cap-table, and payroll data before processing—not after payroll closes.
Cross-border vesting for international teams
US templates and tax assumptions should not be copied across countries. Residence, work location, employment status, mobility, and award type can change the legal, tax, and payroll result.
Before a grant, exercise, settlement, departure, or relocation, confirm local withholding, social contributions, securities requirements, exchange controls, and the responsible group entity.
For distributed teams, an international payroll platform built for founders can help maintain consistent worker and payroll records. Legal and tax advisers should still determine the award’s treatment.
How founders should track vesting
We recommend one controlled workflow from board approval through acceptance, vesting, taxable events, and termination.
Track each worker’s entity and location alongside the award type, quantity, price, currency, schedule, approvals, amendments, settlements, withholding, repurchases, and post-termination deadlines.
On departure:
- Confirm the effective service termination date.
- Calculate vested and unvested quantities.
- Review forfeiture, repurchase, acceleration, and exercise terms.
- Notify the appropriate payroll team.
- Provide written quantities and deadlines.
- Reconcile completed actions with the cap table.
Build a reliable vesting and payroll workflow
Before issuing the next grant, document its schedule, departure outcomes, tax touchpoints, and country-specific payroll responsibilities. Get started with Shorpay to organize international worker and payroll records and coordinate equity-related payroll events with your advisers.
FAQ
Are vested options the same as owned shares?
No. Vested options generally provide the right to buy shares under the award terms. Ownership usually begins after a valid exercise and issuance.
Can a company change a vesting schedule?
Possibly. The answer depends on the plan, award agreement, required approvals, holder consent, and applicable law. Any amendment should be reflected consistently in company records and worker communications.
What does vested mean in a retirement plan?
It means the relevant balance belongs to the participant under the plan terms. A worker’s own contributions are generally vested, while employer contributions may follow a separate schedule.
Is a particular vesting schedule legally required?
Not universally. The appropriate schedule depends on the role, retention objective, award type, hiring market, company needs, and applicable law.